
How to start accepting online payments for your small business
April 22, 2026
TL;DR:
- Setting up reliable online payments requires a bank account, a payment gateway, a website, and PCI compliance.
- Choosing the right provider depends on volume, sales channels, and platform integration; test thoroughly before going live.
- Small businesses should keep checkout simple, offer multiple payment options, and focus on trust signals to boost conversions.
Losing a sale because a customer couldn’t pay their preferred way is painful, and it happens more often than most small business owners realize. Checkout abandonment is one of the most common conversion killers in eCommerce, and limited or clunky payment options are a leading cause. The good news: setting up reliable, flexible online payments is more straightforward than it used to be. In this guide, we walk you through what you need to get started, how to configure your setup step by step, what fees to watch for, and how to optimize your checkout for both trust and sales.
Table of Contents
- What you need to start accepting payments online
- Step-by-step: Setting up online payment solutions
- Common pitfalls and additional fees to watch for
- Optimizing your payment flow for sales and customer trust
- Why most small businesses overcomplicate online payments (and what actually works)
- Level up your online payments with SensePass
- Frequently asked questions
Key Takeaways
| Point | Details |
|---|---|
| Start with essentials | You only need a reliable payment provider, bank account, and compliance basics to begin accepting payments online. |
| Mind total costs | Compare rates and hidden fees because the cheapest solution will depend on your sales volume and transaction mix. |
| Optimize the checkout flow | A streamlined, trustworthy checkout experience drives more completed sales and greater customer loyalty. |
| Prepare for edge cases | Test technical scenarios like refunds, international payments, and duplicate prevention before going live. |
What you need to start accepting payments online
Before your first transaction goes through, four foundational elements need to be in place: a business bank account, a payment gateway, a website or eCommerce platform, and basic PCI compliance. Miss any one of these, and your checkout experience will either fail or expose you to unnecessary risk.
A payment gateway acts as the digital bridge between your customer’s payment method and your bank account. It encrypts and authorizes each transaction in real time. If you’re unfamiliar with how these work or which type fits your business, reviewing the types of payment gateways is a solid starting point. Understanding why use payment gateways also helps clarify how they reduce fraud risk and improve authorization rates.
PCI compliance (Payment Card Industry Data Security Standard) means your systems meet the security standards required to handle card data. Most hosted payment providers handle the heavy lifting here, but you’re still responsible for keeping your own environment secure.
Here’s a quick look at the most popular providers for small businesses in 2026:
| Provider | Best for | Typical online rate |
|---|---|---|
| Stripe | Online-first businesses | 2.9% + 30¢ per transaction |
| Square | Hybrid/in-person and online | 2.6% + 15¢ in-person |
| PayPal | Fast setup and customer trust | 3.49% + 49¢ online |
| Helcim | Volume discounts, growing stores | ~2.4% avg (interchange-plus) |
According to NerdWallet’s processor comparison, each of these providers serves a different use case. Stripe excels for online sales, Square works well for hybrid models, PayPal is recognized and trusted by consumers, and Helcim rewards you with lower rates as your volume grows.
Must-have checklist before going live:
- Business bank account linked to your provider
- Verified merchant account with your payment processor
- SSL certificate on your website (HTTPS)
- PCI-compliant checkout flow
- Refund and dispute policy clearly published
- Test transaction completed successfully
Pro Tip: Choose a payment solution that’s already pre-integrated with your eCommerce platform. If you’re on Shopify, WooCommerce, or Magento, look for a gateway with a native plugin. It cuts your setup time significantly and reduces the chance of integration errors.
Step-by-step: Setting up online payment solutions
Getting from zero to live payments takes five clear steps. The process is the same regardless of which provider you choose, though the interface and timeline vary.
-
Choose your payment provider. Consider your monthly volume, whether you sell in person or online only, and which platform your store is built on. Review setting up ecommerce payment gateways to understand which gateway models fit omnichannel businesses.
-
Open a merchant account. Most modern providers (Stripe, Square, PayPal) combine the gateway and merchant account into one product. You sign up, verify your business identity, and connect your bank account. Helcim requires a bit more documentation but offers better interchange-plus pricing in return.
-
Integrate with your website or store. This usually means installing a plugin, adding an embed code, or using an API. Platforms like Shopify, BigCommerce, and WooCommerce have one-click integrations with most major providers. For custom builds, Stripe’s API is widely regarded as the most developer-friendly. Understanding payment processor differences can help you decide which technical approach suits your team.
-
Configure your checkout flow. Set up your product catalog, shipping options, and tax rules. Choose which payment methods you’ll accept: cards, digital wallets, buy now pay later (BNPL), or bank transfers.
-
Test thoroughly, then go live. Every provider offers a sandbox or test mode. Use it.
| Step | Stripe | PayPal | Square | Helcim |
|---|---|---|---|---|
| Account setup | Minutes | Minutes | Minutes | 1-2 days |
| Integration options | API, plugins | Buttons, plugins | Dashboard, API | API, plugins |
| Sandbox/test mode | Yes | Yes | Yes | Yes |
| Time to first live payment | Same day | Same day | Same day | 1-3 days |
If you process $10,000 in monthly online sales across 200 transactions, your annual processing costs break down like this: Helcim at roughly $3,120, Stripe or Square at around $4,200, and PayPal at approximately $5,364. That’s a $2,000+ gap annually, which is real money for a small business.
Pro Tip: Always run test transactions in sandbox mode before going live. Test a successful payment, a declined card, and a refund. Catching errors before real customers do saves you from support headaches and lost trust.
Common pitfalls and additional fees to watch for
The base processing rate you see advertised is rarely the only cost you’ll pay. Most small business owners are surprised by what shows up on their first few statements. Knowing what to watch for protects your margins.
Hidden fees that appear in real-world usage:
- Chargebacks: Stripe charges $15 per dispute, PayPal charges $20, and Square charges nothing. However, too many chargebacks carry consequences far worse than the fee itself.
- International transactions: Expect an extra 1% to 1.5% on top of your standard rate.
- Currency conversion: Cross-border sales can add another 1% to 4% depending on the provider and currency pair.
- PCI or statement fees: Some processors charge $5 to $30 per month for compliance administration or paper statements.
- Instant payouts: If you need funds in your account immediately rather than waiting the standard 1-2 business days, expect to pay 1% to 1.75% extra.
All of these hidden fees are confirmed across major providers and can significantly affect your net revenue if you’re not budgeting for them.
Chargebacks deserve special attention. A chargeback occurs when a customer disputes a charge directly with their card issuer rather than requesting a refund from you. Industry chargeback rates typically fall between 0.5% and 1%, but exceeding the 0.9% to 1% threshold triggers penalties from card networks and can put your merchant account at risk.
“Exceeding a 1% chargeback rate triggers formal review and potential penalties from most payment processors. Proactive customer support and clear refund policies are the most effective tools for keeping that number low.”
Here’s a quick checklist for reducing payment processing costs and staying compliant:
- Review your processing statement monthly, not just quarterly
- Flag any new line items and ask your provider to explain them
- Use fraud detection tools and address verification (AVS)
- Maintain clear, visible refund and return policies
- Respond to disputes promptly and with documentation
- Follow retail payment security tips to minimize exposure
Optimizing your payment flow for sales and customer trust
Once your payments are live and your fees are under control, the next goal is converting more of the customers who reach your checkout. Checkout design has a direct impact on your sales, and small changes can produce measurable gains.
Keep the checkout short and clean. Every unnecessary field or extra page is a friction point that can push a customer away. Aim for a single-page or two-step checkout at most. Auto-fill, guest checkout, and address lookup tools all reduce the effort a customer needs to complete a purchase.
Offer multiple payment methods. Customers increasingly expect to pay their way. That means cards, yes, but also digital wallets like Apple Pay and Google Pay, BNPL options like Klarna or Afterpay, and bank transfers where relevant. Optimizing checkout for conversions means meeting customers where they are, not forcing them into a single payment lane.
Display trust signals prominently. A visible SSL badge, recognizable payment method logos, and a clear refund policy all reduce the anxiety that causes last-minute abandonment. Place these near your payment fields, not buried in the footer.
Build in technical resilience. Payment flows have edge cases that can quietly cost you orders. International ecommerce edge cases include webhook retries that need idempotency keys to prevent duplicate orders, international refunds issued in presentment currency that risk FX losses if exchange rates shift between purchase and refund, and local payment methods like SEPA that require additional fields such as an IBAN. Test these scenarios before you start selling internationally.
Checkout optimization checklist:
- Offer at least 3 payment methods (card, wallet, BNPL)
- Display security badges near the payment form
- Show final price including all fees before the customer confirms
- Enable guest checkout
- Test the full flow on mobile before launch
- Review your streamline checkout strategies to identify further improvements
Pro Tip: Test your international checkout flow from a different country using a VPN. You’ll often catch currency display issues, missing payment methods, or blocked cards that your domestic testing would never reveal.
Why most small businesses overcomplicate online payments (and what actually works)
Here’s something we see repeatedly: small business owners spend weeks researching the “perfect” payment stack, chasing features they won’t need for years, and end up delaying their launch or overbuilding their integration. The irony is that complexity itself becomes a barrier to sales.
For most businesses processing under $20,000 a month, a flat-rate processor like Stripe or Square, connected directly to your existing platform, is genuinely sufficient. The role of payment gateways at this stage is simple: authorize transactions reliably and keep your customers moving through checkout.
The shift to interchange-plus pricing makes financial sense when your monthly volume consistently exceeds $25,000 to $30,000. Below that, the savings rarely justify the added complexity of managing a separate merchant account and reconciling interchange categories.
Focus instead on integration quality and customer experience. A seamless checkout on your existing eCommerce platform will outperform a technically sophisticated but fragmented payment stack every time. Start simple, measure your conversion rates, and scale your payment infrastructure only when your volume demands it.
Level up your online payments with SensePass
If you’re ready to move beyond a single-provider setup, SensePass gives you an orchestration layer that connects your store to a broad range of payment methods without rebuilding your tech stack.
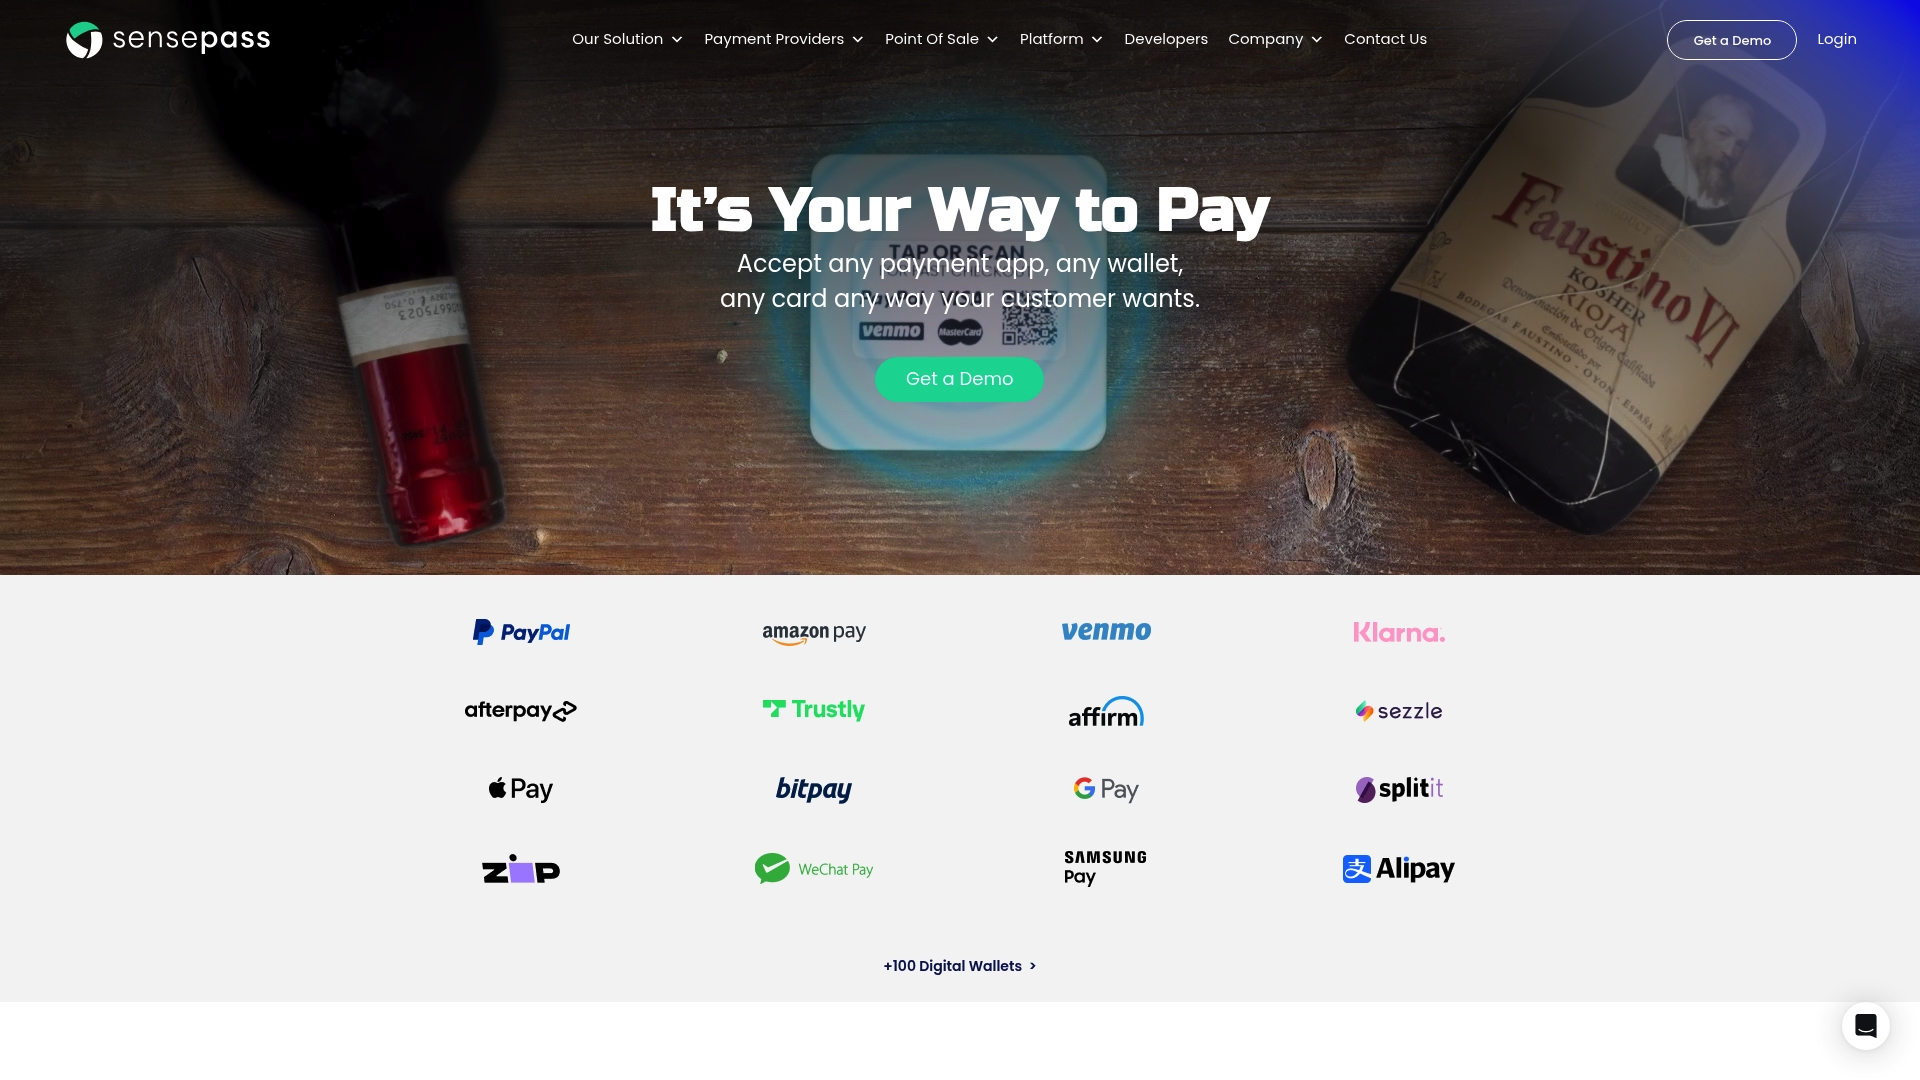
SensePass integrates with major platforms including NetSuite, Oracle Xstore, Aptos, Shopify POS, BigCommerce, NCR, and Dynamics365. It supports digital wallets (Apple Pay, Google Pay, PayPal, Venmo, Alipay), BNPL options (Klarna, Afterpay, Sezzle, Splitit), financing via Affirm and WeGetFinancing, crypto through BitPay and Coinbase, and pay-by-bank solutions like Trustly. SensePass is also processor-agnostic, connecting to 50+ card processors. Explore omnichannel payments for retailers to see how it fits your setup, or review our payment gateway selection tips to make your next move with confidence.
Frequently asked questions
What is the cheapest way for small businesses to accept payments online?
For higher-volume businesses, Helcim’s interchange-plus model costs roughly $3,120 annually on $10,000 monthly sales, compared to $4,200 for Stripe or Square. For lower volumes or simpler needs, Stripe or Square are the easiest and most cost-effective starting point.
How can I minimize chargebacks and related fees?
Keep your chargeback rate below 1% by using fraud detection tools, publishing clear refund policies, and responding to disputes quickly with supporting documentation. Proactive customer communication before disputes are filed is the most effective prevention strategy.
Do I need to accept digital wallets or buy now, pay later methods?
They’re not required, but offering digital wallets and BNPL options consistently lifts conversion rates and can attract customers who would otherwise abandon their cart due to limited payment choices.
What are edge cases I should test before going live?
Test webhook idempotency, international refunds in presentment currency, FX rate exposure, and required local fields like IBAN for SEPA payments. These scenarios are easy to miss in standard domestic testing but can cause real order and reconciliation issues at scale.
Recommended

 New York Office
260 Madison Ave Suite 8018 New York NY 10016

