
Afterpay Walmart Online: What Retailers Should Know
May 18, 2026
TL;DR:
- Walmart does not support Afterpay at checkout; its current BNPL partner is Klarna through OnePay Later. Consumers and retailers must understand that alternative workarounds for Afterpay are limited, unreliable, and often restricted by category or device. Clear messaging about supported BNPL options helps prevent shopper confusion, reduces support volume, and safeguards conversion rates.
Searching for Afterpay Walmart online options leads to one of the most common checkout misconceptions in retail today. Shoppers expect to find Afterpay at Walmart’s checkout, and when it isn’t there, carts get abandoned and support tickets pile up. If you’re managing a retail brand or overseeing an ecommerce operation, understanding exactly which buy now pay later options Walmart supports, and why Afterpay isn’t one of them, directly affects your payment strategy, customer messaging, and BNPL integration decisions.
Table of Contents
- Understanding Walmart’s BNPL landscape and Afterpay’s role
- Workarounds for using Afterpay at Walmart online and in-store
- Preparing your retail and ecommerce systems for BNPL integration choices
- Executing BNPL payments at Walmart: Shopper and merchant best practices
- Verifying and optimizing BNPL payment success at Walmart
- Why assuming Afterpay integration at Walmart is a costly mistake for retailers
- How SensePass powers seamless omnichannel payment integration including BNPL options
- Frequently asked questions
Understanding Walmart’s BNPL landscape and Afterpay’s role
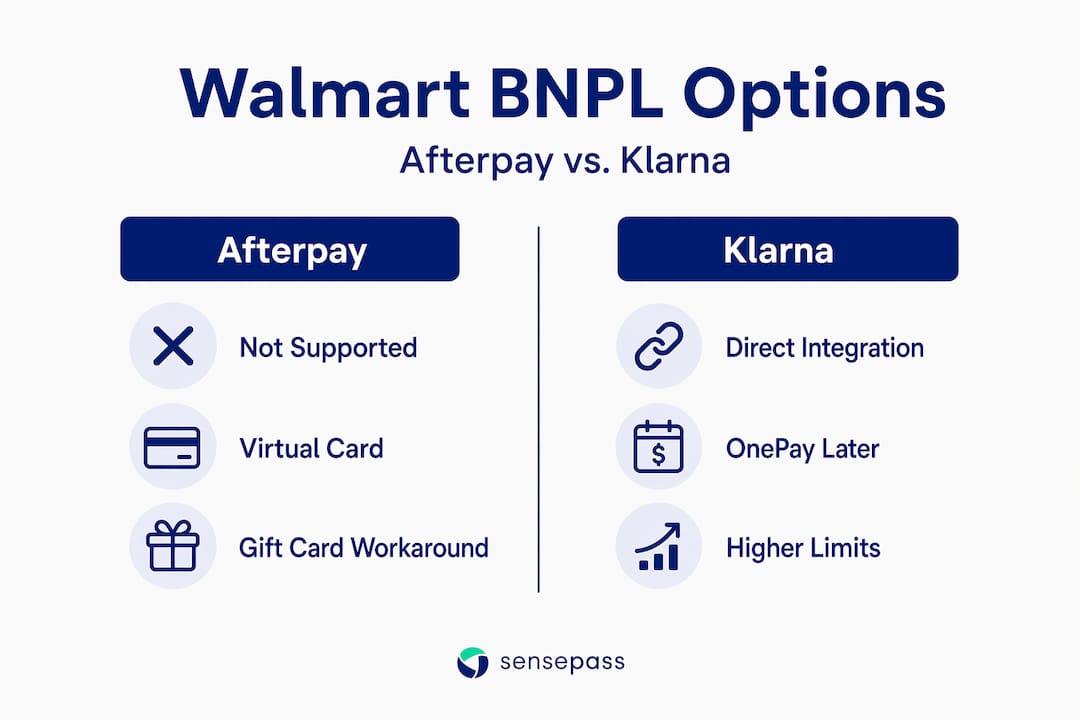
Let’s clear this up immediately. Walmart does not integrate Afterpay at checkout, either online or in-store. The retailer’s current BNPL partner is Klarna, specifically through a product called OnePay Later.
OnePay Later lets approved Walmart shoppers split purchases ranging from $50 to $6,000 into up to three payments. It’s available on Walmart.com, the Walmart app, and at physical registers. This is the official, supported path for Walmart buy now pay later.
The transition to Klarna is recent. Walmart switched its BNPL provider from Affirm to Klarna in 2025, a move that surprised many in the payments industry given Affirm’s long-standing relationship with the retailer. This kind of provider shift is exactly why assuming any single BNPL brand is permanently embedded in a major retailer’s checkout is a risk.
Current Walmart BNPL options at a glance:
| BNPL Provider | Status at Walmart | Notes |
|---|---|---|
| Klarna (OnePay Later) | Active (2025 onward) | Online, app, and in-store |
| Affirm | Former provider | No longer active at Walmart |
| Afterpay | Not integrated | No direct checkout support |
| Sezzle / ZIP | Not integrated | Workarounds only |
- Walmart’s BNPL approval process runs a soft credit check, so shoppers aren’t guaranteed approval.
- Purchase limits ($50 minimum, $6,000 maximum) exclude everyday grocery runs.
- Payment schedules are emailed to shoppers after approval.
Pro Tip: If you’re an ecommerce manager using Klarna at checkout on your own platform, you already understand the approval flow. Apply that same knowledge to set accurate expectations when shoppers ask about Walmart and afterpay in the same breath.
Having established the current BNPL partnerships at Walmart, let’s explore how consumers and retailers can work around Afterpay’s absence.
Workarounds for using Afterpay at Walmart online and in-store
The absence of direct Afterpay integration doesn’t mean shoppers have zero options. Several workarounds exist, but each comes with real limitations that you and your support team need to understand.
Three primary workarounds for Afterpay with Walmart:
- Afterpay virtual card. The Afterpay app generates a virtual Mastercard that functions like a debit card. Shoppers can load funds, then use this card as a payment workaround at select Walmart locations that accept tap-to-pay or card entry. Acceptance is not guaranteed, and Walmart’s system doesn’t always recognize it.
- Single-use virtual cards. Within the Afterpay app, shoppers can generate a single-use virtual card number for a specific purchase. These virtual cards can sometimes be used online at Walmart, but category restrictions and spending limits still apply.
- Walmart gift cards via Afterpay-supported retailers. Some third-party retailers accept Afterpay and sell Walmart gift cards. A shopper could technically buy a gift card through an Afterpay-supported merchant, then use that gift card at Walmart. It’s indirect, adds friction, and most shoppers won’t bother.
Limitations you should communicate clearly:
- Afterpay virtual cards don’t work at every Walmart terminal.
- Category restrictions apply. Groceries, fuel, and certain electronics are commonly excluded.
- Fees may apply depending on Afterpay account status.
- Spending limits on the virtual card may not align with the shopper’s intended cart value.
- Customer support burden increases when shoppers attempt these workarounds and fail.
Afterpay workaround comparison:
| Method | Works online? | Works in-store? | Reliability |
|---|---|---|---|
| Afterpay virtual card | Partial | Partial | Low to moderate |
| Single-use virtual card | Sometimes | No | Low |
| Gift card via third party | Yes | Yes | Moderate, high friction |
Pro Tip: If shoppers on your platform are asking about afterpay on walmart, redirect them proactively in your FAQ and checkout help copy. One clear sentence saves multiple support conversations.
Preparing your retail and ecommerce systems for BNPL integration choices
Here’s where it gets strategic. Most checkout-related shopper frustration isn’t a payment problem. It’s a messaging problem. If your website, app, or store materials suggest that Afterpay works at Walmart, you’re setting shoppers up for a failed transaction and a damaged experience.
BNPL roadmap decisions should prioritize currently supported providers over assumptions about brand interchangeability. Klarna is not Afterpay. Affirm is not Klarna. Each has its own approval criteria, transaction limits, and supported merchant categories.
Practical preparation steps for retail and ecommerce managers:
- Audit your existing BNPL payment options copy. Remove any reference to Afterpay at Walmart that isn’t explicitly labeled as a workaround.
- Update POS terminal prompts and digital signage to reflect Klarna/OnePay Later as the current Walmart option.
- When connecting alternative payment methods to your own platform, document which BNPL providers are active and review that documentation quarterly.
- If you operate near Walmart or run a platform that serves Walmart sellers, align your SuiteCommerce BNPL integration to match current retailer partnerships.
- Assign someone to monitor BNPL provider news. The switch from Affirm to Klarna happened within a single contract cycle. Another shift could happen just as quickly.
Pro Tip: Build a simple internal “BNPL status sheet” that lists every payment provider your platform supports, their active retail partners, and the date you last verified the information. Review it every quarter.
Executing BNPL payments at Walmart: Shopper and merchant best practices
For shoppers, the OnePay Later checkout process at Walmart is straightforward when it works correctly. Understanding the steps prevents common drop-off points.
Shopper steps for OnePay Later at Walmart:
- Add items to cart (minimum $50 required).
- Select OnePay Later at checkout (online, app, or in-store register).
- Complete Klarna’s soft credit approval.
- Choose a payment plan if more than one option is offered.
- Confirm the order and receive payment schedule by email, including any down payment details.
Merchant and staff preparation:
- Train store associates to recognize OnePay Later as the correct Walmart BNPL option. Staff should not tell customers to use Afterpay, even as a suggestion.
- Verify that your POS software and contactless payment methods are current with Klarna’s integration requirements.
- Educate your team on which product categories are excluded from BNPL at Walmart. Groceries and fuel are almost always restricted.
Common BNPL transaction issues and resolutions:
| Issue | Likely cause | Resolution |
|---|---|---|
| BNPL option not appearing | Category not eligible | Confirm item eligibility |
| Payment declined | Credit check failed | Suggest alternative payment |
| Cart under minimum | Amount below $50 | Add items or pay in full |
| Afterpay not accepted | Not integrated at Walmart | Direct shopper to OnePay Later |
| Payment plan email not received | Email in spam | Check spam folder, re-trigger send |
Pro Tip: Post a brief “How to pay later at Walmart” explainer on any customer-facing materials your brand controls. Even a two-sentence note about OnePay Later versus Afterpay saves confusion at the register.
Verifying and optimizing BNPL payment success at Walmart
Getting the integration right is step one. Keeping it right requires ongoing attention to transaction data and shopper feedback.
Clear communication about supported BNPL options reduces shopper confusion and lowers support volume significantly. But you need to know what’s going wrong before you can fix it.
Key actions for ongoing BNPL verification and improvement:
- Monitor Klarna/OnePay Later transaction success rates monthly. A dip in approval rates may signal a change in Klarna’s underwriting criteria or a product category restriction you missed.
- Survey shoppers who abandoned checkout. Ask specifically whether a payment method issue contributed to the drop-off. You may find Afterpay-related confusion showing up in open-text responses.
- Review your website, app store listings, and omnichannel payment optimization tips to identify any outdated BNPL references.
- Update customer service scripts quarterly. BNPL provider changes at major retailers happen faster than most teams update their internal documentation.
- Work with your payment gateway to get consolidated reporting on BNPL payment outcomes across channels. Fragmented data makes it impossible to see the full picture.
- Build a rapid response process for when BNPL providers change. The 2025 Affirm-to-Klarna switch at Walmart is a model case: retailers who updated messaging quickly lost fewer sales.
Pro Tip: Set a Google Alert for “[BNPL payment options] Walmart” and “[Afterpay alternatives Walmart]”. Real-time news about provider changes gives you lead time to update messaging before shoppers experience it as a checkout problem.
Why assuming Afterpay integration at Walmart is a costly mistake for retailers
Most retail and ecommerce teams don’t lose sales because they have the wrong payment strategy. They lose sales because they communicated the wrong information confidently. The Afterpay-Walmart situation is a textbook example.
Shoppers searching for “afterpay walmart online” aren’t always fringe users. Many are regular Afterpay users who simply assume the service works everywhere. When they reach Walmart’s checkout and find it missing, their next move is usually cart abandonment, not research. Shoppers expecting Afterpay at Walmart often face failed transactions and service frustration precisely because no one corrected that expectation upstream.
The operational cost compounds. Support teams field BNPL questions. Marketing teams don’t update checkout copy fast enough. And somewhere upstream, a retailer assumed all BNPL providers were essentially interchangeable, like assuming every card terminal accepts every wallet app.
The harder lesson here is about velocity. The Afterpay integration insight applies just as much to any BNPL provider: these partnerships are commercial contracts, and they change. Klarna won Walmart’s BNPL contract from Affirm in 2025. There is no reason a future cycle couldn’t bring another shift.
The retailers who protect their conversion rates are the ones who treat BNPL provider status as a live data point, not a set-and-forget configuration. They update checkout messaging when providers change. They train staff before the new integration goes live. And they never let shopper-facing materials lag behind the actual payment options available at checkout.
How SensePass powers seamless omnichannel payment integration including BNPL options
If the Afterpay-Walmart situation reveals anything, it’s that payment optionality and current-provider accuracy both matter. That’s exactly the problem SensePass is built to solve.

SensePass is an orchestration layer and payment gateway for retailers that integrates with major platforms including NetSuite, SuiteCommerce, Oracle Xstore, Aptos, Shopify POS, BigCommerce, Storis, NCR, and Dynamics365. It supports omnichannel payments for retailers across in-store POS, self-checkout, call center, and ecommerce channels. For BNPL specifically, SensePass supports Klarna, Afterpay, Sezzle, ZIP, and Splitit. Digital wallets include PayPal, Venmo, WeChat, Apple Pay, Google Pay, Alipay, and Amazon Pay. Financing options include WeGetFinancing and Affirm. Crypto payments run through BitPay and Coinbase, and pay-by-bank options include Trustly and LinkMoney. SensePass is also processor-agnostic, giving merchants access to 50+ card processors. If you’re reviewing payment gateway selection tips or want to understand what an omnichannel payment strategy actually looks like in practice, SensePass offers the infrastructure to back it up.
Frequently asked questions
Can I use Afterpay directly on Walmart’s online checkout?
No. Walmart does not integrate Afterpay for direct checkout online or in-store, and currently promotes Klarna’s OnePay Later as its official BNPL option.
What is Walmart’s current buy now, pay later option?
Walmart’s BNPL provider is Klarna via OnePay Later, allowing approved shoppers to split purchases between $50 and $6,000 into up to three payments.
Are there any workarounds to use Afterpay for Walmart purchases?
Customers can try Afterpay virtual cards or single-use virtual cards online, or purchase Walmart gift cards through Afterpay-supported retailers, but these methods carry category restrictions, spending limits, and possible fees.
How should retailers handle BNPL payment communication regarding Walmart?
Retailers should clearly communicate supported BNPL options like Klarna and avoid suggesting Afterpay to prevent shopper confusion and reduce incoming support requests.

 New York Office
260 Madison Ave Suite 8018 New York NY 10016

