
Top 5 Best Omnichannel Payment Solutions 2026
March 13, 2026
Managing payments across different touchpoints is no longer a simple task. Businesses now face choices that could shape how customers buy and pay. Some solutions connect online and in-store payments with ease. Others promise faster checkout or smarter security. Finding the right fit can make a big difference for both the business and its customers. The next options might just change the way you think about payments.
Table of Contents
SensePass

At a Glance
SensePass is the clear market leader for retailers that need a single orchestration layer for online and in-store payments. It combines a unified payment hub with fast contactless checkout to reduce wait times and lower processing costs.
Core Features
SensePass accepts a broad range of payment methods and centralizes them into one platform for retail POS, mobile checkout, self-checkout, call center payments, and ERP payments. The platform supports over 101 digital wallets and payment processors and emphasizes fast, contactless experiences.
- Integrations include NetSuite, SuiteCommerce, Oracle Xstore, Aptos, Shopify POS, BigCommerce, Storis, NCR, Dynamics365 and more.
- Payment support covers PayPal, Venmo, WeChat, Apple Pay, Google Pay, Alipay, Amazon Pay, BNPL providers like Klarna, Sezzle, ZIP, Splitit, Afterpay, financing from WeGetFinancing and Affirm, crypto via BitPay and Coinbase, and pay by bank options such as Trustly and LinkMoney.
- SensePass is processor-agnostic, giving merchants access to 50+ card processors for maximum flexibility.
Pros
- Supports a broad range of payment methods: SensePass lets you accept digital wallets, BNPL, crypto, and bank transfers through one platform, reducing checkout friction for customers.
- Seamless platform integrations: It plugs into major POS and ecommerce systems so you keep existing workflows while gaining new payment options.
- Unified dashboard for payment management: Teams can reconcile transactions, monitor conversions, and manage refunds from a single interface.
- Fast contactless checkout: Contactless payments and QR code flows shorten queues and improve in-store throughput.
- Lower transaction and CAPEX costs: Centralized routing and processor choice help reduce processing fees and avoid unnecessary hardware spend.
Who It’s For
Retail chains, omnichannel merchants, and hospitality operators that need consistent payment behavior across online and physical channels will benefit most. You should consider SensePass if you run multiple locations, operate subscriptions, or process high volumes across call centers and ecommerce platforms.
Unique Value Proposition
SensePass stands out because it merges deep platform compatibility with broad payment coverage. The combination of integrations like Shopify POS and Oracle Xstore and support for PayPal, Klarna, BitPay, Trustly, and 50+ processors creates unmatched deployment flexibility. Sophisticated buyers choose SensePass when they need a single control plane that preserves existing processors while adding modern payment methods and reducing total cost of ownership.
Real World Use Case
A regional retail chain implemented SensePass to add contactless and wallet payments at 120 stores while unifying its online checkout. The result was shorter queues, fewer declined transactions through smarter routing, and a single reconciliation process across POS and ecommerce systems.
Pricing
Pricing is not listed on the website and typically requires contacting sales for a quote. Expect fees and plans to vary by transaction volume, chosen processors, and integration scope.
Website: https://sensepass.com
Citcon
At a Glance
Citcon is a global payment platform that consolidates over 100 payment methods into one integration, letting merchants accept local and digital payment types across channels. The platform targets medium and large retailers that need fast rollout and broad market coverage without multiple vendor contracts.
Core Features
Citcon delivers an all-in-one payment API that unifies online, mobile, and in-store acceptance while handling currency and compliance for global operations. Deployment timelines are billed as rapid, with many customers onboarded within one to four weeks.
- 100+ payment methods support for local wallets and alternative payments.
- Global currency support with compliance controls for cross-border acceptance.
- Multi-channel payments covering online checkout, mobile, and brick and mortar stores.
- Rapid deployment typically within 1-4 weeks to accelerate time-to-market.
- Operations automation for reconciliation and back-office workflows.
Pros
-
Single integration simplifies multi-payment processing into a unified API, reducing engineering overhead and vendor management work.
-
Local payment reach expands global coverage by offering many regional payment options, which helps improve conversion in new markets.
-
Cost reduction lowers operational and development expenses by consolidating reconciliation and payment flows into one platform.
-
Quick implementation speeds rollout so merchants can start accepting local methods within weeks instead of months.
-
Versatile vertical support works for eCommerce, retail, and platforms that need both online and offline payments.
Cons
-
Opaque pricing makes it hard for procurement teams to model TCO because public rates and fee structures are not posted on the website.
-
High upfront cost risk with reported implementation bills such as a $5 million setup that could price out smaller merchants.
-
Integration effort required since connecting complex payment routing and reconciliation often needs dedicated development resources.
Who It’s For
Citcon suits medium to large enterprises that plan aggressive international expansion and require broad payment method coverage. Retailers with regional payment preferences or platforms that must combine online, mobile, and in-store acceptance will see the most value.
Unique Value Proposition
Citcon’s main advantage is bundling many local and alternative payment methods behind a single developer-friendly API, reducing time and complexity when entering new markets. That combination of reach and centralized operations is compelling for teams prioritizing speed and scale.
Real World Use Case
A global retailer integrates Citcon to accept over 100 local payment methods across multiple countries. The retailer reduces checkout abandonment in new markets and consolidates reconciliation into one system, trimming staff time spent on manual settlement tasks.
Pricing
Pricing details are not listed publicly and are described as customized to client needs. That means procurement must request a quote and budget for potential high implementation charges in addition to ongoing fees.
Website: https://citcon.com
KOMOJU
At a Glance
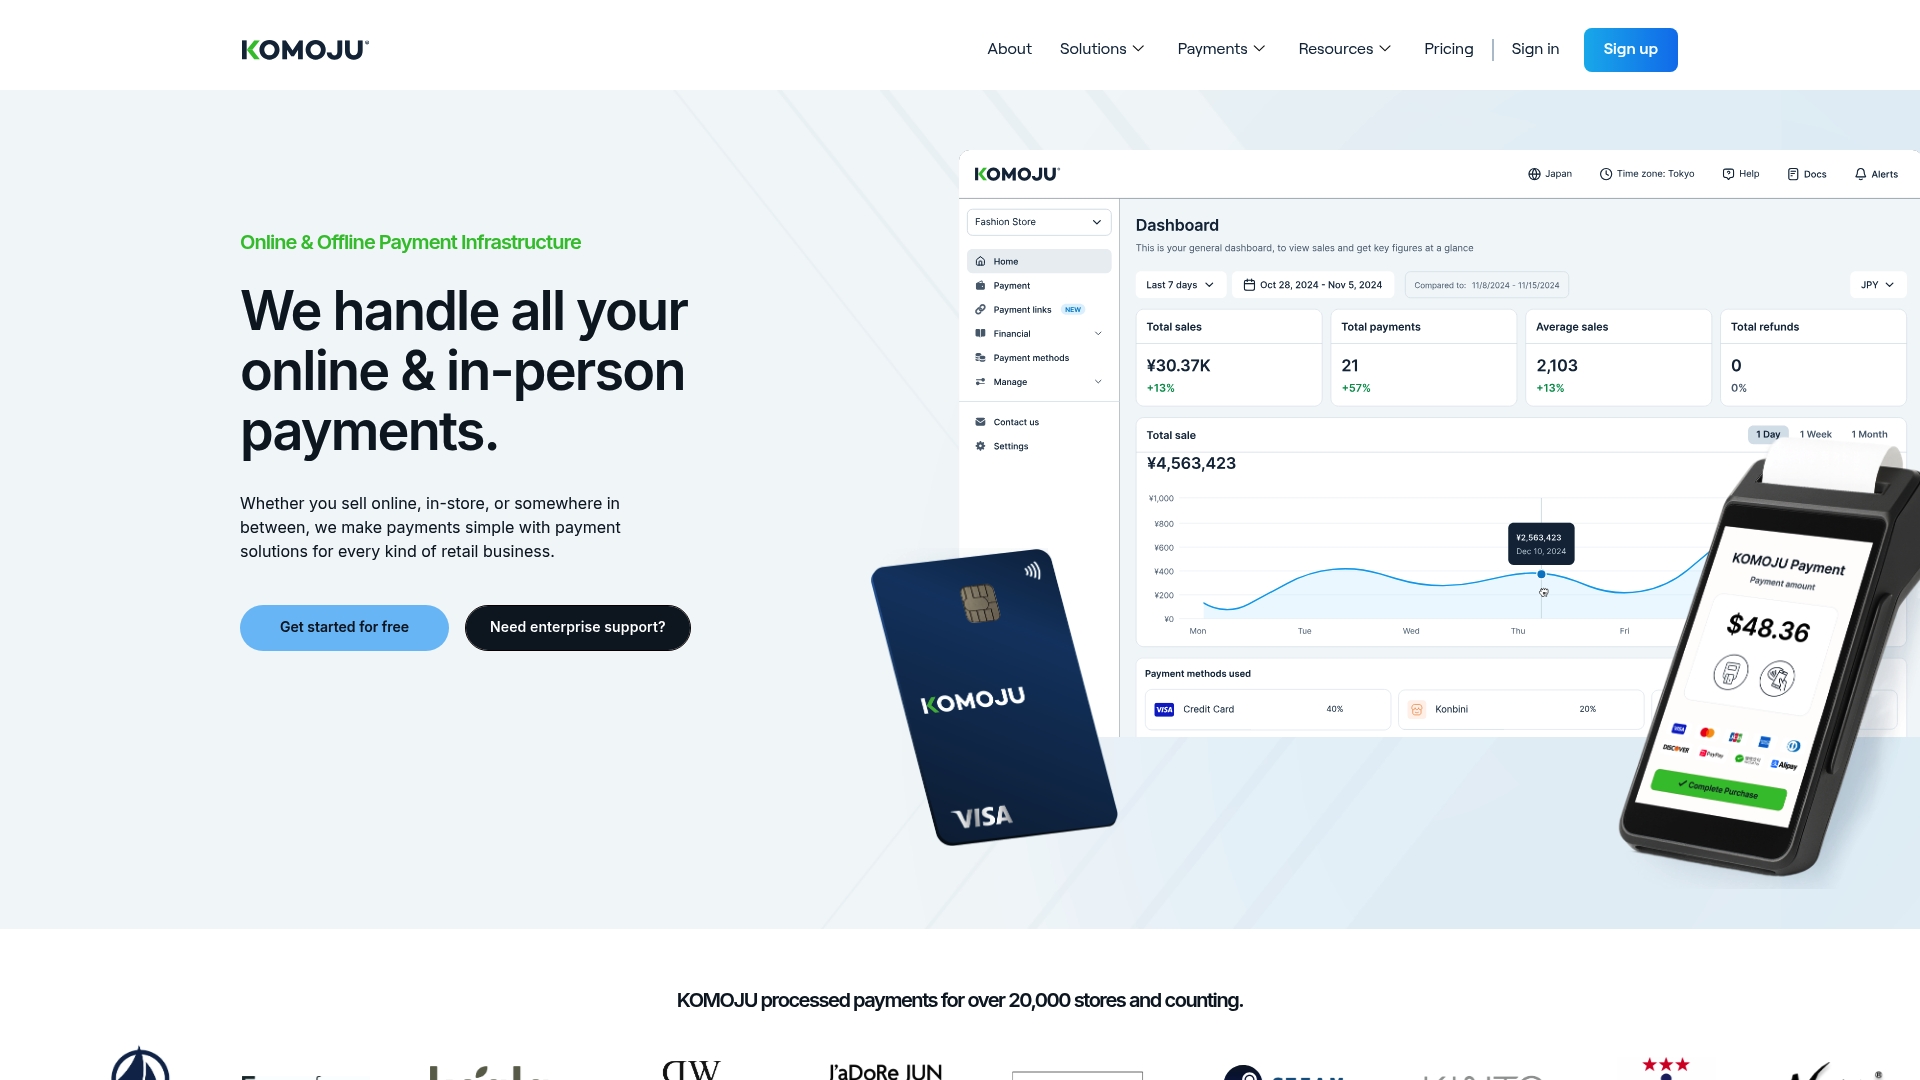
KOMOJU delivers a secure, internationally focused payment platform that supports online and in store sales while offering extensive local payment options. It fits retailers that need broad payment coverage and enterprise grade compliance without sacrificing uptime.
Core Features
KOMOJU supports over 65 payment methods including credit cards, digital wallets, bank transfers, and many local options for global expansion. The platform offers API, hosted pages, hosted fields, SDKs, and no code payment links for flexible integration paths.
- Integrates with Shopify, Wix, WooCommerce, Salesforce, Magento, and more.
- Offers in store acceptance through KOMOJU Terminal and tap to pay capabilities.
- Provides add on solutions such as corporate prepaid cards and payment links.
Pros
- Flexible integration options: Multiple integration choices let development teams build custom flows or use hosted pages for faster launch.
- Wide payment coverage: Support for local and international methods helps merchants reduce checkout friction in new markets.
- Strong security posture: Compliance with PCI DSS Level 1 v4.0 and ISO 27001 protects transaction data and reduces audit exposure.
- Unified online and in store acceptance: The combination of ecommerce connectors and in store terminals keeps sales and reporting consistent across channels.
- High reliability: A reported 99.99 percent uptime means less downtime risk for peak selling periods.
Cons
- Pricing complexity: The transaction based model requires merchants to request detailed pricing which can create evaluation overhead for small businesses.
- Implementation complexity: The breadth of features can require technical resources or vendor support to configure enterprise grade setups.
- Unclear support responsiveness: Public information does not clarify response times which can concern operations teams during incidents.
Who It’s For
KOMOJU suits retailers of all sizes that sell both online and in store and that need broad local payment acceptance across regions. Growth oriented merchants expanding into new countries will benefit most from its payment variety and ecommerce platform integrations.
Unique Value Proposition
KOMOJU combines broad local payment reach with enterprise security and multiple integration methods so merchants maintain control over checkout while supporting regional preferences. That mix helps retailers convert customers in markets where global card usage is not dominant.
Real World Use Case
A Japanese ecommerce retailer uses KOMOJU to process online credit card payments while integrating with Shopify and operating KOMOJU Terminal for in store sales. The retailer consolidates reporting and extends international reach without juggling multiple gateway vendors.
Pricing
KOMOJU uses a transaction based pricing model with detailed rates provided on request. Merchants should request a rate sheet to compare per transaction fees and any add on service charges.
Website: https://komoju.com
Paystand
At a Glance
Paystand offers a blockchain based Payments as a Service platform that targets B2B finance with faster and lower cost transfers. Its strongest claim is no transaction fees on bank payments, which shifts cost dynamics for mid sized and large enterprises.
Core Features
Paystand centralizes accounts and payment flows with strong automation and connectivity.
- Accounts Receivable Automation including automatic reconciliation, collections automation, payment portal, billing and receivables reporting.
- Accounts Payable Automation for AP workflows, international payments, and purchase order approvals.
- Payments Network that supports fee free bank to bank transfers, ACH, Canadian EFT, check scanning, and push payments.
- ERP Integrations with NetSuite, Sage Intacct, Dynamics 365 and similar systems to synchronize financial records.
- Expense Management tools for spend management, corporate cards, procurement, and spend analytics.
Pros
- Zero transaction fees on bank payments: Eliminates per payment fees for bank transfers which can reduce operating costs significantly for high volume B2B billing.
- Comprehensive automation: Automates both receivables and payables which reduces manual reconciliation and accelerates cash application.
- Blockchain technology: Provides secure and immutable payment records that enhance auditability and reduce reconciliation disputes.
- Extensive ERP integrations: Connects with major accounting systems to push and pull transaction data and reduce bookkeeping errors.
- Subscription pricing model: Predictable subscription charges make budgeting easier compared with per transaction models.
Cons
- Limited information on real time customer support or onboarding makes it harder to predict implementation experience for teams without in house payments expertise.
- Feature set focuses on organizations already using ERP systems which makes the platform less suitable for small businesses or those without an ERP.
- The complexity of a blockchain based architecture can represent an unnecessary technical burden for companies with simple payment needs.
Who It’s For
Paystand fits mid sized to large enterprises that want to reduce B2B payment costs and automate cash cycles. Organizations that already run ERP systems and need tight reconciliation and faster bank transfers will extract the most value.
Unique Value Proposition
Paystand combines accounts automation with a payments network that eliminates bank transfer fees. That pairing targets the key pain point of B2B finance: manual reconciliation plus high transaction costs.
Real World Use Case
A manufacturing company integrates Paystand to automate invoicing and receive instant bank transfers. The finance team reduces manual posting, reconciles payments in real time, and improves cash flow visibility across multiple sites.
Pricing
Paystand uses subscription based pricing with no transaction fees on bank payments. Specific rates and plan details are available upon request from sales.
Website: https://paystand.com
Adyen
At a Glance
Adyen is a unified fintech platform built for global scale and compliance. It pairs enterprise grade reliability with embedded financial products to support payments, payouts, card issuing, and capital across multiple channels.
Adyen works best when you need a single partner for payments and financial services with strong uptime and international banking licenses backing its operations.
Core Features
Adyen provides a single platform for payments, data, and financial products, with built in optimizations for conversion and fraud reduction. The platform uses a single API that supports multiple payment methods and channels while centralizing control of settlements and payouts.
- One platform for payments, payouts, card issuing, and launching branded financial products.
- Built in optimizations aimed at conversion improvement and cost efficiency.
- Global acceptance across more than 150 currencies and 200 local payment methods.
Pros
- High platform uptime of 99.999% supports continuous commerce operations without frequent interruptions.
- International banking licenses deliver regulatory trust and compliance for cross border financial flows.
- Global scale with support for over 150 currencies and 200 local payment methods helps expand into new markets.
- Trusted by major brands which demonstrates suitability for enterprise and high volume use cases.
- Comprehensive capabilities that combine payments, payouts, card issuing, and capital in one stack.
Cons
- Complex pricing structure can make cost forecasting difficult for businesses with mixed payment methods and volumes.
- Integration effort required to access advanced features means implementation timelines can extend for full utilization.
- Limited fee transparency for specific services without direct contact increases procurement friction for some teams.
Who It’s For
Large enterprises and high growth businesses that need scalable and compliant payment infrastructure will find Adyen appropriate. Teams running global eCommerce platforms or subscription models that require consolidated reporting and embedded financial features will benefit most.
Unique Value Proposition
Adyen combines global payment acceptance with embedded financial products under one platform backed by international banking licenses. That combination provides centralized control of money movement and the ability to launch branded financial offerings while maintaining enterprise grade uptime.
Real World Use Case
Adobe used Adyen to maximize subscription revenue through a unified global payments platform. This highlights Adyen’s strength for subscription based models and large scale enterprise operations that need consistent cross border processing.
Pricing
Adyen charges a processing fee of $0.13 per transaction plus a payment method fee that varies by method for example 3.95% for most card payments or method specific rates. There are no setup or monthly fees and charges are applied per transaction.
Website: https://adyen.com
Payment Platforms Comparison
This table provides a detailed comparison of advanced payment platforms, summarizing their features, advantages, targeted users, and pricing information to help businesses make informed choices.
| Platform | Key Features | Advantages | Audience | Pricing |
|---|---|---|---|---|
| SensePass | Unified payment hub for POS and ERP systems, processor-agnostic | Broad payment method support, seamless POS integration, reduces hardware investment | Retail chains, omnichannel merchants | Custom, quote-based |
| Citcon | 100+ payment methods, rapid deployment | Single API integration, expands global coverage, consolidated operations | Medium to large enterprises | Custom, quote-based with potential high setup fees |
| KOMOJU | Supports 65+ payment methods, PCI DSS compliant | Flexible integration options, regional payment reach, high reliability | Retailers of all sizes | Transaction-based, quote required |
| Paystand | Blockchain-based platform, ERP integrations | Zero transaction fees, extensive automation, subscription pricing model | Mid-to-large enterprises using ERP systems | Subscription-based, quote required |
| Adyen | Single API for payments and financial services | Global acceptance, enterprise uptime, embedded financial products | Large-scale enterprises | $0.13/transaction + varying method-specific fees |
Select the platform that aligns best with your business needs by comparing their distinct offerings and cost structures.
Discover the Future of Omnichannel Payments with SensePass
The “Top 5 Best Omnichannel Payment Solutions 2026” article highlights a common challenge retailers face today: managing diverse payment methods across multiple sales channels while keeping the checkout process seamless and cost-efficient. Retailers want one platform that integrates well with their existing POS and ecommerce systems and supports popular digital wallets, BNPL options, crypto payments, and bank transfer solutions.
SensePass is designed exactly for this need. It connects effortlessly with major platforms such as NetSuite, SuiteCommerce, Oracle Xstore, Aptos, Shopify POS, BigCommerce, Storis, NCR, and Dynamics365. It supports a vast array of payment methods including PayPal, Venmo, Apple Pay, Klarna, Afterpay, BitPay, and Trustly. As a processor-agnostic platform, SensePass offers merchants the freedom to select from over 50 card processors to optimize costs and flexibility.
Take control of your payments ecosystem and streamline your omnichannel sales today.

Ready to simplify your payment solutions while boosting conversions? Visit SensePass now and experience the power of unified payments tailored specifically for modern retailers.
Frequently Asked Questions
What are the main features to look for in an omnichannel payment solution?
A good omnichannel payment solution should support a variety of payment methods, including digital wallets, card payments, and bank transfers, to accommodate diverse customer preferences. Ensure it offers seamless integration with your existing systems to streamline your operations and improve customer experience.
How can an omnichannel payment solution improve customer experience?
An omnichannel payment solution enhances customer experience by providing a consistent and smooth checkout process across all platforms, whether in-store or online. To implement this, choose a solution that enables fast and secure transactions, allowing customers to select their preferred payment method without delays.
What factors influence the cost of implementing an omnichannel payment solution?
The cost of implementing an omnichannel payment solution can be influenced by transaction volume, the types of payment methods supported, and integration complexity. Review your anticipated transaction levels and required features to obtain accurate cost estimates before making a decision.
How long does it typically take to implement an omnichannel payment solution?
Implementation timelines for omnichannel payment solutions can vary significantly, ranging from a few weeks to a few months based on the complexity of your operational needs. To expedite the process, work closely with your solution provider to ensure a smooth setup and training for your team within 30–60 days.
Can an omnichannel payment solution help reduce transaction fees?
Yes, many omnichannel payment solutions offer competitive transaction fees by consolidating payment processing across channels. Evaluate different providers to identify those that can lower your processing costs by approximately 15-20% as you streamline your payment workflows.
Recommended
- Payment Gateway Selection Tips for Retail Success – Omnichannel payments at the Point Of Sale | Sensepass
- Payment Gateway Selection Tips for Retail Success – Omnichannel payments at the Point Of Sale | Sensepass
- 7 Essential Types of Digital Payments for Modern Retailers – Omnichannel payments at the Point Of Sale | Sensepass
- Master Payment Processing Best Practices for Your Business – Omnichannel payments at the Point Of Sale | Sensepass

 New York Office
260 Madison Ave Suite 8018 New York NY 10016

