
Step-by-step contactless payments guide for retail: 82% adoption
April 24, 2026
TL;DR:
- Contactless payments using NFC speed up transactions and enhance customer loyalty.
- Implementing secure, certified hardware and compliance ensures smooth contactless POS deployment.
- Ongoing staff training and monitoring optimize performance and security in omnichannel retail.
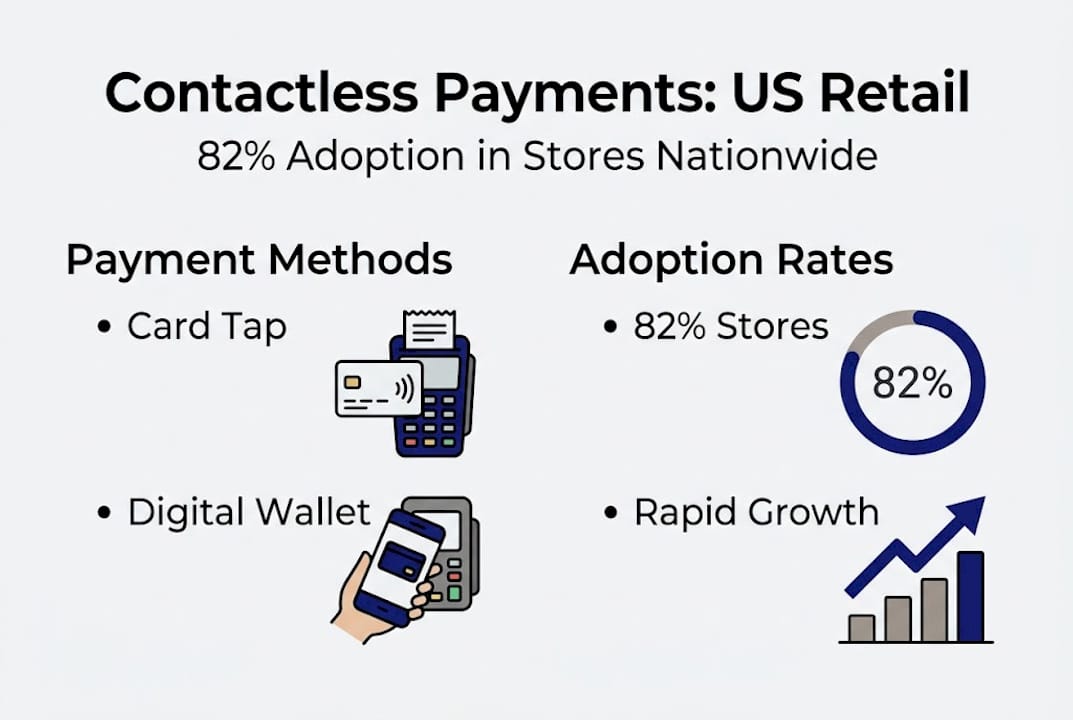
Contactless payments aren’t just a convenience upgrade — they’re a measurable driver of revenue and loyalty. 82% of US consumers now use contactless payments weekly, and retailers who move fast gain shorter queues, higher repeat purchase rates, and a checkout experience that feels effortless. The challenge isn’t whether to implement contactless — it’s how to do it securely, efficiently, and in a way that works across every sales channel you operate. This guide gives you a clear, step-by-step roadmap from technology basics through system selection, actual deployment, and ongoing optimization so you can launch with confidence.
Table of Contents
- Understanding contactless payment technologies
- Preparing for implementation: Choosing systems and meeting compliance
- Implementation steps for seamless omnichannel integration
- Troubleshooting and optimizing contactless payments
- A smarter, more secure path to contactless adoption
- Take the next step: Omnichannel payment solutions for retail
- Frequently asked questions
Key Takeaways
| Point | Details |
|---|---|
| Speed boosts sales | Faster checkout times increase customer retention and repeat purchases. |
| Security is layered | Tokenization, cryptograms, and biometrics significantly reduce fraud risks. |
| Compliance is mandatory | EMV and PCI DSS testing are essential for legal, reliable contactless deployment. |
| Troubleshooting is easy | Edge case failures can be fixed quickly with simple device and software adjustments. |
| Omnichannel unlocks value | Contactless payments enable seamless integration across in-store, online, and mobile channels. |
Understanding contactless payment technologies
Before you invest in hardware or reconfigure your checkout flow, it helps to understand exactly what’s happening during a contactless tap. The technology powering these transactions is called NFC, short for Near Field Communication. NFC allows two devices to exchange data wirelessly when they are within about four centimeters of each other. That close range is intentional — it keeps accidental reads from happening and limits exposure to interception.
When a customer taps their card, phone, or wearable at your terminal, the payment data transmitted isn’t their actual card number. Instead, the system uses tokenization for safety, replacing sensitive account details with a one-time token. This token is useless to anyone who intercepts it because it can’t be reused. The transaction also generates a dynamic cryptogram — essentially a unique digital signature — for each individual payment. So even if someone captured the data from one transaction, it couldn’t be replayed.
Here’s how the payment flow works step by step:
- Customer holds their NFC-enabled device within range of the terminal
- The terminal reads the encrypted token and sends it to the payment network
- The network verifies the token and cryptogram in real time
- Authorization is returned in seconds, and the transaction completes
What devices support NFC payments? Cards with the contactless symbol, smartphones running Apple Pay or Google Pay, smartwatches, and even some fitness bands. The ecosystem is already in your customers’ pockets.
US preference snapshot:
| Payment method | US preference share |
|---|---|
| Contactless card tap | 36% |
| Digital wallet tap | 14% |
| Traditional card swipe/insert | 50% |
The data shows that contactless cards are favored over digital wallets in many US segments, but both are growing rapidly. Supporting both formats is the smart play. You can learn more about what is contactless payment and the underlying mechanics before moving to the implementation phase.
Preparing for implementation: Choosing systems and meeting compliance
Now that you understand the technology, the next task is selecting the right hardware and software while making sure you meet every regulatory requirement. Skipping this phase is where most retailers run into expensive problems later.
Choosing your POS hardware and payment gateway
Not every terminal on the market supports NFC. Look for terminals explicitly labeled as NFC-enabled or contactless-ready. If you’re considering a Tap-on-Phone solution — which turns a standard Android smartphone into a payment terminal — confirm it meets PCI MPoC (Mobile Payments on COTS) standards before purchasing. Your payment gateway must also support digital wallet processing and connect cleanly to your existing eCommerce or POS platform.
Compliance requirements you must meet
EMV L1/L2 testing validates both the physical communication layer and the payment application layer of your hardware. Both levels are required for certified terminals. Beyond EMV, you need to maintain PCI DSS (Payment Card Industry Data Security Standard) compliance, which governs how cardholder data is stored, processed, and transmitted across your network.
Prioritize EMVCo-certified devices whenever possible. Certification means the device has passed rigorous interoperability and security tests.
Device and compliance comparison:
| Device type | EMV certified | NFC support | PCI MPoC required |
|---|---|---|---|
| Dedicated NFC terminal | Yes | Yes | No |
| Tap-on-Phone (Android) | Varies | Yes | Yes |
| Traditional POS terminal | Yes | Sometimes | No |
Checklist: Confirming hardware and software compatibility
- Verify the terminal carries EMV L1 and L2 certification
- Confirm your payment gateway supports NFC and digital wallets
- Check PCI DSS compliance documentation from your processor
- If using Tap-on-Phone, obtain PCI MPoC certification from vendor
- Test terminal communication with your existing POS software
- Validate that your eCommerce integration handles tokenized transactions
Pro Tip: Once you go live, monitor approval rates daily for the first two weeks. A sudden drop often signals a misconfigured token or a compatibility issue with a specific card network — catching it early saves chargebacks and customer frustration.
Review the contactless payments guide for a broader look at compliance considerations, and explore retail payment methods to understand how contactless fits alongside your other accepted payment types.
Implementation steps for seamless omnichannel integration
With the right hardware selected and compliance confirmed, you’re ready to deploy. The goal at this stage is a consistent, frictionless experience whether a customer pays in-store, curbside, or online.
Step-by-step deployment:
- Install and configure your NFC terminals. Mount terminals at checkout counters at a comfortable tap height. Connect to your payment gateway and run a test authorization with a live card before opening to customers.
- Enable digital wallet support. Work with your gateway to activate Apple Pay, Google Pay, and other wallet options. Each wallet has its own registration process with the payment networks.
- Set up Tap-on-Phone if applicable. PCI MPoC guidelines allow smartphone-based terminals to operate without extra hardware, making them ideal for mobile staff or pop-up locations.
- Connect omnichannel touchpoints. Link your in-store terminal data, your online checkout, and any curbside or drive-through lanes to a single payment orchestration layer. This gives you unified reporting and a consistent customer experience.
- Train your staff. Walk every team member through the tap flow, how to assist customers who have trouble, and how to escalate terminal errors. Consistent staff behavior is what prevents abandoned transactions at the register.
Need a closer look at the setup process? The enable contactless payments resource walks through terminal activation in detail, and the payment integration guide covers gateway connection. For a full cross-channel workflow view, the retail payment workflow guide is worth reviewing.
Key touchpoints to activate for omnichannel coverage:
- In-store NFC terminal at every register
- Curbside pickup via Tap-on-Phone or QR-linked payment link
- Online checkout with saved digital wallet support
- Self-checkout kiosks with NFC reader integration
- Call center payments using tokenized card-on-file
Pro Tip: Run a test round on at least five different device types before launch — an older iPhone, an Android with a case, a smartwatch, a contactless card, and a newer flagship phone. Edge cases almost always surface during this step, not during live transactions.
Troubleshooting and optimizing contactless payments
After launch, your focus shifts from setup to stability. Most contactless failures are minor and fixable quickly — the key is knowing what to look for.
Common causes of contactless payment failures:
- Device misalignment at the terminal reader
- Metal phone cases blocking NFC signal
- Outdated payment app or terminal firmware
- NFC turned off in device settings
- Low battery on customer’s phone disabling payment apps
- Network connectivity issues between terminal and gateway
Device case interference and poor alignment account for a significant share of failed taps. Train your staff to recognize these symptoms and offer a simple verbal guide: remove the case, re-align the device, or switch to a physical card if needed.
Quick troubleshooting steps:
- Ask the customer to remove any metal or thick card case
- Confirm the terminal’s NFC light is active
- Re-align the device directly over the reader symbol
- Restart the payment app on the customer’s device
- Update terminal firmware if multiple failures occur at one register
- Check your network connection if errors persist across all terminals
Contactless payments also carry a hygiene benefit that became critical post-COVID and remains important to health-conscious customers: no physical card handling means fewer touchpoints, cleaner transactions, and faster service.
Beyond fixing failures, use operational data to improve performance over time. The contactless checkout implementation resource shows how to track these metrics effectively.
Operational metrics to monitor:
| Metric | Why it matters | Target benchmark |
|---|---|---|
| Average queue time | Reflects checkout speed improvement | Under 90 seconds |
| Transaction approval rate | Flags system or compliance issues | Above 98% |
| Customer retention rate | Measures experience satisfaction | 45% greater retention vs. non-contactless |
| Contactless adoption rate | Shows staff training effectiveness | Above 60% of transactions |
Review these metrics with your team weekly for the first month, then monthly once the system stabilizes. Periodic reviews catch fraud pattern shifts early and surface training gaps before they affect the customer experience.
A smarter, more secure path to contactless adoption
Here’s something most implementation guides won’t tell you: the biggest risks in contactless payment rollouts are behavioral, not technical. The NFC hardware works. The tokenization layer works. What fails is people: staff who don’t reinforce proper tap positioning, managers who delay firmware updates, and decision-makers who assume that because the system is live, security is handled.
Tokenization and short NFC range neutralize the most common skimming threats, but behavioral analytics and ongoing monitoring are what catch the advanced ones. The retailers who get this right treat security as an ongoing operational discipline, not a one-time setup task.
Combine tokenization with biometric wallet authentication (Face ID or fingerprint unlock on Apple Pay and Google Pay) to create a layered security posture that’s genuinely hard to compromise.
Pro Tip: Schedule a quarterly security review with your payment processor. Review declined transaction patterns, flagged authorizations, and any new fraud vectors specific to contactless. An hour per quarter is worth far more than a single breach response.
The retail payment security tips resource and the secure payments guide give you concrete frameworks for maintaining this discipline over time.
Take the next step: Omnichannel payment solutions for retail
You now have a complete framework for implementing, managing, and securing contactless payments in your retail operation. The next question is: which platform can bring all of this together?

SensePass is an omnichannel payment orchestration layer built for exactly this kind of setup. It integrates with major POS systems including NetSuite, SuiteCommerce, Oracle Xstore, Aptos, Shopify POS, BigCommerce, Storis, NCR, and Dynamics365. It supports digital wallets like PayPal, Venmo, Apple Pay, Google Pay, WeChat, Alipay, and Amazon Pay, plus BNPL options like Klarna, Afterpay, Sezzle, ZIP, and Splitit, financing through Affirm and WeGetFinancing, crypto via BitPay and Coinbase, and Pay by Bank through Trustly and LinkMoney. SensePass is also processor-agnostic with access to 50+ card processors. Explore omnichannel payments for retailers, review payment gateway tips, and browse top payment tips to accelerate your rollout.
Frequently asked questions
What hardware is required for contactless payments in retail?
You’ll need NFC-enabled POS terminals or Tap-on-Phone solutions that meet EMV L1/L2 compliance for secure transactions. Certified hardware eliminates most interoperability failures before they reach your customers.
How can retailers reduce security risks with contactless payments?
Implement tokenization, maintain current firmware, follow PCI DSS standards, and require biometric authentication for digital wallets. Tokenization and biometrics together form a strong layered defense against both physical and digital threats.
What are the most common reasons contactless payments fail?
Device case interference and poor alignment with the reader are the most frequent causes, followed by outdated software or NFC being disabled on the customer’s device.
How fast are contactless transactions compared to traditional card payments?
Contactless transactions complete in seconds compared to the 15 to 30 seconds typically required for chip insert or swipe payments, which meaningfully reduces average queue times.
Are contactless payments suitable for omnichannel retail setups?
Yes. Contactless supports omnichannel flows across in-store, curbside, mobile, and self-checkout environments, giving customers a consistent and convenient experience at every touchpoint.
Recommended
- How to enable contactless payments for retail success – Omnichannel payments at the Point Of Sale | Sensepass
- Contactless payment integration guide: seamless setup for retail – Omnichannel payments at the Point Of Sale | Sensepass
- How to implement contactless checkout: faster sales, happier guests – Omnichannel payments at the Point Of Sale | Sensepass
- Why Use Contactless Payments: Complete Guide for Retail – Omnichannel payments at the Point Of Sale | Sensepass
- Blog | Merchant Solutions Corp

 New York Office
260 Madison Ave Suite 8018 New York NY 10016

