
Credit Card Processing Business: Complete Guide
November 19, 2025
Nearly 90 percent of in-store transactions in the United States now involve credit or debit cards, transforming how retailers and customers interact every day. Behind every swipe or tap lies a maze of security checks, technology, and financial partnerships working together in real time. Understanding credit card processing is no longer just for banks or tech experts—business owners, entrepreneurs, and shoppers all benefit from knowing how these intricate systems keep payments safe and businesses running smoothly.
Table of Contents
- What Is a Credit Card Processing Business?
- Types of Credit Card Processors Explained
- How Credit Card Processing Works for Retailers
- Critical Costs, Fees, and Compliance Factors
- Omnichannel Payment Integration With SensePass
Key Takeaways
| Point | Details |
|---|---|
| Role of Credit Card Processors | Credit card processors act as intermediaries, managing transactions between merchants, customers, banks, and networks through a series of secure steps. |
| Types of Processors | Understanding the different types of processors (MSPs, ISOs, Payment Gateways) helps businesses choose the right solution for efficient transaction management. |
| Cost and Compliance | Merchants should be aware of various fees (interchange, assessment, processor markups) and ensure compliance with PCI DSS to protect customer data and avoid penalties. |
| Omnichannel Integration | Implementing omnichannel payment integration enhances customer experience across multiple sales platforms, allowing for diverse payment methods and streamlined transactions. |
What Is a Credit Card Processing Business?
A credit card processing business transforms the seemingly simple act of swiping a credit card into a complex technological and financial transaction. According to Association for Financial Professionals, credit card processing represents a series of secure steps that enable businesses to efficiently accept credit card payments, involving multiple parties and intricate technological pathways.
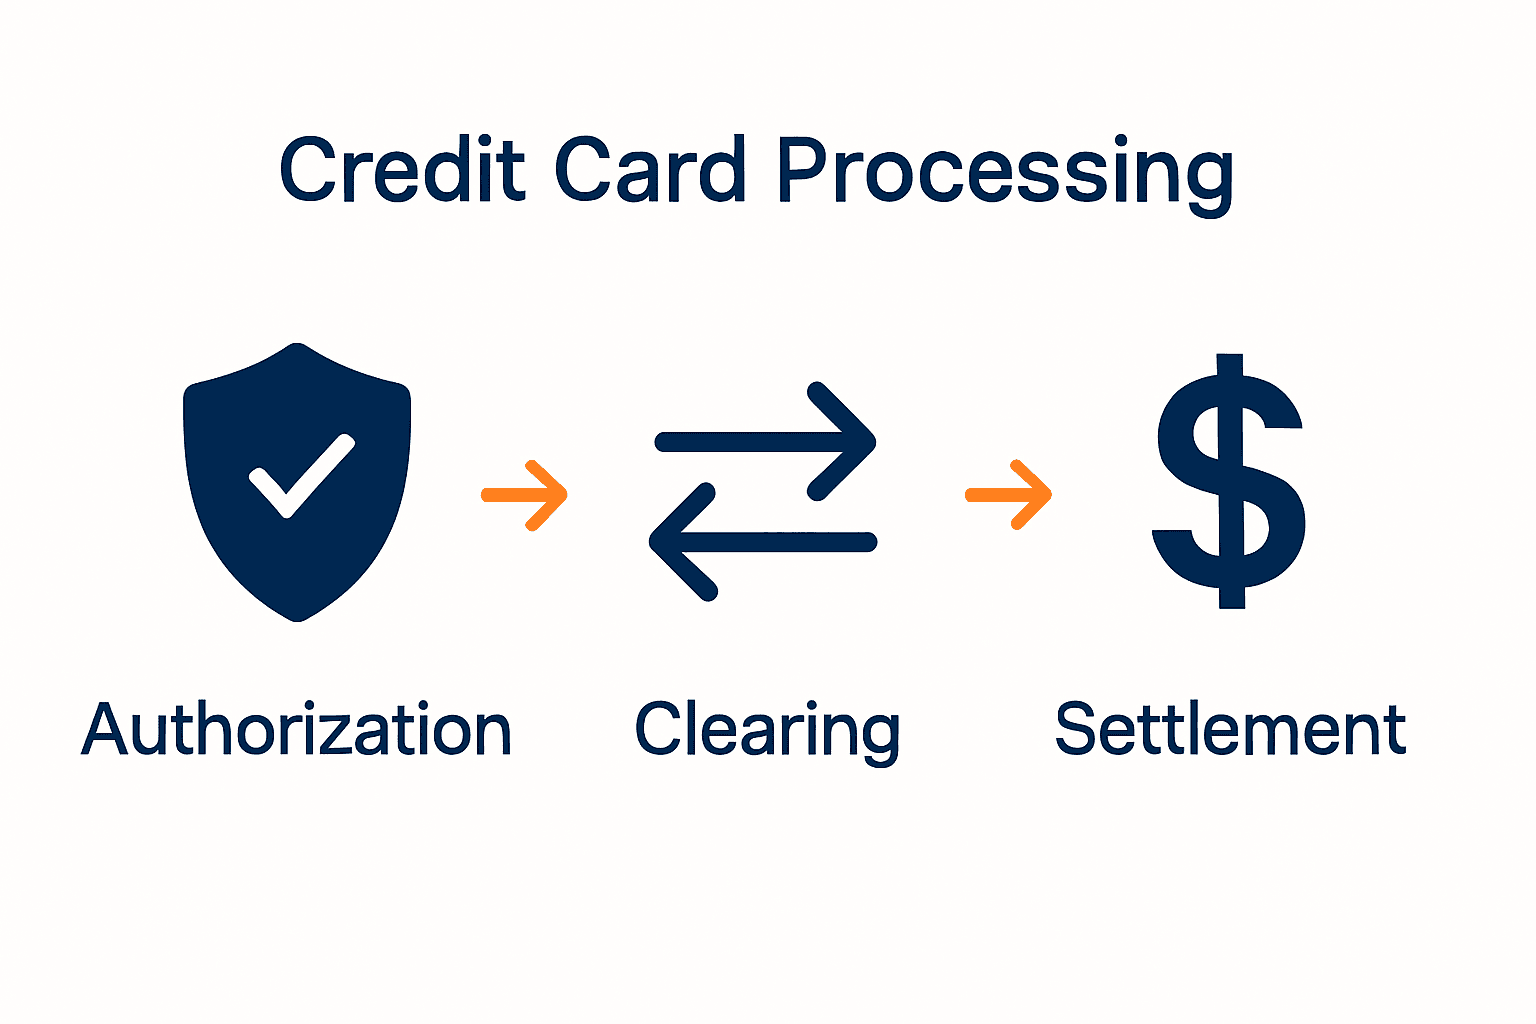
At its core, a credit card processing business serves as a critical intermediary between merchants, customers, financial institutions, and credit card networks. These businesses facilitate the seamless electronic transfer of payment information, ensuring merchants receive funds securely and quickly. The process involves three primary phases: authorization (verifying the card’s validity and available funds), clearing (transmitting transaction details), and settlement (transferring money between bank accounts).
The operational mechanics of a credit card processing business include several key components:
- Transaction routing through secure digital networks
- Fraud detection and prevention mechanisms
- Payment gateway integration for multiple sales channels
- Real-time verification of customer payment credentials
- Compliance with stringent financial security regulations
By partnering with payment gateway solutions like SensePass, businesses can leverage sophisticated processing infrastructure that supports multiple payment methods, reduces transaction costs, and enhances overall customer payment experiences across digital and physical platforms.
Types of Credit Card Processors Explained
Credit card processing involves multiple specialized entities working together to facilitate secure financial transactions. According to the Association for Financial Professionals, the key participants in this ecosystem include issuing banks, acquiring banks, payment processors, and card networks, each playing a critical role in transaction management.
Issuing Banks are financial institutions that provide credit cards to consumers, extending lines of credit and managing cardholder accounts. These banks take on the financial risk by lending money and are responsible for billing and collecting payments from cardholders. Acquiring Banks, in contrast, maintain merchant accounts and provide the infrastructure that allows businesses to accept credit card payments.
The different types of credit card processors can be categorized based on their specific functions:
- Merchant Service Providers (MSPs): Handle transaction processing for small to medium businesses
- Independent Sales Organizations (ISOs): Act as intermediaries between merchants and acquiring banks
- Payment Gateways: Facilitate online transaction processing and secure data transmission
- Aggregate Processors: Process transactions for multiple merchants under a single merchant account
By understanding these nuanced differences between payment processors, businesses can select the most appropriate solution for their specific payment processing needs, ensuring efficient, secure, and cost-effective transaction management across various sales channels.
How Credit Card Processing Works for Retailers
Retail credit card processing is a sophisticated digital dance of financial information and secure transactions. According to the Association for Financial Professionals, retailers initiate credit card transactions by submitting authorization requests through point-of-sale terminals or payment gateways, which then route through complex card networks to verify and approve purchases.
The transaction journey involves three critical stages: authorization, clearing, and settlement. During authorization, the payment system checks the card’s validity, available credit, and potential fraud risks in real-time. The clearing phase involves transmitting transaction details between the merchant’s bank and the customer’s issuing bank, reconciling the financial information. Settlement is the final stage where actual funds are transferred from the customer’s account to the merchant’s account.
Key steps in the credit card processing workflow include:
- Transaction Initiation: Customer presents credit card at point of sale
- Authorization Request: POS system sends transaction details to payment processor
- Bank Verification: Issuing bank confirms card validity and available funds
- Transaction Approval: Processor sends approval or denial back to merchant
- Fund Transfer: Approved transaction results in money movement between banks
Businesses can streamline this complex process by implementing comprehensive retail payment workflow solutions that integrate seamlessly across multiple sales channels, ensuring quick, secure, and efficient transaction processing for both merchants and customers.
Critical Costs, Fees, and Compliance Factors
Navigating the financial landscape of credit card processing requires a deep understanding of the complex fee structures and regulatory requirements. According to Business.org, merchants face a multifaceted cost environment involving multiple fee types, including interchange fees, assessment fees, and processor markups.
The primary cost components in credit card processing can be broken down into several critical categories:
- Interchange Fees: Percentage-based charges set by card networks
- Assessment Fees: Fixed costs charged by card brands like Visa and Mastercard
- Processor Markup: Additional fees imposed by payment processing companies
- Transaction Fees: Per-transaction charges that vary by card type and transaction method
- Monthly Service Fees: Recurring charges for maintaining payment infrastructure
Compliance represents another crucial aspect of credit card processing. As the Association for Financial Professionals emphasizes, merchants must strictly adhere to Payment Card Industry Data Security Standard (PCI DSS) to protect cardholder data and maintain secure payment environments. Non-compliance can result in significant financial penalties, increased transaction costs, and potential legal vulnerabilities.
Businesses can optimize their payment processing expenses by implementing strategic approaches to reduce credit card processing fees, carefully analyzing their transaction volumes, negotiating rates, and selecting processors that offer transparent pricing models tailored to their specific business needs.
Omnichannel Payment Integration With SensePass
In today’s rapidly evolving retail landscape, omnichannel payment integration has become a critical strategy for businesses seeking seamless customer experiences across multiple sales channels. SensePass provides a comprehensive payment orchestration layer that enables retailers to accept a diverse range of payment methods consistently across in-store, online, mobile, and call center platforms.
SensePass supports integration with a wide array of platforms and payment ecosystems, including:
- POS Systems: NetSuite, SuiteCommerce, Oracle Xstore, Aptos, Shopify POS
- eCommerce Platforms: BigCommerce, Storis, WooCommerce
- Retail Management Systems: NCR, Dynamics 365
The platform’s robust integration capabilities extend to supporting multiple payment methods, ensuring maximum flexibility for merchants:
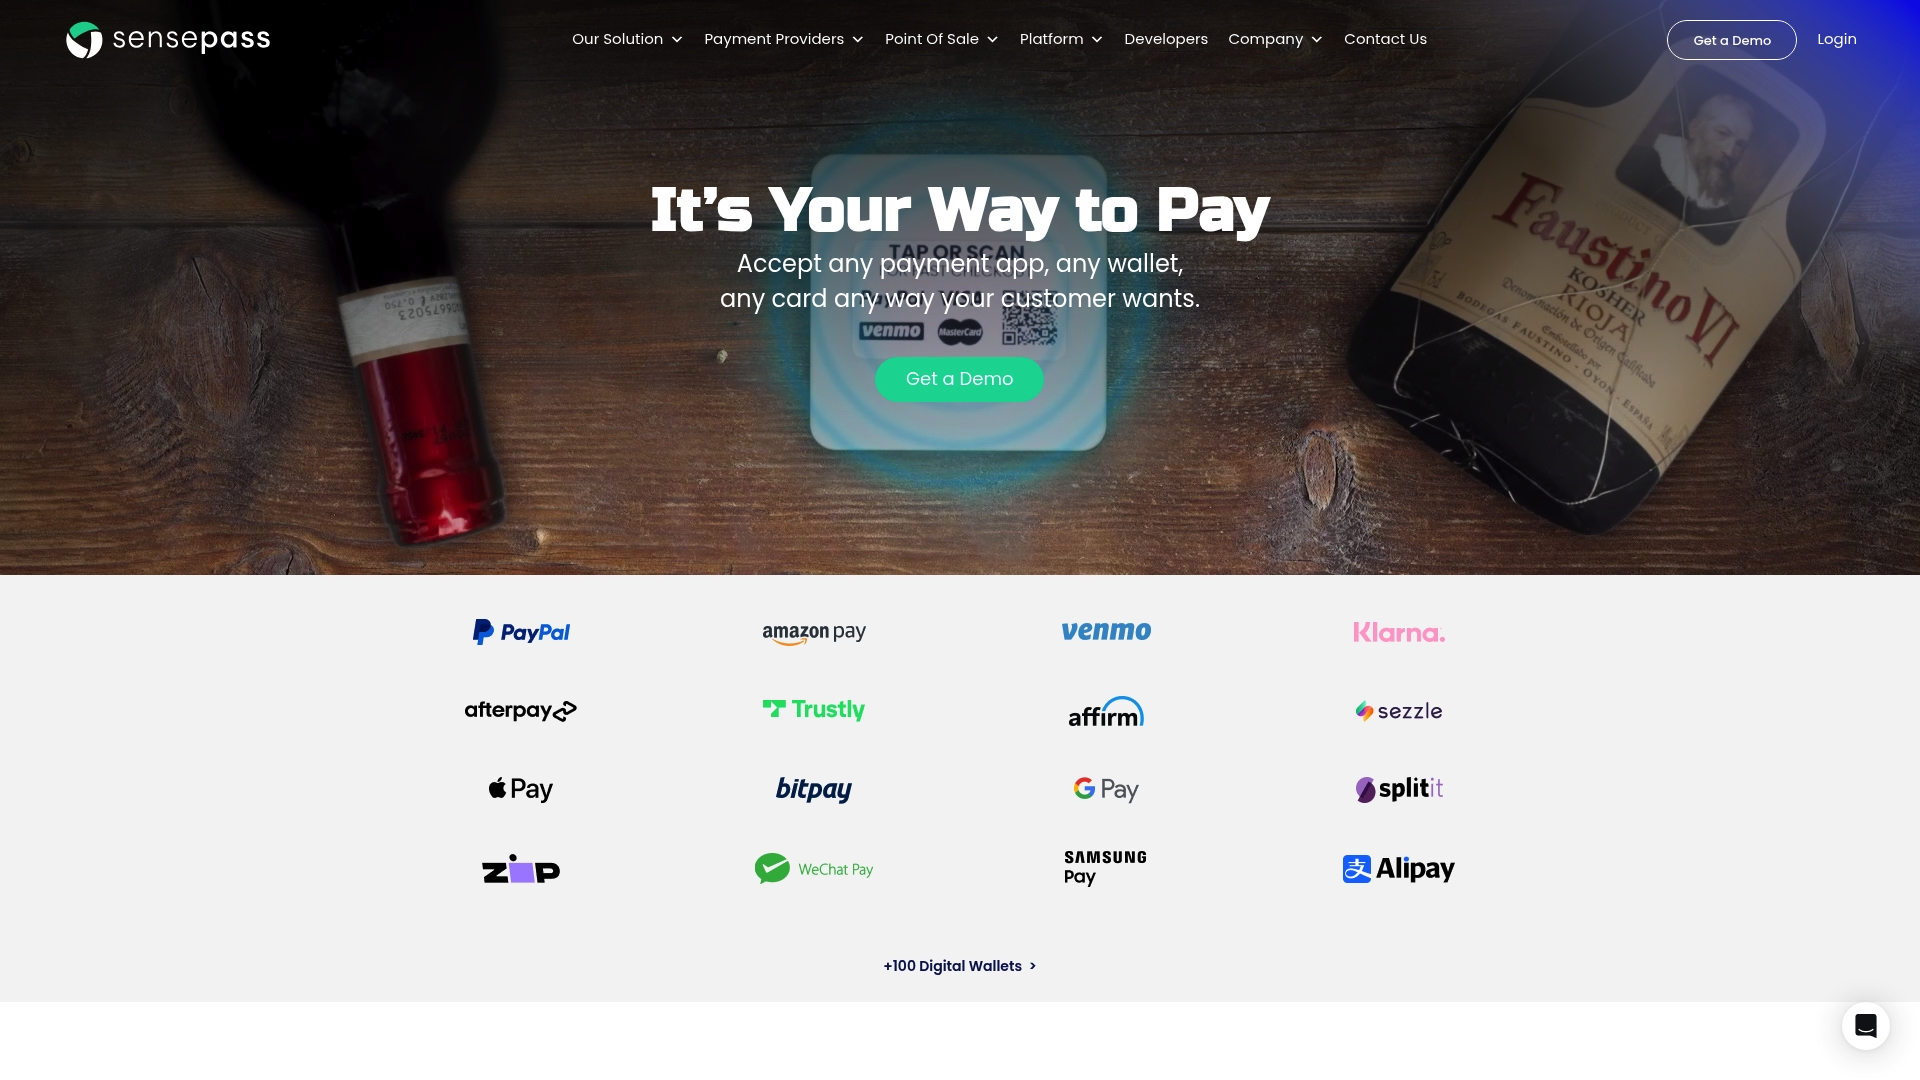
- Digital Wallets: Apple Pay, Google Pay, PayPal, Venmo
- BNPL Services: Klarna, Sezzle, Afterpay
- Crypto Payments: BitPay, Coinbase
- Financing Options: Affirm, WeGetFinancing
By navigating the complexities of omnichannel retail payments, businesses can leverage SensePass’s processor-agnostic approach to choose from 50+ card processors, reduce transaction costs, and create a unified, frictionless payment experience that meets modern consumer expectations across all sales channels.
Simplify Your Credit Card Processing with SensePass
Navigating the complexities of credit card processing can feel overwhelming. From managing authorization, clearing, and settlement phases to juggling various fees and compliance requirements, businesses need a seamless solution that keeps pace with today’s omnichannel retail environment. SensePass directly addresses these challenges by providing a robust, processor-agnostic payment orchestration layer tailored for retailers seeking to streamline payments across multiple channels.
With proven integration capabilities supporting leading platforms such as NetSuite, SuiteCommerce, Oracle Xstore, Aptos, Shopify POS, BigCommerce, Storis, NCR, and Dynamics365, SensePass ensures flawless operation whether you sell in-store, online, or via call centers. The platform supports a wide range of payment methods including digital wallets like PayPal and Apple Pay, BNPL services like Klarna, crypto payments via BitPay, and traditional card processors — offering you unmatched flexibility and control.
Take control of your payment processing today with SensePass and transform how your business accepts payments.
Ready to reduce costs, boost sales conversion rates, and deliver a smooth, secure payment experience? Visit SensePass now to explore how our omnichannel payment solutions can elevate your business.
Frequently Asked Questions
What is a credit card processing business?
A credit card processing business serves as an intermediary that enables merchants to accept credit card payments by handling the secure transfer of payment information between customers, financial institutions, and card networks.
How does credit card processing work for retailers?
Credit card processing for retailers involves three key stages: authorization (verifying the card’s validity and available funds), clearing (transmitting transaction details), and settlement (transferring money between the customer’s and merchant’s accounts).
What are the types of credit card processors?
The types of credit card processors include Merchant Service Providers (MSPs), Independent Sales Organizations (ISOs), Payment Gateways, and Aggregate Processors, each serving different functions in transaction processing.
What are the main costs associated with credit card processing?
The main costs of credit card processing include interchange fees, assessment fees, processor markups, transaction fees, and monthly service fees, which can vary depending on the payment processor and transaction type.
Recommended

 New York Office
260 Madison Ave Suite 8018 New York NY 10016

