
Dynamic Payment Method Strategy for Retail in 2026
June 25, 2026
TL;DR:
- Dynamic payment strategies route payment options in real time using signals like device type and gateway health. They significantly reduce checkout abandonment and improve transaction success rates by personalizing method ranking and routing. Implementing such systems requires an orchestration layer, real-time data capture, and careful monitoring to avoid reconciliation issues.
A dynamic payment method strategy is defined as a real-time system that selects, ranks, and routes payment options at the moment of checkout based on live signals like device type, purchase history, and gateway health. The industry term for this practice is intelligent payment routing, and it sits at the core of modern omnichannel retail. AI-powered adaptive payment flows reduce checkout abandonment by 84% and increase completed transactions by 67% during peak periods. Those numbers reflect a structural shift, not a marginal improvement. Platforms like Sensepass and tools like Stripe Adaptive Checkout have made this approach accessible to mid-market retailers, not just enterprise operations. If you run a multichannel retail business, this strategy directly affects your conversion rate, processing costs, and customer satisfaction.
What are the key components of a dynamic payment method strategy?
A dynamic payment method strategy requires three foundational layers: a payment orchestration layer, real-time data capture, and an adaptive checkout interface. Without all three, you get partial results at best.
The orchestration layer sits between your storefront and your payment processors. It receives transaction requests, evaluates live signals, and routes each payment to the most appropriate processor or method. Sensepass operates as exactly this kind of orchestration layer, connecting retailers to 50+ card processors while remaining processor-agnostic. That flexibility means you are never locked into a single processor’s success rates or pricing.
Real-time data capture feeds the routing logic. The signals that matter most include:
- Device type (mobile, desktop, in-store terminal)
- Customer location and regional payment preferences
- Purchase history and prior payment method behavior
- Gateway health at the moment of the transaction
- Cart value and product category
The adaptive checkout interface is what the customer actually sees. Configuring payment methods from a dashboard without custom code is now standard practice. This means your team can add or reorder payment options, including BNPL providers like Klarna or Afterpay, without a developer sprint.
Pro Tip: Before deploying any routing logic, audit your current payment method mix. Retailers who map their top five payment methods by channel and cart value find the clearest starting point for routing rules.
How does real-time adaptive payment ranking and routing work?
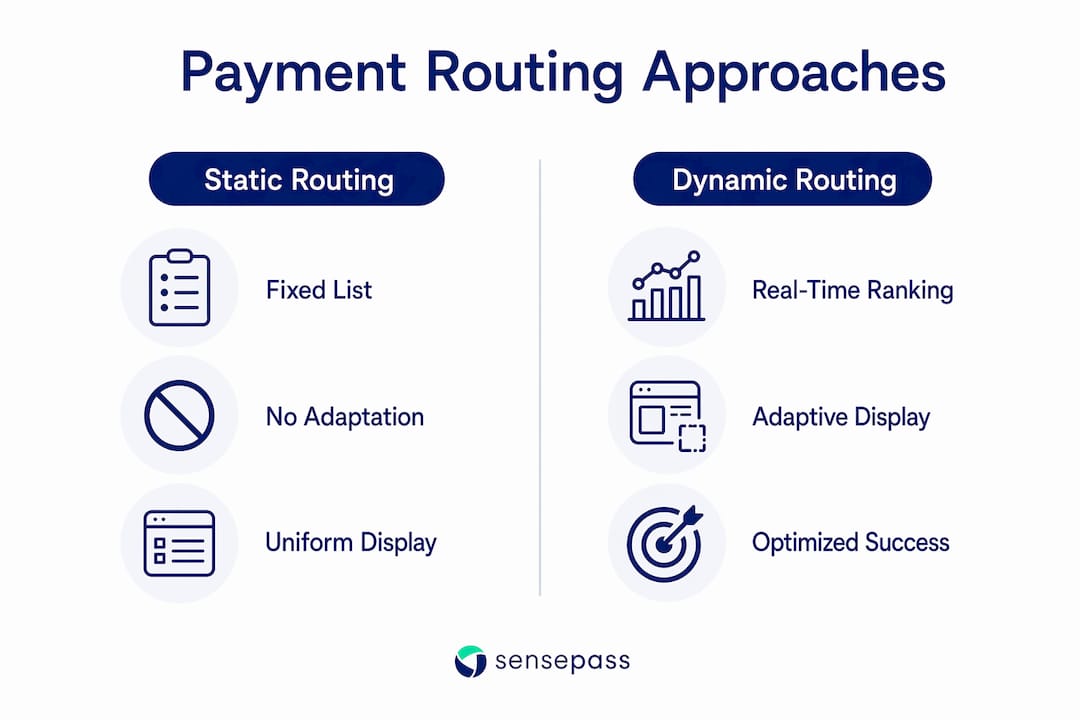
Adaptive payment ranking replaces the static payment menu with a probabilistic system. Instead of showing every customer the same list, the checkout engine scores each available payment method by its likelihood of completing the transaction successfully for that specific customer in that specific context.
The process follows a clear sequence:
- Signal collection. At checkout initiation, the system captures device type, browser, location, session behavior, and any available customer history.
- Method scoring. A probabilistic model assigns a conversion likelihood score to each available payment method based on the collected signals.
- Ranked display. The checkout interface surfaces the highest-scoring methods first. Dynamic wallet ordering based on device and purchase history replaces the fixed list.
- Transaction routing. The selected method routes to the optimal processor based on real-time gateway health and cost parameters.
- Fallback and retry. If a transaction fails, the system executes a controlled retry on an alternate gateway or method without customer-facing confusion.
- State confirmation. Before any retry, the system confirms the prior transaction state to prevent duplicate charges.
Intelligent payment routing uses device type, payment history, and gateway health to improve success rates and reduce reconciliation complexity. That last point matters more than most retailers realize. Every ambiguous transaction state creates a reconciliation problem for your finance team.
The most dangerous failure mode in routing is ambiguous state awareness. This happens when a system retries or switches gateways without confirming whether the previous attempt succeeded or failed. Orchestration layers like Sensepass enforce explicit transaction state tracking to prevent this. The result is cleaner books and fewer customer disputes.
Over-routing by adding many gateways without intelligent logic increases reconciliation challenges without improving success rates. More gateways without smarter decision logic just creates more noise.
Static vs. dynamic payment routing: which approach wins?
The difference between static and dynamic payment approaches is not subtle. Static systems present the same payment options in the same order to every customer. Dynamic systems personalize both the display and the routing in real time.
| Feature | Static approach | Dynamic approach |
|---|---|---|
| Payment method display | Fixed list, same for all customers | Ranked by conversion likelihood per customer |
| Gateway selection | Manual or preset | Algorithmic, based on live signals |
| Failed transaction handling | Manual retry or customer re-entry | Automated fallback with state confirmation |
| Reconciliation complexity | High, especially with multiple processors | Lower, with explicit state tracking |
| BNPL visibility | Fixed position, often negotiated | Algorithm-driven, based on customer fit |
| Setup flexibility | Requires developer changes | Dashboard-configurable in modern platforms |
The conversion impact of switching from static to dynamic is measurable. Adaptive payment flows produce an 84% reduction in abandonment. Static menus cannot compete with that because they ignore the context that determines whether a customer completes a purchase.
Best payment method practices for retailers moving away from static systems:
- Prioritize methods with the highest historical completion rates for your customer segments.
- Use BNPL options like Klarna, Sezzle, Splitit, and Afterpay as dynamic additions, not fixed placements. Splitit’s card-linked installments work across online, in-store, and phone channels without new credit checks.
- Treat payment method visibility as a conversion variable, not a design decision.
How to deploy a dynamic payment strategy across multiple channels
Deploying adaptive payment strategies across POS, eCommerce, and call center channels requires a structured rollout. Rushing the implementation creates the exact reconciliation problems you are trying to avoid.
Phase 1: Infrastructure audit
Confirm that your current stack supports the following:
- A payment orchestration layer or gateway that accepts real-time routing rules
- API connections to your POS systems, eCommerce platform, and any phone sales tools
- Data capture at the transaction level, including device type and customer identifier
Sensepass integrates with NetSuite, SuiteCommerce, Oracle Xstore, Aptos, Shopify POS, BigCommerce, Storis, NCR, and Dynamics365, among others. That breadth of POS system integration means you can apply consistent routing logic across every channel without rebuilding your stack.
Phase 2: Payment method configuration
Add your full method set to the orchestration layer. Sensepass supports digital wallets including PayPal, Venmo, WeChat, Apple Pay, Google Pay, Alipay, and Amazon Pay. It also supports BNPL through Klarna, Sezzle, ZIP, Splitit, and Afterpay, financing through WeGetFinancing and Affirm, crypto payments through BitPay and Coinbase, and pay-by-bank through Trustly and LinkMoney.
Phase 3: Routing rule configuration
Set initial routing rules based on your existing transaction data. Prioritize your top-performing processor for high-value transactions. Configure fallback processors for each primary route.
Phase 4: Monitoring and tuning
Track these metrics weekly after launch:
| Metric | What it tells you |
|---|---|
| Authorization rate by method | Which methods succeed most often |
| Abandonment rate by channel | Where friction still exists |
| Retry rate | Whether fallback logic is triggering correctly |
| Reconciliation exceptions | Whether state tracking is working |
Mid-market retailers gain measurable benefits from intelligent routing by avoiding duplicate attempts and simplifying reconciliation. You do not need enterprise scale to justify this investment.
Pro Tip: Run your dynamic routing in shadow mode for two weeks before going live. Shadow mode logs what the system would have routed without actually changing the transaction path. You catch configuration errors before they affect real customers.
Key Takeaways
A dynamic payment method strategy is the single most direct lever retailers have for improving checkout conversion and reducing payment processing costs across all channels.
| Point | Details |
|---|---|
| Define your signals first | Routing logic only works when you capture device type, location, and purchase history at the transaction level. |
| Avoid over-routing | Adding more gateways without decision logic increases reconciliation complexity without improving success rates. |
| State tracking prevents duplicates | Explicit transaction state confirmation before any retry is the difference between clean books and customer disputes. |
| Dynamic BNPL placement outperforms fixed | Algorithm-driven BNPL visibility converts better than negotiated fixed placements. |
| Phased rollout reduces risk | Shadow mode testing before go-live catches routing errors without affecting real transactions. |
What I’ve learned about routing logic that most guides get wrong
Vlad here. After working with retailers across POS and eCommerce environments, the pattern I see most often is this: merchants invest in adding more payment methods and more gateways, then wonder why their success rates do not improve. The problem is almost never the number of options. It is the absence of decision logic connecting them.
The retailers who see real gains from adaptive payment strategies are the ones who treat routing as a data problem first and a technology problem second. They start by understanding which payment methods actually complete for which customer segments, then build routing rules around that reality. The technology, whether it is Sensepass or another orchestration layer, just executes those rules at speed.
The other thing I would caution against is treating BNPL placement as a fixed contract. Adaptive payment displays make payment visibility algorithm-driven, which means a BNPL provider’s position at checkout depends on conversion signals, not a negotiated spot. That shift benefits the retailer and the customer. It does not always benefit the provider. Know which side of that equation you are on.
For mid-market retailers who think intelligent routing is out of reach, the evidence says otherwise. The infrastructure exists, the integrations are ready, and the retail payment optimization gains are real. The only thing standing between you and better conversion rates is the decision to start.
— Vlad
How Sensepass powers adaptive payment routing for retailers
Retailers who want to put a dynamic payment method strategy into practice need an orchestration layer that connects every channel, every method, and every processor in one place.

Sensepass is built for exactly that. It supports digital wallets like Apple Pay, Google Pay, PayPal, Venmo, WeChat, Alipay, and Amazon Pay alongside BNPL options including Klarna, Afterpay, Sezzle, ZIP, and Splitit. Financing through WeGetFinancing and Affirm, crypto payments through BitPay and Coinbase, and pay-by-bank through Trustly and LinkMoney round out the method set. Sensepass is processor-agnostic across 50+ card processors, and it integrates with NetSuite, Oracle Xstore, Aptos, Shopify POS, BigCommerce, NCR, Dynamics365, and more. For retailers ready to move from static checkout to real-time adaptive routing, the omnichannel payment guide is the right place to start.
FAQ
What is a dynamic payment method strategy?
A dynamic payment method strategy is a real-time system that selects and routes payment options at checkout based on live signals like device type, customer history, and gateway health. The goal is to maximize transaction success and reduce abandonment.
How does dynamic routing differ from static payment menus?
Static menus show every customer the same payment options in the same order. Dynamic routing ranks and displays methods based on conversion likelihood for each specific transaction, producing measurably higher completion rates.
What signals drive adaptive payment method ranking?
The primary signals are device type, customer purchase history, geographic location, cart value, and real-time gateway health. These inputs feed a probabilistic model that scores each available payment method before displaying it.
Is intelligent payment routing only for large enterprises?
Mid-market retailers benefit from intelligent routing by avoiding duplicate charges and simplifying reconciliation. The technology is accessible through orchestration platforms that integrate with standard POS and eCommerce systems.
What is the biggest risk when implementing payment routing?
Ambiguous transaction state awareness is the most common failure point. When a system retries a payment without confirming whether the previous attempt succeeded, it creates duplicate charges and reconciliation errors. Explicit state tracking before every retry prevents this.
Recommended
- 7 Types of Retail Payment Methods for Your Business – Omnichannel payments at the Point Of Sale | Sensepass
- Mobile Payment Trends 2026: What Retailers Must Know – Omnichannel payments at the Point Of Sale | Sensepass
- Mobile Payment Trends 2025: What Retailers Must Know – Omnichannel payments at the Point Of Sale | Sensepass
- Retail Payment Ecosystem Guide: Complete Overview – Omnichannel payments at the Point Of Sale | Sensepass

 New York Office
260 Madison Ave Suite 8018 New York NY 10016

