
Guidelines for Crypto Payments: A Business Compliance Guide
July 14, 2026
TL;DR:
- Businesses must follow regulatory guidelines to accept crypto payments securely and avoid costly compliance errors. They need meticulous record-keeping, proper integration, and adherence to tax and AML rules to ensure legal and financial accuracy. Starting with a phased approach helps validate processes and minimizes operational risks.
Guidelines for crypto payments are structured best practices that businesses must follow to accept cryptocurrency securely, compliantly, and with accurate financial records. The IRS treats cryptocurrency as property, not currency, which means every transaction creates a taxable event requiring documentation. Regulatory bodies including the IRS, FinCEN, and state-level money services business (MSB) licensing authorities each impose distinct obligations on merchants. Getting these fundamentals right from the start protects your business from tax notices, licensing violations, and operational failures that are far more costly to fix after the fact.
What are the core compliance and legal requirements for accepting crypto?
The IRS classifies cryptocurrency as property, so every crypto payment counts as ordinary income at the USD fair market value on the date of receipt. That means you record income the moment a customer pays, not when you convert the crypto to dollars. Any later conversion, swap, or disposal of that crypto creates a second taxable event for capital gains or losses.
Most businesses that simply accept crypto as payment do not qualify as money transmitters. However, MSB registration is required if your business exchanges crypto for cash or holds customer funds. FinCEN registration uses RMSB Form 107 with biennial renewals, and state licensing requirements vary significantly by jurisdiction.
AML and KYC obligations depend on your specific business model and the volume of transactions you process. The threshold that triggers additional federal reporting is clear:
- Large transaction reporting: Transactions over $10,000 require filing IRS Form 8300, matching the same rules applied to cash transactions.
- AML protocols: Businesses with higher transaction volumes or customer fund exposure must implement formal anti-money laundering programs.
- KYC screening: Customer identity verification and sanctions screening are required when your risk profile or transaction volume demands it.
- State licensing: Some states require separate money transmitter licenses even when FinCEN registration is not triggered.
The practical takeaway is that most retailers accepting crypto directly at checkout face IRS income reporting as their primary obligation. MSB and AML requirements become relevant when your model moves closer to exchange or custodial services.
How do you technically integrate crypto payments into existing systems?
Technical integration follows a defined sequence. Skipping steps or cutting corners in the architecture creates fulfillment errors and security vulnerabilities that are difficult to trace after the fact.
- Select and onboard a crypto payment gateway. Choose a gateway that supports the specific assets and blockchain networks your customers use. Confirm it provides webhook notifications, a sandbox environment, and clear API documentation before committing.
- Define your asset and network scope. Accepting Bitcoin on the wrong network or failing to specify the correct chain causes lost payments. Lock down which assets and networks you support before going live.
- Build your invoice and monitoring workflow. Generate a unique payment address per invoice, set an expiration window, and monitor the blockchain for incoming transactions. Never reuse addresses across invoices.
- Design a state machine for payment status. Reliable crypto integration treats “pending” as the primary state and handles all transitions: pending, confirmed, underpaid, overpaid, and expired. Fulfillment should only trigger on confirmed status.
- Implement idempotent webhook handlers. Webhook handlers must be idempotent because gateways retry failed notifications. Your code must process duplicate events without double-fulfilling orders or creating reconciliation errors.
- Verify all webhook signatures. Webhook payloads must be cryptographically verified using shared secrets or asymmetric keys provided by the gateway. Never trust payment completion signals that arrive without a valid signature.
Pro Tip: Never rely on frontend confirmation to trigger order fulfillment. A customer’s browser can be manipulated. Only backend webhook verification from a cryptographically signed payload should release an order.
For retailers evaluating gateway options, payment gateway selection tips cover the security and compliance criteria that apply directly to crypto integrations. The role of payment gateways in retail also explains how crypto fits within a broader payment architecture.
What are the accounting and tax reporting rules for crypto payments?
Tax compliance is the most common failure point for merchants accepting cryptocurrency. Meticulous record keeping paired with cost-basis accounting is the only way to avoid IRS CP2000 notices, which typically arrive 12–18 months after the filing year.
Every crypto payment requires a complete record at the time of receipt:
- Timestamp: The exact date and time of the transaction, pulled from the block.
- Crypto type and amount: The specific asset and quantity received.
- USD fair market value: The price at the moment of receipt, not at conversion.
- Transaction hash: The on-chain identifier for audit purposes.
Cost-basis tracking must be wallet-specific and independently calculated. Do not rely on exchange-provided cost basis figures. Exchanges may report zero-cost basis or incomplete data, which causes incorrect capital gains calculations and triggers IRS notices. You must calculate fair market value at receipt using block timestamps and exchange price data.
Your business must elect and consistently apply an accounting method: FIFO (first in, first out), LIFO (last in, first out), or specific identification. Each method produces different tax outcomes. Specific identification gives you the most control but requires the most detailed records.
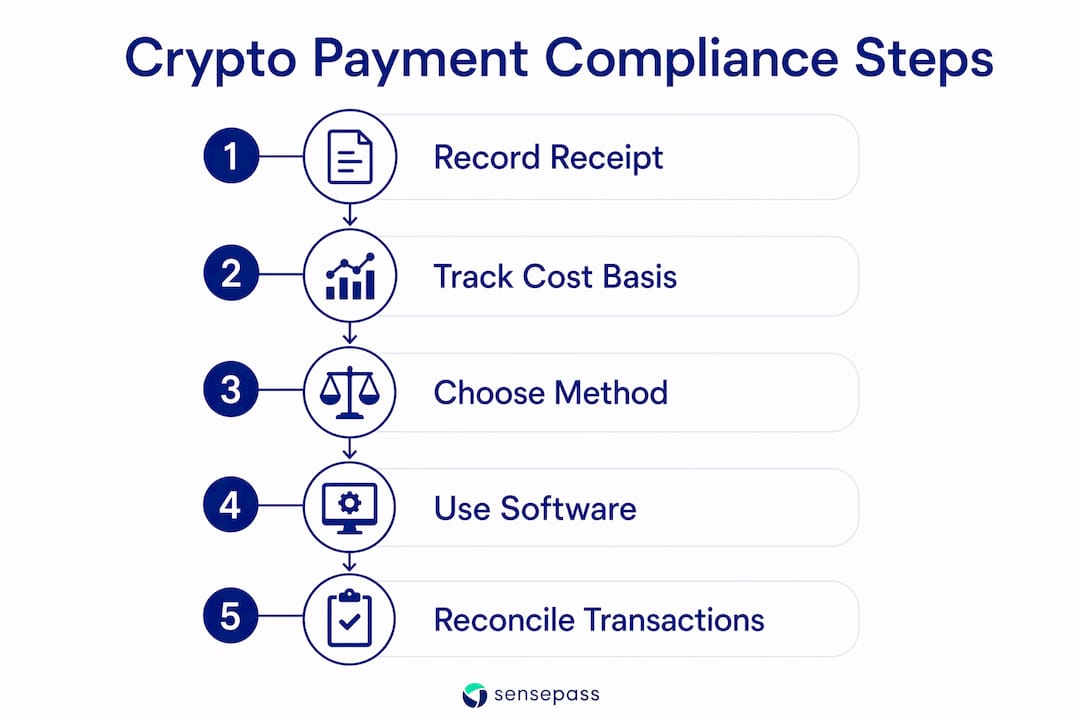
Pro Tip: Use dedicated crypto tax software that integrates with your accounting platform. Manually reconciling hundreds of transactions per month is error-prone and time-consuming. Automation reduces both risk and labor.
| Record element | Why it matters |
|---|---|
| Block timestamp | Establishes the exact fair market value at receipt |
| USD fair market value | Determines ordinary income amount reported to IRS |
| Transaction hash | Provides audit trail for each taxable event |
| Cost basis per wallet | Required for accurate capital gains calculation |
| Accounting method election | Must be consistent across all periods |
Common mistakes include mixing personal and business wallets, ignoring gas fees as deductible expenses, and failing to record conversion events as separate taxable disposals.
What operational best practices reduce risk in crypto payment acceptance?
A phased rollout starting with limited assets, one gateway, and a single settlement policy is the most effective way to validate your integration before scaling. This approach lets you test the full invoice-to-reconciliation flow under controlled conditions and catch errors before they affect large transaction volumes.
Your treasury policy needs to be defined before you go live. Decide whether you will hold crypto on your balance sheet or convert to fiat immediately upon receipt. Immediate conversion eliminates volatility risk and simplifies accounting. Holding crypto introduces price exposure and requires more complex cost-basis tracking.
Operational monitoring should track four metrics from day one: adoption rate, refund rate, support case volume related to crypto payments, and reconciliation success rate. These metrics tell you whether your integration is working and where friction exists for customers.
Exception handling policies must be written and communicated to your support team before launch. Predefined rules for underpayments, overpayments, and expired invoices reduce customer disputes and prevent ad hoc decisions that create inconsistent outcomes. Refund policies for crypto payments are particularly complex because the asset’s value may have changed between purchase and refund.
Pro Tip: Run a full reconciliation test with your accounting team before launch. Process a small number of real transactions end-to-end and confirm that every record appears correctly in your ledger, tax software, and bank statement.
Continuous KYC, AML, and sanctions screening must be built into your ongoing operations, not treated as a one-time setup task. Regulatory requirements evolve, and your compliance posture needs to keep pace.
Key Takeaways
Businesses that follow structured crypto payment guidelines from the start avoid the compliance failures, tax penalties, and operational errors that derail late-stage corrections.
| Point | Details |
|---|---|
| IRS property classification | Record every crypto payment as ordinary income at USD fair market value on the date of receipt. |
| MSB and AML thresholds | Transactions over $10,000 require IRS Form 8300; MSB registration applies only when exchanging or holding customer funds. |
| Idempotent webhook handling | Build backend handlers that process duplicate gateway notifications without double-fulfilling orders. |
| Wallet-specific cost basis | Calculate cost basis independently per wallet using block timestamps, not exchange-provided figures. |
| Phased rollout first | Start with one asset, one gateway, and one settlement policy before expanding to additional currencies or channels. |
Why crypto payment compliance is harder than it looks
I’ve watched businesses treat crypto payment integration as a checkout feature rather than a financial infrastructure decision. That framing is where most problems start.
The technical side, the API calls, the webhook handlers, the state machines, gets the most attention from engineering teams. But the accounting and compliance layer is where real risk lives. A missed cost-basis record or a misclassified conversion event doesn’t surface until the IRS sends a CP2000 notice more than a year later. By then, the transaction volume is large, the records are incomplete, and the correction is expensive.
The businesses that get this right treat crypto acceptance as a cross-functional project from day one. Finance, engineering, and legal all need to be in the room before the first transaction processes. Finance defines the accounting method and treasury policy. Engineering builds the state machine and webhook verification. Legal confirms licensing obligations and AML thresholds.
I’ve also seen businesses adopt crypto payments because it sounds forward-thinking, without a clear answer to the question of what business outcome they are measuring. Adoption rate, average order value from crypto customers, and reconciliation accuracy are the metrics that tell you whether the investment is working. Novelty is not a metric.
The crypto payment gateway market is maturing quickly, which means infrastructure options are better than they were two years ago. That makes the technical side easier. It does not make the compliance side easier. The regulatory environment is still evolving, and the businesses that build disciplined processes now will have a significant advantage when reporting requirements tighten further.
— Vlad
How Sensepass fits into your crypto payment infrastructure
Sensepass is an omnichannel payment orchestration layer built for retailers that need to support multiple payment methods across every channel without rebuilding their existing infrastructure.
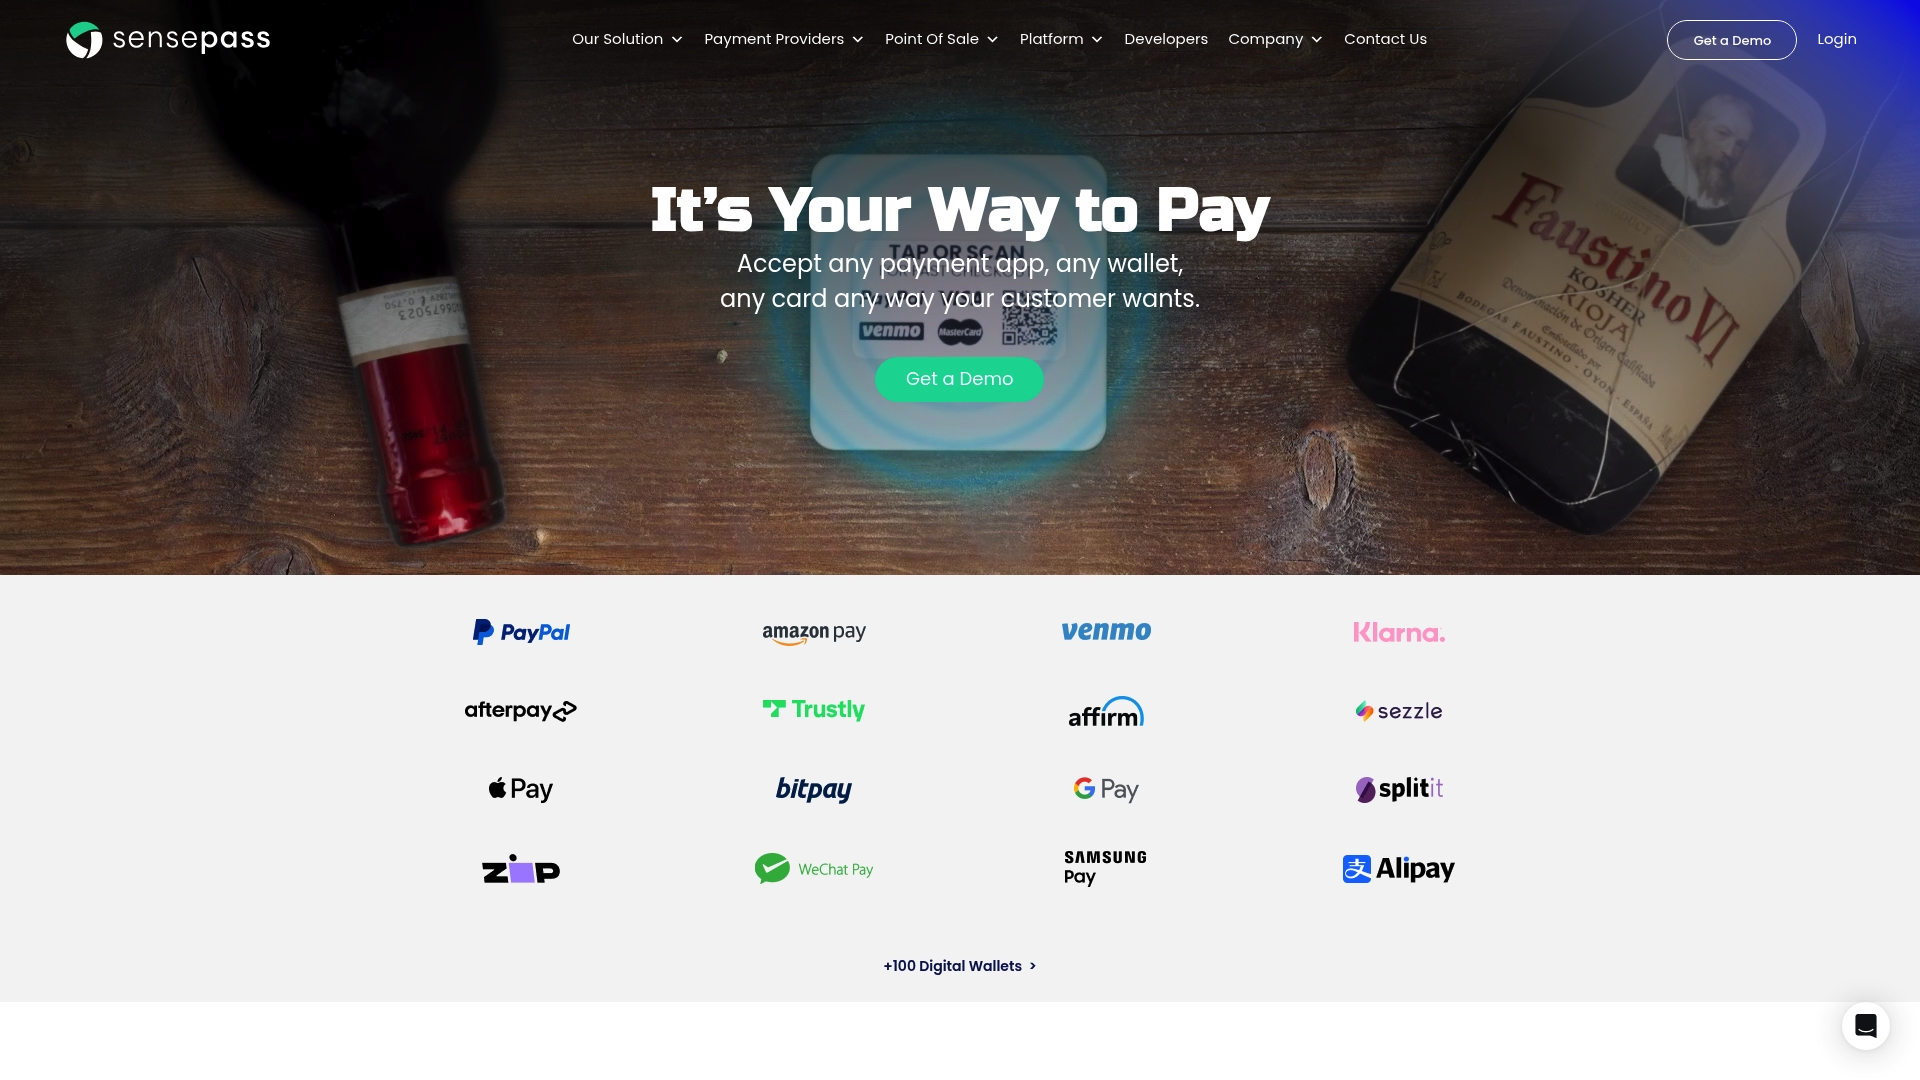
Sensepass integrates with major platforms including NetSuite, SuiteCommerce, Oracle Xstore, Aptos, Shopify POS, BigCommerce, Storis, NCR, and Dynamics365. For crypto specifically, Sensepass supports BitPay and Coinbase alongside digital wallets (PayPal, Venmo, Apple Pay, Google Pay, Alipay, Amazon Pay, WeChat), BNPL options (Klarna, Sezzle, ZIP, Splitit, Afterpay), financing (WeGetFinancing, Affirm), and Pay by Bank (Trustly, LinkMoney). Sensepass is processor-agnostic, giving merchants access to 50+ card processors for maximum flexibility. For retailers building a complete omnichannel payment strategy, Sensepass provides the infrastructure to add crypto without disrupting what already works.
FAQ
What does the IRS require for crypto payment reporting?
The IRS treats cryptocurrency as property. Every payment received must be recorded as ordinary income at the USD fair market value on the date of receipt, and any subsequent disposal is a taxable capital gains event.
When does a business need an MSB license for crypto?
A business needs FinCEN MSB registration and potentially state licensing when it exchanges crypto for cash or holds customer funds. Simply accepting crypto as payment for goods or services generally does not trigger MSB obligations.
What is the $10,000 reporting threshold for crypto transactions?
Crypto transactions over $10,000 require filing IRS Form 8300, the same rule that applies to large cash transactions. Businesses must also apply AML and KYC protocols based on their risk profile and transaction volume.
Why must webhook handlers be idempotent?
Payment gateways retry failed webhook notifications, which means your system may receive the same payment event multiple times. Idempotent handlers process duplicate events without double-fulfilling orders or creating accounting errors.
How should businesses track cost basis for crypto payments?
Cost basis must be calculated per wallet using block timestamps and exchange price data at the time of receipt. Relying on exchange-provided cost basis figures leads to incorrect capital gains calculations and IRS CP2000 notices.
Recommended
- How to start a payment processing business in 2026 – Omnichannel payments at the Point Of Sale | Sensepass
- How to Simplify Call Center Payments: A 2026 Guide – Omnichannel payments at the Point Of Sale | Sensepass
- Setting Up Crypto Payment Options for Retailers – Omnichannel payments at the Point Of Sale | Sensepass
- Crypto Payment Gateway Market 2025: Trends, Growth & Future Outlook

 New York Office
260 Madison Ave Suite 8018 New York NY 10016

