
How to Add Bank Transfer Options for Retailers
June 17, 2026
TL;DR:
- Adding bank transfer options allows for lower-cost, account-to-account payments that meet customer preferences and reduce dependence on card networks. Setting up ACH-compatible bank accounts with supported processors like Stripe, WooCommerce, or QuickBooks enables businesses to process transfers securely and efficiently, following proper validation and compliance procedures. Incorporating bank transfers into checkout strategies can significantly cut costs, improve transaction reliability, and serve high-ticket or B2B customers who prefer direct bank payments.
Bank transfer payment options are direct account-to-account payment methods that let customers pay from their bank without using a credit card. Knowing how to add bank transfer options to your checkout gives you a lower-cost alternative to card payments, reduces your dependency on card networks, and meets the preferences of customers who avoid credit. Platforms like WooCommerce and QuickBooks already support this natively, and processors like Stripe make it straightforward to configure. This guide walks you through every step: prerequisites, platform-specific setup, fee structures, and the mistakes that cost retailers time and money.
What do you need before adding bank transfer options?
Getting set up correctly from the start saves you from compliance headaches and failed transactions later. Three things must be in place before you configure anything.
A business bank account that supports ACH. ACH (Automated Clearing House) is the standard U.S. network for electronic bank-to-bank transfers. Your bank account must be ACH-enabled, which most U.S. business checking accounts are by default. Confirm this with your bank before proceeding.
A compatible payment processor or PSP. You need a third-party payment processor that supports ACH payments. Processors like Helcim or Payment Depot offer ACH processing with invoicing and recurring payment tools built in. Stripe also supports bank transfer activation directly in its dashboard. Choose a processor that fits your transaction volume and business model.
Authorization and compliance documentation. Accepting ACH payments requires written or digital authorization from each customer before debiting their account. This is a legal requirement under NACHA rules. Prepare a clear authorization form or use a processor that handles this within its hosted checkout flow.
- Verify your business bank account is ACH-capable
- Select a processor that supports ACH and matches your sales volume
- Prepare customer authorization forms or confirm your processor handles them
- Gather your bank account number, routing number, and IBAN if selling internationally
Pro Tip: Before going live, run a test micro-deposit transaction to confirm your account and routing numbers are correct. A single digit error can delay settlements by days.
How to configure bank transfer payment methods on popular platforms
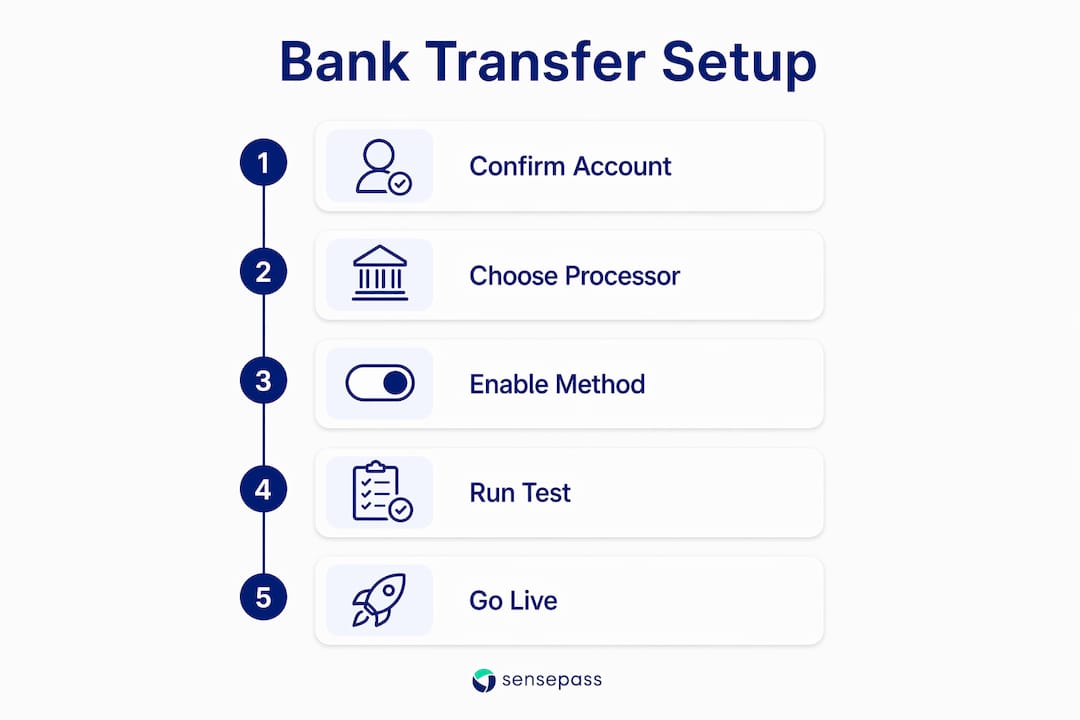
The setup process varies by platform, but the core steps follow the same logic: enable the payment method, enter your bank details, and verify the connection.
WooCommerce direct bank transfer (BACS)
WooCommerce includes a built-in bank transfer module called BACS (Bank Account Credit Scheme). The WooCommerce setup process follows these steps:
- Log into your WordPress admin panel and go to WooCommerce > Settings > Payments.
- Find Direct Bank Transfer in the list and click Enable.
- Click Set Up to open the configuration screen.
- Enter your bank account details: account name, account number, sort code or routing number, bank name, and IBAN if applicable.
- Add instructions that will appear on the order confirmation page, telling customers exactly where to send the payment.
- Click Save Changes.
For multi-currency stores, WooCommerce multi-account setup lets you add one row per bank account using the Add Account button. Label each account with its currency clearly so customers send funds to the right destination.
QuickBooks online bank account linking
QuickBooks Online takes a different approach. Rather than collecting payments at checkout, it connects your bank via login credentials to import transactions automatically for reconciliation. Go to Banking > Connect Account, select your bank, and authenticate with your online banking credentials and multi-factor authentication. QuickBooks then pulls in transactions for you to categorize and match against invoices.
Stripe bank transfer activation
In Stripe, navigate to Dashboard > Settings > Payment Methods. Find Bank Transfers and toggle it on. Stripe supports ACH Credit Transfer for U.S. customers and will generate a unique virtual bank account number for each customer. This eliminates the risk of customers sending funds to the wrong account.
| Platform | Setup Location | Key Detail Required | Time to Activate |
|---|---|---|---|
| WooCommerce | Settings > Payments > Direct Bank Transfer | IBAN, account number, routing number | Under 10 minutes |
| Stripe | Dashboard > Settings > Payment Methods | Bank account verification | Under 15 minutes |
| QuickBooks Online | Banking > Connect Account | Online banking credentials | Under 5 minutes |
Pro Tip: Use Stripe’s virtual account number feature whenever possible. It assigns a unique account number per customer, which makes reconciliation automatic and eliminates misdirected transfers.
How do fees and settlement times work for bank transfers?
Cost and timing are the two factors that most directly affect whether bank transfers make sense for your business model.
ACH processing fees through a third-party processor typically run 0.5%–1.5% plus $0.20–$1.50 per transaction. That is significantly lower than the 2%–3% you pay on most credit card transactions. For high-ticket items or B2B invoices, the savings add up fast.
Settlement timing follows a predictable pattern: standard ACH takes 1–3 business days, while real-time payment rails like RTP (Real-Time Payments) or FedNow provide immediate confirmation. Wire transfers settle fastest but carry the highest fees, while ACH is free or low cost but slower. The right choice depends on your cash flow requirements.
| Payment Type | Typical Fee | Settlement Time | Best For |
|---|---|---|---|
| ACH Transfer | 0.5%–1.5% + $0.20–$1.50 | 1–3 business days | Recurring billing, B2B invoices |
| Real-Time Rails (RTP/FedNow) | Varies by processor | Immediate | Urgent or high-value transactions |
| Wire Transfer | $15–$30 flat | Same day or next day | Large one-time payments |
| Credit Card | 2%–3% | 1–2 business days | General retail |
Security is non-negotiable when you accept bank transfers. Follow these practices:
- Encrypt all bank account data in transit and at rest
- Use tokenization to avoid storing raw account numbers on your servers
- Require customer identity verification before processing large transfers
- Monitor for duplicate or unusual transaction patterns using your processor’s fraud tools
- Review your retail payment security practices regularly as threat patterns evolve
“ACH payments are difficult to reverse once completed. Validation steps to confirm account details before processing are not optional. They are the difference between a clean transaction and a weeks-long correction process.” — Bankrate
What are the most common pitfalls when enabling bank transfers?
Most bank transfer failures trace back to data entry errors or incomplete customer instructions. Knowing where things go wrong lets you build a process that prevents them.
Incorrect routing or account numbers. A single transposed digit sends funds to the wrong account. ACH errors are hard to reverse and corrections can take weeks. The fix is to use hosted checkout pages that validate account numbers in real time rather than relying on customers to type them manually.
- Always display your full bank details on the order confirmation page and in the confirmation email
- Use a processor that offers micro-deposit verification for new customer accounts
- Require customers to re-enter their account number to confirm it before submission
- Set clear payment deadlines in your order instructions (for example, “payment due within 3 business days”)
- Build an automated follow-up email for orders awaiting bank transfer confirmation
Delays from incomplete customer information. If a customer forgets to include an order reference number in their transfer, matching the payment to the correct order becomes manual work. Stripe’s virtual account number system solves this automatically. For WooCommerce BACS, include a mandatory reference field in your checkout instructions.
Managing multiple bank accounts without confusion. If you operate in multiple currencies, label each account explicitly in your WooCommerce settings. Customers should never have to guess which account to use. A clear table in your checkout instructions showing currency, bank name, and account number removes ambiguity entirely.
Pro Tip: Set up a dedicated bank account solely for receiving customer transfers. Keeping it separate from your operating account makes reconciliation faster and reduces the risk of processing errors during month-end close.
For retailers managing multiple payment methods at once, a multi-method checkout setup reduces the operational complexity of tracking bank transfers alongside card and wallet payments.
Key takeaways
Adding bank transfer options requires the right processor, correct account setup, and clear customer instructions to work reliably across platforms.
| Point | Details |
|---|---|
| Prerequisites come first | Confirm ACH capability, select a compatible processor, and prepare authorization forms before setup. |
| Platform setup is straightforward | WooCommerce, Stripe, and QuickBooks each have native bank transfer tools that take under 15 minutes to activate. |
| Fees are lower than cards | ACH processing costs 0.5%–1.5% plus a small per-transaction fee, well below standard card rates. |
| Validation prevents costly errors | Use hosted checkout pages and micro-deposit verification to eliminate account number mistakes. |
| Security requires active management | Encrypt account data, tokenize storage, and monitor for fraud patterns from day one. |
Why bank transfers deserve a permanent spot in your checkout
Most retailers I work with treat bank transfers as a niche option they add reluctantly. That thinking is backward. Bank transfers are the preferred payment method for a significant portion of B2B buyers and high-ticket consumers who simply do not want to put large purchases on a card. If your checkout does not offer it, those customers either abandon or call your team to arrange a wire manually. Neither outcome is good.
The real strategic value is cost reduction. When you shift even 15%–20% of your transaction volume from cards to ACH, the fee savings are material. For a retailer processing $500,000 per month, moving a fifth of that to ACH at 0.8% versus 2.5% on cards saves roughly $8,500 per month. That is not a rounding error.
My honest recommendation: do not treat bank transfers as a standalone addition. Integrate them as part of a broader payment method strategy. The retailers who win are the ones who give customers genuine choice at checkout, whether that is ACH, digital wallets, BNPL, or cards. Balancing speed and cost means offering real-time rails for urgent transactions and standard ACH for recurring billing. Trying to manage that manually across multiple processors is where things break down. An omnichannel payment gateway that handles routing logic for you is worth every dollar of the integration cost.
— Vlad
How Sensepass makes bank transfer integration part of a bigger picture
If you are ready to go beyond a single bank transfer setup and build a payment system that handles every method your customers prefer, Sensepass is built for exactly that.

Sensepass is a processor-agnostic payment orchestration platform that integrates with major retail and ecommerce systems including NetSuite, SuiteCommerce, Oracle Xstore, Aptos, Shopify POS, BigCommerce, Storis, NCR, and Dynamics365. It supports Pay by Bank options through Trustly and LinkMoney alongside digital wallets like PayPal, Venmo, Apple Pay, Google Pay, Alipay, WeChat, and Amazon Pay. You also get BNPL options from Klarna, Sezzle, ZIP, Splitit, and Afterpay, financing through WeGetFinancing and Affirm, and crypto payments via BitPay and Coinbase. With access to 50+ card processors, you choose the processing relationship that fits your margins. Explore the full omnichannel payments guide for retailers to see how Sensepass brings it all together.
FAQ
What is ACH and why does it matter for bank transfers?
ACH (Automated Clearing House) is the U.S. electronic network that processes direct bank-to-bank transfers. It is the standard method for accepting bank payments in the U.S. and is supported by processors like Stripe, Helcim, and Payment Depot.
How long does a bank transfer take to settle?
Standard ACH transfers settle in 1–3 business days. Real-time payment rails like RTP or FedNow provide immediate confirmation for time-sensitive transactions.
Can i add bank transfer options to WooCommerce for free?
Yes. WooCommerce includes a built-in Direct Bank Transfer module at no extra cost. You enable it under Settings > Payments and enter your bank account details directly in the dashboard.
What happens if a customer sends a transfer to the wrong account?
ACH transfers are difficult to reverse once processed, and corrections can take weeks. Using hosted checkout pages with real-time account validation or Stripe’s virtual account numbers prevents most of these errors before they happen.
How much does it cost to accept bank transfers?
ACH processing fees typically range from 0.5%–1.5% plus $0.20–$1.50 per transaction through a third-party processor. This is substantially lower than standard credit card processing rates of 2%–3%.
Recommended

 New York Office
260 Madison Ave Suite 8018 New York NY 10016

