
How to Add Financing Options In-Store for Retailers
July 7, 2026
TL;DR:
- Adding in-store financing increases sales by providing flexible payment options that reduce purchase abandonment. Retailers must ensure their POS systems support API integration, understand provider costs, and train staff to explain financing clearly. Promoting financing early through signage and staff conversations significantly boosts customer adoption and order values.
In-store financing is defined as a payment program that lets customers split a purchase into installments, paid over weeks or months, at the point of sale. Knowing how to add financing options in-store is one of the highest-leverage decisions a retail business owner can make. Up to 70% of shoppers abandon a purchase when no financing is available. That single data point explains why retailers who offer payment plans consistently report higher average order values and stronger customer loyalty than those who do not.
How to add financing options in-store: prerequisites and tools
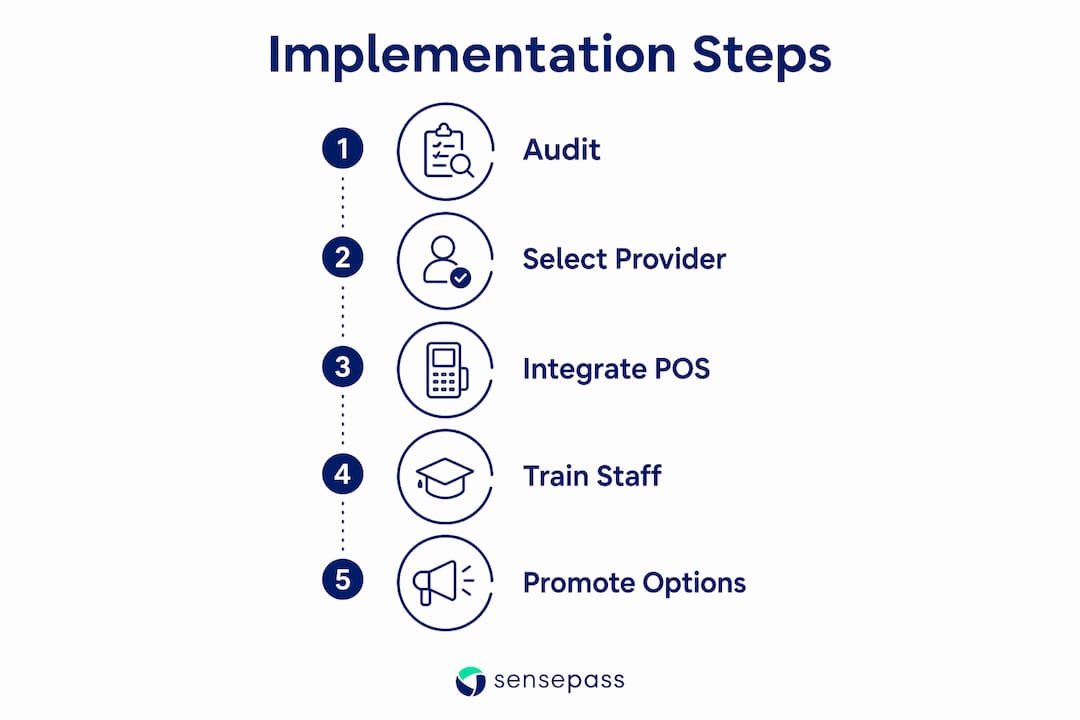
Before you sign a contract with any financing provider, audit what you already have. Your POS system, payment gateway, and staff workflows all need to support the new program before a single customer applies.
What to evaluate before you start:
- POS compatibility. Confirm your current system supports API connections to third-party financing providers. Systems like NetSuite, Oracle Xstore, Aptos, Shopify POS, NCR, Dynamics365, and Storis all support external payment integrations, but the depth of that support varies by version and configuration.
- Financing provider terms. POS financing interest rates range from 3% to over 30%, with additional fees such as late charges and processing costs layered on top. Read the full fee schedule, not just the headline rate.
- Total cost of financing. Compare the full cost across providers, including merchant discount rates and integration fees. The cheapest integration often hides the most unfavorable terms.
- Hardware and software upgrades. If your POS hardware is outdated, equipment financing loans for retail technology range from $5,000 to $500,000 with approvals in as little as 2–5 days.
- Staff readiness. Your team needs to explain financing clearly and confidently. Budget time for training before launch.
Pro Tip: Request a sandbox or demo environment from your financing provider before going live. Testing the full application flow on your actual POS hardware catches integration problems before customers see them.
| Evaluation Area | Key Question |
|---|---|
| POS compatibility | Does your system support API-based financing integrations? |
| Provider terms | What is the total cost including fees, not just the interest rate? |
| Hardware readiness | Do you need equipment upgrades to support the new workflow? |
| Staff training | Can your team explain financing options clearly at the register? |
| Compliance | Does the program meet consumer lending regulations in your state? |
What is the step-by-step process to implement in-store financing?
Implementation follows a clear sequence. Skipping steps, especially testing, is the most common reason a financing launch fails to convert customers.
-
Choose between third-party and in-house financing. Retailers face a fundamental choice: outsource credit risk to a third-party lender who pays you immediately, or run your own lending program and retain full control but absorb the operational risk. Third-party programs like WeGetFinancing and Affirm are the faster path for most retailers. In-house programs suit larger operations with dedicated finance staff.
-
Select your financing partners. Evaluate providers on approval rates, customer experience, and integration quality. Sensepass connects retailers to financing options including WeGetFinancing and Affirm, alongside BNPL providers like Klarna, Sezzle, ZIP, Splitit, and Afterpay. Having multiple options at checkout increases the chance that every customer finds a plan that works.
-
Integrate with your POS and payment platform. A frictionless financing option requires plug-and-play API integration that enables real-time credit decisioning at checkout. Work with your POS vendor or a payment orchestration layer to connect the financing provider’s API to your existing workflow. Sensepass integrates with platforms including NetSuite, SuiteCommerce, Shopify POS, BigCommerce, NCR, and Dynamics365, among others.
-
Set up digital application channels. Customers should be able to apply on a tablet at the register, on their phone via a QR code, or through a self-checkout kiosk. Reducing friction in the application step directly increases approval and adoption rates.
-
Train your staff. Every associate needs to know how to introduce financing, walk a customer through the application, and answer basic questions about terms. Role-play common objections before launch.
-
Test the full checkout flow. Run at least 10 complete test transactions across different financing amounts and customer profiles. Confirm that approvals, declines, and partial approvals all route correctly in your POS.
-
Launch and monitor. Track financing adoption rate, average order value on financed purchases, and approval rates weekly for the first 90 days. Adjust your promotion strategy based on what the data shows.
Pro Tip: Start with one financing provider and one store location. A controlled launch gives you clean data and lets you fix problems before scaling across your full retail footprint.
What are the common mistakes when adding in-store financing?
Most financing programs underperform not because of poor product selection, but because of avoidable operational errors.
- Manual data re-entry. System friction from manual entry between your POS and financing platform causes high error rates and delays. This kills the customer experience faster than a declined application. API integration is not optional; it is the baseline requirement.
- Underestimating in-house lending complexity. In-house financing requires strong underwriting and collections discipline. Weak risk management here leads to business failure more often than poor sales do. Modern loan management systems automate underwriting, collections, and compliance, but they still require dedicated oversight.
- Ignoring total cost. Merchants often focus on integration ease and miss the full fee structure. A provider charging a 5% merchant discount rate on every financed sale costs far more than one charging 2%, even if the integration takes longer to set up.
- Compliance gaps. Consumer lending is regulated at both the federal and state level. Disclosures, interest rate caps, and application processes all carry legal requirements. Consult a compliance attorney before launching any financing program, especially an in-house one.
“The biggest risk in retail financing is not that customers won’t use it. The risk is that you build a program with the wrong provider terms, poor system integration, and no compliance review, and then scale it before you discover the problems.”
How do you promote financing options in-store to maximize sales?
Financing adoption rises sharply when customers see it early in their shopping experience, not just at the register. Promotion works best when it starts at the product display and follows the customer through every touchpoint to checkout.
-
Put financing on product tags and shelf signage. Show the monthly payment amount next to the full price on every high-ticket item. “Own this for $42/month” converts better than “$499.” Customers make purchase decisions based on monthly affordability, not total price.
-
Use window and entrance signage. Customers who know financing is available before they enter the store shop with a different mindset. They consider higher-priced items they would otherwise ignore.
-
Train staff to introduce financing early. The best time to mention financing is when a customer picks up a product, not when they hesitate at the register. A simple line like “We offer payment plans starting at $X per month” removes the price barrier before it forms.
-
Add financing messaging to digital touchpoints. Your website, email campaigns, and social media should all reference in-store financing. Customers who research online before visiting the store should already know you offer payment plans. This is a core principle of omnichannel payment strategy.
-
Use self-checkout and kiosk screens. Display financing options on every digital screen in the store. A customer browsing a self-checkout kiosk who sees “Apply for financing in 60 seconds” is far more likely to complete a large purchase than one who does not.
Retailers who combine visible in-store signage with staff-led conversations about financing see the strongest lift in average order value. The conversion rate impact of financing promotion compounds when every touchpoint reinforces the message.
Key Takeaways
Adding financing options in-store requires the right technology integration, clear provider terms, and consistent promotion across every customer touchpoint to drive meaningful sales results.
| Point | Details |
|---|---|
| Audit before you launch | Confirm POS compatibility and read the full fee structure before signing with any provider. |
| API integration is non-negotiable | Manual data entry between systems causes errors and kills the customer experience. |
| Third-party programs reduce risk | Outsourcing credit risk to providers like WeGetFinancing or Affirm is faster and safer for most retailers. |
| Promote financing early | Show monthly payment amounts on product tags and signage, not just at checkout. |
| Monitor the first 90 days | Track adoption rate, average order value, and approval rates weekly to catch problems early. |
My take on what actually moves the needle with in-store financing
I’ve seen retailers spend months selecting the perfect financing provider, then launch with zero in-store signage and wonder why adoption is flat. The technology decision matters, but it is not the hard part. The hard part is changing how your staff talks to customers and how your store communicates value before anyone reaches the register.
The retailers I’ve watched succeed with financing treat it like a product, not a payment method. They train staff the same way they train them on a new product line. They put financing messaging on the floor, not just in the fine print at checkout. They also pick one financing partner to start, get the integration right, and then add more options once the baseline works.
The in-house versus third-party decision gets overthought. For most independent and mid-size retailers, third-party financing through a provider like WeGetFinancing or Affirm is the right call. You get paid immediately, the credit risk sits with the lender, and your operational burden stays manageable. In-house programs make sense when you have the volume, the staff, and the risk management infrastructure to support them. Most retailers do not, at least not at the start.
One more thing: do not skip the compliance review. Consumer lending regulations vary by state, and the penalties for non-compliance are serious. A one-time legal review before launch costs far less than a regulatory problem after.
— Vlad
How Sensepass helps retailers add financing at the point of sale
Sensepass is a payment orchestration layer built for retailers who need to connect multiple payment methods to a single, integrated checkout experience.

Sensepass integrates with major POS platforms including NetSuite, SuiteCommerce, Oracle Xstore, Aptos, Shopify POS, BigCommerce, Storis, NCR, and Dynamics365. It supports financing options through WeGetFinancing and Affirm, BNPL through Klarna, Sezzle, ZIP, Splitit, and Afterpay, digital wallets including PayPal, Venmo, Apple Pay, Google Pay, Alipay, Amazon Pay, and WeChat, crypto payments via BitPay and Coinbase, and Pay by Bank through Trustly and LinkMoney. Sensepass is processor-agnostic, giving you access to 50+ card processors. For a full breakdown of how omnichannel payment integration works in retail, the omnichannel payments guide covers the complete setup process. You can also review the financing setup steps built specifically for retail POS environments.
FAQ
What is in-store financing and how does it work?
In-store financing lets customers apply for a payment plan at the point of sale and split a purchase into monthly installments. Approval happens in real time through a third-party lender or an in-house program, and the retailer typically receives full payment immediately when using a third-party provider.
How much does it cost to offer financing in a retail store?
POS financing costs vary widely. Interest rates range from 3% to over 30%, and providers often add merchant discount rates, processing fees, and late charge structures on top. Always compare the total cost across providers, not just the stated interest rate.
Do I need to upgrade my POS system to add financing?
Not always, but your POS must support API integration with your chosen financing provider. If your hardware or software is outdated, equipment financing loans for retail technology range from $5,000 to $500,000 with approvals in 2–5 days.
What is the difference between third-party and in-house financing?
Third-party financing outsources credit risk to a lender who pays the retailer immediately. In-house financing keeps full control with the retailer but requires underwriting, collections, and compliance infrastructure. Most retailers start with third-party programs and move to in-house only when volume and operational capacity justify it.
How do I get customers to actually use financing options?
Promote financing early with monthly payment amounts on product tags, entrance signage, and staff conversations. Customers who see financing options at the product display are far more likely to use them than those who only hear about it at checkout.
Recommended
- Offering Financing at Checkout: A Retailer’s 2026 Guide – Omnichannel payments at the Point Of Sale | Sensepass
- Retail Financing Option Setup Steps for Retailers – Omnichannel payments at the Point Of Sale | Sensepass
- Your Guide to Flexible Payment Options in Retail – Omnichannel payments at the Point Of Sale | Sensepass
- How To Connect Alternative Payment Methods to Shopify POS

 New York Office
260 Madison Ave Suite 8018 New York NY 10016

