
How to choose the best payment processor for Shopify
May 11, 2026
TL;DR:
- Running a Shopify store incurs significant transaction fees that can compound with the wrong payment processor. Shopify Payments offers lower costs and seamless integration, while third-party processors often add extra fees and setup complexity. Selecting the right processor based on cost, features, and growth plans is crucial for optimizing margins and supporting omnichannel retail expansion.
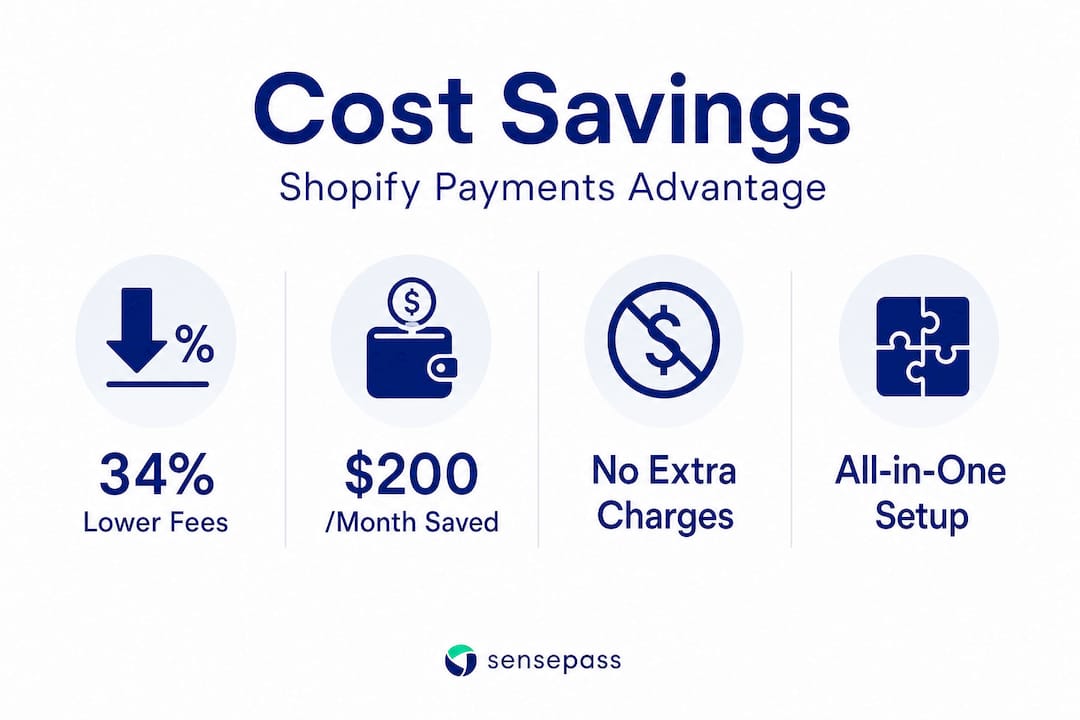
Running a Shopify retail store means every transaction fee chips away at your margin. What surprises many retailers is how quickly those fees compound when the wrong processor is in place. Third-party processors cost up to 34% more than Shopify Payments once you factor in the additional Shopify transaction fees layered on top of the processor’s own rates. Multiply that across hundreds of monthly orders and you’re looking at hundreds of dollars in avoidable losses. This guide walks you through how processors work within Shopify, what to evaluate before committing, how to set one up correctly, and how to verify your setup is actually saving you money.
Table of Contents
- How payment processors work with Shopify
- What to consider before choosing a payment processor
- Step-by-step: Setting up and integrating payment processors
- Verifying performance and optimizing your payment processing
- The overlooked truth about payment processors for Shopify retailers
- Enhance Shopify payments with leading omnichannel solutions
- Frequently asked questions
Key Takeaways
| Point | Details |
|---|---|
| Extra Shopify fees matter | Using third-party processors adds up to 2% in transaction fees, increasing costs significantly. |
| Coverage influences choice | Shopify Payments is simple but has country and industry restrictions, making third-party options essential for some. |
| Integration impacts experience | Smooth setup and omnichannel compatibility maximize both savings and customer satisfaction. |
| Ongoing audits save money | Regularly verify processor fees and performance to avoid hidden costs and maintain flexibility. |
How payment processors work with Shopify
Now that you know the financial stakes, let’s break down how payment processors actually function within Shopify, and what choosing one means for your day-to-day retail operations.
When a customer pays at your store or checkout page, a payment processor acts as the digital bridge between the customer’s bank, the card network, and your merchant account. Shopify sits on top of all this, routing each transaction through whichever processor you’ve connected. Shopify gives you two main paths: use its built-in solution, Shopify Payments, or connect a third-party processor through its partner integrations.
Shopify Payments is powered by Stripe on the backend and is fully embedded into your dashboard. There are no extra transaction fees beyond the processor rate, which ranges from approximately 2.4% to 2.9% plus 30 cents depending on your plan. The moment you switch to a third-party option, Shopify adds its own transaction fee on top. That means additional Shopify transaction fees of 2% on Basic, 1% on the Shopify plan, and 0.5% on Advanced, creating a significant cost disadvantage for most retailers.
For omnichannel retailers, the processor you choose also affects what happens in-store. If you’re connecting payment methods to Shopify POS, your processor needs to support card-present transactions, contactless payments, and ideally Buy Now, Pay Later options at the point of sale. Not every third-party processor is built for that level of integration.
Here’s a quick comparison to anchor the decision:
| Feature | Shopify Payments | Third-party processor |
|---|---|---|
| Extra Shopify transaction fee | None | 0.5% to 2% per transaction |
| Setup complexity | Low | Medium to high |
| POS compatibility | Native | Varies by integration |
| Available countries | 23+ countries | Up to 47+ (e.g., Stripe) |
| BNPL support | Limited | Broader via integrations |
| High-risk industry support | No | Possible (varies) |
| Payout speed | 2 to 3 business days | 2 to 7 business days |
Key factors to keep in mind when evaluating processors:
- Cost structure: Combined processor rate plus any Shopify transaction fee
- Payment method support: Digital wallets, BNPL, crypto, and bank transfers
- POS readiness: In-store hardware compatibility and contactless payment support
- Geographic availability: Where your customers are located
- Dispute handling: Chargeback fees and dispute resolution processes
For retailers looking to add modern options like integrating Afterpay on Shopify, third-party processors or payment orchestrators often open more doors than Shopify Payments alone. Reviewing tips for choosing free payment gateways can also help you spot hidden fees before they surface on your monthly statements.
Pro Tip: Always pull both Shopify’s fee schedule and your processor’s rate card before you make a final selection. Total cost is what matters, not just the headline processing rate.
What to consider before choosing a payment processor
Understanding how processors fit into Shopify is one step. Next, let’s cover what factors deserve your attention before making a commitment.
Choosing a processor is not just a technical decision. It shapes how customers pay, how quickly funds reach your account, how you handle disputes, and whether your business can grow internationally without platform disruption. The right checklist here can save you a significant migration headache later.
Evaluation criteria every Shopify retailer should assess:
- Platform availability: Is the processor available in all your current and target markets?
- Industry eligibility: Certain processors decline high-risk categories such as firearms, CBD, or subscription boxes
- Transaction fees: Total cost including Shopify’s surcharge, if any
- Payout timing: How fast does money arrive in your bank account?
- Omnichannel compatibility: Does the processor work across your online store, POS, and call center?
- BNPL and alternative payment support: Can customers use Klarna, Afterpay, or Affirm?
- Dispute management: What is the chargeback fee and how hands-on is the dispute process?
- Customer support quality: Is there real support available when transactions fail during a peak sales period?
Geography matters more than most retailers realize. Shopify Payments is available in 23+ countries, while processors like Stripe support 47+ countries. If you’re selling globally or planning to expand, that gap could force a disruptive processor switch mid-growth.
Note: If your business operates in a country where Shopify Payments isn’t available, or falls into a high-risk category, a third-party processor is not optional. It’s your only path. Plan for it early so it doesn’t catch you by surprise.
For retailers adding flexible payment options, accepting Klarna on Shopify POS at the point of sale requires a processor or payment orchestrator that specifically supports that integration. Not every provider does, and verifying this before you commit saves significant rework.
Omnichannel compatibility is where many retailers underestimate their needs. A processor that handles your online store but struggles with in-store card-present transactions creates friction at the worst possible moment. Reviewing processor differences for retail integration helps clarify which providers genuinely support a unified commerce model.
For a broader strategic view, the gateway selection tips for retailers resource covers how to evaluate risk, integration quality, and long-term scalability before signing any agreement.
Pro Tip: If you serve multiple countries, map out both Shopify’s and your shortlisted processor’s coverage before committing. A mismatch discovered after launch often means costly platform migrations and customer disruption.
Step-by-step: Setting up and integrating payment processors
After considering your options, you’re ready to get hands-on. Here’s a clear, actionable guide to actually setting up your Shopify payment solution.
Before you begin, gather the following:
- Legal business name and registration documents
- Tax identification number (EIN for US businesses)
- Bank account details for payouts
- Your Shopify plan level (this determines your transaction fee tier)
- Any industry classification codes relevant to your products
Setting up Shopify Payments:
- From your Shopify admin, go to Settings and then Payments.
- Click “Activate Shopify Payments” and complete the identity verification form.
- Enter your banking information for direct deposits.
- Configure supported payment methods, including Apple Pay, Google Pay, and Shop Pay.
- Test the checkout with a real or test transaction to confirm everything routes correctly.
- Confirm your payout schedule and currency settings match your business needs.
Setting up a third-party processor (using Stripe as an example):
- Create and verify a Stripe account at stripe.com.
- In Shopify admin, go to Settings, then Payments, then choose “Third-party providers.”
- Search for and select Stripe from the provider list.
- Enter your Stripe API keys (found in your Stripe dashboard under Developers).
- Configure payment methods within Stripe’s dashboard, including any BNPL or wallet options.
- Run a test transaction through your Shopify storefront to verify the connection.
- Review your Shopify billing to confirm the correct transaction fee tier is applied.
Here’s a side-by-side summary of setup complexity and estimated time:
| Processor setup | Steps involved | Estimated time | Complexity |
|---|---|---|---|
| Shopify Payments | 6 steps, native setup | 30 to 60 minutes | Low |
| Stripe (third-party) | 7 steps, API connection | 1 to 2 hours | Medium |
| PayPal (third-party) | 5 steps, OAuth connection | 45 to 90 minutes | Medium |
| Custom processor | Variable, developer required | 4 to 8+ hours | High |
Common mistakes to avoid:
- Entering mismatched business details between Shopify and your processor account, which can trigger account holds
- Forgetting to disable the old processor before enabling a new one, creating duplicate routing
- Not confirming your payout currency matches your bank account currency
- Skipping test transactions and discovering routing errors only after real customer payments fail
One important benchmark to keep in mind: at $10,000 per month in sales, Shopify Payments saves approximately $200 per month compared to using a third-party processor on the Basic plan. Chargebacks carry a fee of $15 per dispute, regardless of the processor you use. These numbers give you a concrete savings target to verify once your setup is live.
For a deeper walkthrough on connecting payment processors to Shopify POS, including hardware configuration and in-store routing, the SensePass resource library covers the steps in detail. If you’re unsure which option fits your situation, the gateway selection for Shopify guide helps narrow it down based on your business model and transaction volume.
Verifying performance and optimizing your payment processing
You’ve implemented your payment solution. Now let’s ensure it actually delivers the promised value and supports business growth.
Setting up a processor is the beginning of the process, not the end. Retailers who treat it as a one-time task often discover months later that hidden fees, misconfigured routing, or outdated integrations have quietly eroded their margins. Monthly verification is a practical discipline, not an optional audit.
Monthly verification checklist:
- Compare your actual processing fees against expected rates based on your plan
- Review your Shopify billing for any unexpected transaction surcharges
- Check payout timing to confirm funds arrive within your expected window
- Test checkout flows on both desktop and mobile, online and in-store
- Review your chargeback log and confirm dispute fees match the $15 benchmark
- Verify that all enabled payment methods (wallets, BNPL, bank transfers) are functioning correctly
- Confirm your processor dashboard and Shopify reports are reconciling accurately
Customer experience testing is as important as fee auditing. A payment method that works on desktop but fails on mobile, or processes online but creates friction in-store, directly reduces conversion. Run full transaction tests from the customer’s perspective at least quarterly. If you’re using a broader mix of payment methods, verify each one independently.
The Shopify Payments cost advantage of up to 34% monthly is only realized if your configuration is correct from day one. Misconfigured accounts, dormant redundant processors, or incorrect plan assignments can silently undermine those savings. Similarly, benchmarking at $10,000 per month with $200 in monthly savings gives you a concrete reference point. If your actual savings fall significantly below that, something in your setup warrants investigation.
For a broader view of how your processor stacks up against alternatives, reviewing expert omnichannel payment comparisons can surface options you haven’t considered, especially for expanding payment method support. Checking Stripe pricing details is also useful if you’re evaluating whether a switch would meaningfully reduce your costs.
Pro Tip: Set a calendar reminder every 30 days to pull your fee statements and compare them against the $200/month savings benchmark for a $10K store. A consistent shortfall is usually a sign of a configuration error or a plan mismatch worth correcting.
When to revisit your processor selection:
- You’re expanding into new countries where your current processor lacks coverage
- You want to add BNPL options like Klarna, Sezzle, Splitit, or Afterpay
- Your monthly volume has grown enough that a higher Shopify plan would eliminate transaction fees
- You’re launching a subscription model that requires more advanced billing features
- Customer complaints about payment failures or limited options are rising
The overlooked truth about payment processors for Shopify retailers
Most payment processor advice focuses on one thing: transaction fees. That’s understandable. Fees are visible, measurable, and directly tied to margin. But after working with retailers across multiple channels and markets, we’ve seen a clear pattern. The retailers who struggle most are not the ones who chose the slightly more expensive processor. They’re the ones who chose the inflexible one.
Here’s the harder truth: a processor that fits perfectly today can become a growth ceiling in 18 months. The retailer who launched on Shopify Payments, then expanded internationally, then discovered it wasn’t available in their new market, now faces a full migration at the worst possible time. The retailer who locked into a single processor for in-store and online didn’t anticipate that their customers would start asking for Klarna, Afterpay, or even crypto payments. These aren’t edge cases anymore.
The payment landscape is moving fast. Digital wallets like Apple Pay, Google Pay, Venmo, and Alipay are now expected, not optional. BNPL options like Klarna, Sezzle, and ZIP are directly influencing purchase decisions, especially for higher-ticket items. Pay by bank options like Trustly and LinkMoney are gaining traction as cost-effective alternatives to card networks. Crypto payments via BitPay and Coinbase are becoming viable for specific customer segments. A processor that doesn’t support these methods, or that requires a full platform swap to add them, is costing you revenue even if the transaction fees look competitive on paper.
The smartest approach treats your processor selection as a strategic infrastructure decision, not a cost optimization exercise. Build for the customers you’re going to have, not just the ones you have today. Reviewing processor impacts on retail strategy from a growth lens rather than a cost lens is how leading retailers stay ahead. Evaluate your entire setup annually and ask one direct question: does this still support where we’re going?
Enhance Shopify payments with leading omnichannel solutions
If this article has helped clarify your processor options, SensePass can take your Shopify payment strategy further. SensePass is a processor-agnostic orchestration layer that integrates seamlessly with Shopify POS and major platforms including NetSuite, Oracle Xstore, Aptos, BigCommerce, NCR, Dynamics365, and more.

With SensePass, you can accept digital wallets (PayPal, Venmo, Apple Pay, Google Pay, WeChat, Alipay, Amazon Pay), BNPL options (Klarna, Afterpay, Sezzle, ZIP, Splitit), financing through Affirm and WeGetFinancing, crypto via BitPay and Coinbase, and Pay by Bank through Trustly and LinkMoney. You also gain access to 50+ card processors, giving you maximum flexibility to optimize costs without being locked into a single provider. Explore omnichannel payments for retailers, review top payment tips for operational excellence, and use the gateway selection tips to find the right fit for your business today.
Frequently asked questions
What are the main fees when using third-party payment processors on Shopify?
Shopify charges an extra transaction fee of up to 2% on top of the processor’s normal rate, making third-party options significantly more expensive than Shopify Payments for most retailers.
When should I use a third-party processor instead of Shopify Payments?
A third-party processor is the right call when Shopify Payments isn’t available in your country, your industry is considered high-risk, or you need specialized features like advanced subscriptions or broader international support.
How much can switching to Shopify Payments save a typical retailer?
A store processing $10,000 per month saves about $200 each month in fees with Shopify Payments on the Basic plan, compared to a typical third-party processor setup.
What is the chargeback fee for payment disputes on Shopify?
The chargeback fee is $15 per dispute and applies across most payment processors connected to Shopify, regardless of whether you use Shopify Payments or a third-party provider.
Recommended
- Essential Payment Gateway Selection Tips for Retailers – Omnichannel payments at the Point Of Sale | Sensepass
- How Do I Integrate Afterpay into Shopify Without Cards? (Setup Guide)
- 7 Key Tips for Choosing a Free Website Payment Gateway – Omnichannel payments at the Point Of Sale | Sensepass
- Payment Gateway vs Payment Processor: Key Differences for Retailers – Omnichannel payments at the Point Of Sale | Sensepass

 New York Office
260 Madison Ave Suite 8018 New York NY 10016

