
How to Manage Mixed Payments in Retail and eCommerce
June 9, 2026
TL;DR:
- Mixed payment management involves accepting multiple payment methods for a single transaction while ensuring accurate reconciliation across systems. Proper handling requires strict sequential processing, normalization of transaction IDs, and utilizing orchestration platforms to unify diverse channels and providers. Investing in this infrastructure proactively prevents reconciliation errors and streamlines multichannel payment operations.
Mixed payment management, also called split-tender processing, is the practice of accepting two or more payment methods against a single transaction and reconciling every leg of that transaction accurately across your systems. If you run a retail store or an eCommerce operation, you already face this: a customer pays part of a $200 order with a gift card, the rest with Apple Pay, and your POS, ERP, and accounting system each need to reflect that split correctly. The challenge is not just accepting the payment. It is keeping order integrity intact, reconciling across providers, and maintaining clean reporting when the payment methods involved span credit cards, digital wallets, buy now pay later (BNPL), and bank transfers. Platforms like SensePass and NetSuite are built to handle exactly this complexity at scale.
How to manage mixed payments: sequential processing and order accuracy
The single most important rule in split-tender processing is this: do not modify the order once the first payment leg has been captured. Changing item quantities, applying discounts, or adjusting prices mid-transaction causes POS system errors that are difficult to reverse and can corrupt the order record entirely. Oracle NetSuite’s retail POS guidance is explicit on this point, and it applies equally to any platform processing sequential tenders.
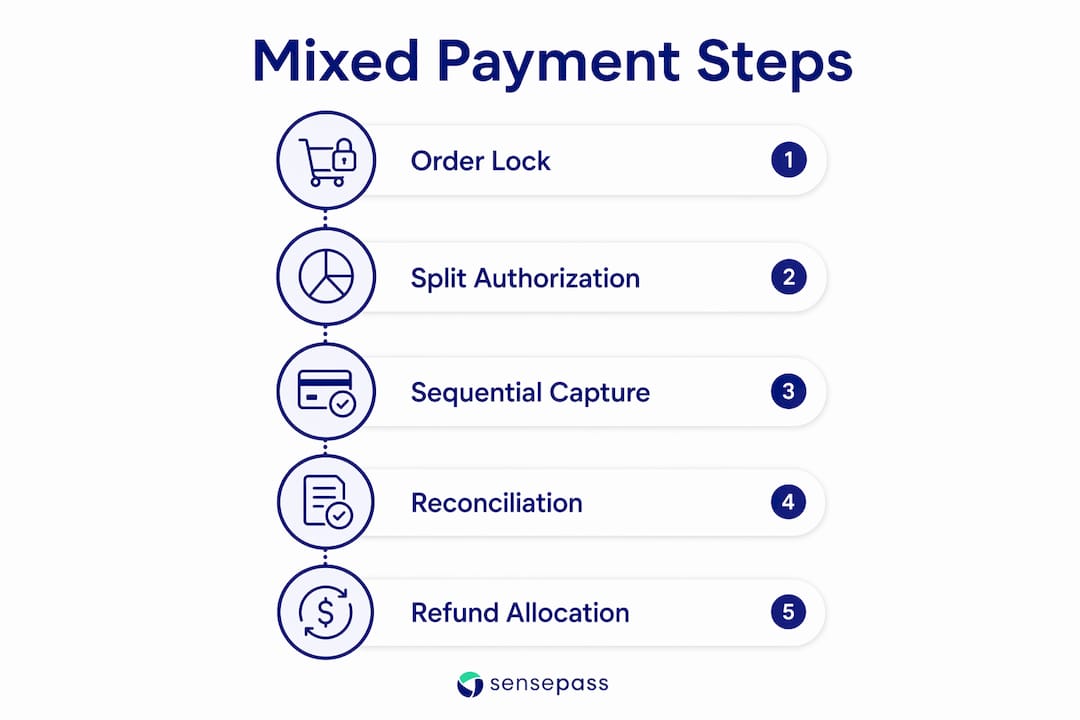
The correct approach follows a controlled sequence:
- Lock the order total before initiating any payment capture. No edits to items, prices, or quantities are permitted once the first tender is accepted.
- Capture the first payment method (for example, a gift card or store credit) and record the authorized amount against the order.
- Calculate the remaining balance automatically. Your POS or payment platform should display the outstanding amount without manual calculation.
- Capture the second payment method (for example, a credit card or Google Pay) for the remaining balance.
- Confirm the full order total is met before closing the transaction. If any leg fails, the system must support partial reversal without voiding the entire order.
- Generate a single order confirmation that itemizes each payment method and amount for the customer record.
Operational risk in split payments is driven by timing and order stability rather than simple arithmetic. A cashier who tries to add a promotional discount after the first card is swiped, or a customer who changes their mind about a gift card mid-transaction, creates a failure state that most POS systems handle poorly.
Pro Tip: Partial authorization modes carry price hold periods. If a customer’s first payment leg is authorized but the second leg times out, the authorization on the first method may expire before the transaction completes. Configure your system to cancel incomplete partial payments automatically after a defined timeout, and train staff on the recovery process so they do not attempt to re-enter a partial order manually.
Common staff mistakes include manually splitting the order into two separate transactions instead of using the split-tender function, and failing to record which card was used for which portion. Both errors create reconciliation problems downstream.
How do you reconcile payments from multiple providers?
Reconciliation across multiple payment providers is where most retail and eCommerce businesses lose time and accuracy. Each payment service provider (PSP) assigns its own proprietary transaction ID. When you accept a Klarna BNPL payment, a Visa credit card, and a PayPal wallet payment in a single day, you receive three separate settlement files with three different ID formats. Joining raw PSP IDs directly is a common and costly mistake. The IDs do not share a common key, so any attempt to match them without normalization produces gaps and duplicates in your ledger.
The solution is a normalization layer that maps every provider’s transaction ID to a single canonical internal ID. This internal ID travels with the order through your POS, ERP, and accounting system, regardless of how many payment legs are involved.
Key reconciliation patterns you need to support:
- One-to-one: A single payment method maps to a single settlement record. This is the simplest case and the least common in mixed payment environments.
- One-to-many: One order generates multiple settlement records, one per payment method. This is the standard split-tender pattern.
- Many-to-one: Multiple partial captures (common in BNPL installment plans) roll up to a single order record.
- Batch settlements: Card processors and digital wallet providers settle in batches, often with a one-to-two-day delay. Your reconciliation engine must match batch totals back to individual order-level transactions.
| Reconciliation challenge | Recommended approach |
|---|---|
| Multiple PSP transaction IDs per order | Assign a canonical internal order ID at transaction creation |
| Settlement timing differences across providers | Use a matching engine that holds unmatched records in a pending state |
| Refunds spanning multiple payment methods | Split refunds across original tenders and generate separate refund records per leg |
| Chargebacks on partial captures | Flag the specific payment leg and isolate it from the settled portion |
| Batch vs. real-time settlement mismatch | Reconcile at the batch level first, then drill down to transaction level |
Refunds deserve special attention. A $100 return on a split-tender order paid with $25 cash and $75 credit card requires two separate refund records. Refunds on split-tender payments create multiple entries in your ERP’s general ledger, each requiring its own GL mapping. If your system is not configured for this, the refund will post incorrectly and trigger a reconciliation discrepancy at month-end. Multi-leg transactions with chargebacks are even more complex, since they cross settlement periods and require a matching engine capable of handling many-to-many relationships between captures and settlements.
Manual reconciliation vs. payment orchestration: which approach scales?
The choice between manual reconciliation and a payment orchestration platform is not a matter of preference. It is a matter of transaction volume and payment method diversity. Manual reconciliation works when you have one processor, one channel, and a small transaction count. It breaks down the moment you add a second PSP, a BNPL provider, or a second sales channel.
| Approach | Suitable for | Key limitation |
|---|---|---|
| Manual reconciliation | Single processor, low volume | Does not scale; error-prone with multiple PSPs |
| Spreadsheet-based matching | Small eCommerce operations | No real-time visibility; high labor cost |
| ERP-native reconciliation (e.g., NetSuite) | Mid-market retailers with one or two PSPs | Limited support for alternative payment methods |
| Payment orchestration platform | Omnichannel retailers with diverse payment methods | Requires integration investment upfront |
Fragmented payment systems cause duplicated workflows and reporting gaps across omnichannel retail. An orchestration platform solves this by sitting above your individual PSPs and providing a single routing, reporting, and risk management layer. You define routing rules: send high-value transactions to the processor with the lowest interchange rate, route international orders through a processor with strong FX support, and fall back to a secondary processor if the primary is unavailable.
Payment orchestration also handles compliance routing. Certain payment methods, such as Alipay or WeChat Pay, require specific processor relationships. An orchestration layer manages those relationships without requiring your development team to build and maintain separate integrations for each one.
Pro Tip: When evaluating an orchestration platform, ask specifically about its omnichannel payment capabilities across POS, eCommerce, and call center channels. A platform that only covers online transactions will leave your in-store split-tender workflows unmanaged.
Sensepass operates as exactly this kind of orchestration layer. It connects to NetSuite, SuiteCommerce, Oracle Xstore, Aptos, Shopify POS, BigCommerce, Storis, NCR, Dynamics365, and more. On the payment method side, it supports digital wallets including PayPal, Venmo, WeChat, Apple Pay, Google Pay, Alipay, and Amazon Pay, plus BNPL options like Klarna, Sezzle, ZIP, Splitit, and Afterpay, financing through WeGetFinancing and Affirm, crypto via BitPay and Coinbase, and bank payments through Trustly and LinkMoney. Sensepass is also processor-agnostic, giving you access to 50+ card processors so you can optimize for cost and reliability without being locked into a single provider.
How to track multiple payment types across channels
Tracking mixed payment transactions accurately requires more than a good reporting dashboard. It requires a unified event model where every payment action, authorization, capture, settlement, refund, and chargeback, carries a consistent set of identifiers and timestamps regardless of which channel or provider generated it.
Follow these steps to build that tracking foundation:
- Assign a universal transaction ID at order creation. This ID must persist through every payment event, across your POS, eCommerce platform, and back-office ERP. It is the thread that connects all payment legs to a single order.
- Capture timestamps at each payment event. Authorization time, capture time, and settlement time are different events. Recording all three lets you identify delays, expired authorizations, and settlement timing mismatches.
- Synchronize reporting from all payment sources. Pull settlement data from your card processors, digital wallet providers, BNPL platforms, and bank transfer services into a single reporting layer. Tools like NetSuite’s payment reconciliation module or a dedicated orchestration platform like Sensepass handle this aggregation automatically.
- Tag transactions by channel. Every payment event should carry a channel tag: in-store POS, online checkout, mobile app, or call center. This lets you analyze payment method preferences by channel and identify where split-tender transactions are most common.
- Monitor FX variance for cross-border transactions. If you accept payments in multiple currencies, the exchange rate at authorization and the rate at settlement will differ. Record both rates and calculate the variance at the transaction level, not just at the monthly summary level.
Multi-channel visibility directly reduces cash flow errors. When you can see in real time that a BNPL installment from Afterpay has not settled on schedule, or that a batch from a card processor is missing three transactions, you can act before the discrepancy compounds. Retailers who rely on payment integration across channels report faster month-end close cycles and fewer manual adjustments because the data is clean at the source.
Key takeaways
Managing mixed payments requires sequential processing discipline, a normalization layer for reconciliation, and an orchestration platform that unifies all payment methods and channels into a single, auditable system.
| Point | Details |
|---|---|
| Lock orders before split-tender capture | Never modify items or prices after the first payment leg is authorized to prevent POS errors. |
| Normalize all PSP transaction IDs | Map every provider’s ID to a canonical internal ID to make reconciliation scalable and accurate. |
| Split refunds match original tenders | Refunds on mixed payments must be distributed across the original payment methods and recorded separately. |
| Orchestration replaces manual reconciliation | An orchestration platform routes, reports, and reconciles across all PSPs and channels automatically. |
| Tag every transaction by channel and timestamp | Consistent event identifiers and timestamps are the foundation of accurate multi-channel payment tracking. |
Why most businesses underestimate mixed payment complexity
I have worked with enough retail and eCommerce operators to know that split-tender payments are almost always treated as an edge case until they are not. A business adds a gift card program, or starts accepting Klarna, or opens a second sales channel, and suddenly the reconciliation process that worked fine for straight card transactions starts producing errors every week.
The part that surprises most financial managers is how much of the complexity lives in the refund and chargeback layer, not the original transaction. Processing a split-tender sale is manageable. Reversing one, especially when the original payment legs settled in different batch cycles, is where systems and processes break down. I have seen businesses carry reconciliation discrepancies for months because no one realized that their ERP was posting split refunds to a single GL account instead of distributing them across the original tender types.
The other underestimated factor is staff training. The best orchestration platform in the world does not help if a cashier manually splits an order into two transactions to avoid using the split-tender function. Operational discipline and system capability have to move together.
My honest advice: do not wait until your payment method mix forces a reconciliation crisis. Invest in an orchestration layer before you need it, configure your canonical ID system from day one, and treat payment gateway selection as a strategic decision rather than a technical afterthought. The businesses that handle diverse payment methods well are the ones that built the infrastructure before the volume arrived.
— Vlad
Manage all your payment methods with Sensepass
If you are running a retail or eCommerce operation with more than one payment method, you need more than a payment gateway. You need an orchestration layer that connects every channel and every provider into one system.

Sensepass integrates with NetSuite, SuiteCommerce, Oracle Xstore, Aptos, Shopify POS, BigCommerce, Storis, NCR, and Dynamics365. It supports digital wallets (PayPal, Apple Pay, Google Pay, Venmo, WeChat, Alipay, Amazon Pay), BNPL (Klarna, Sezzle, ZIP, Splitit, Afterpay), financing (WeGetFinancing, Affirm), crypto (BitPay, Coinbase), and bank payments (Trustly, LinkMoney). With access to 50+ card processors, Sensepass gives you the flexibility to optimize routing by cost, speed, and reliability. Explore the complete omnichannel payments guide to see how Sensepass brings it all together.
FAQ
What is a split-tender payment?
A split-tender payment is a single transaction paid using two or more payment methods, such as a gift card combined with a credit card. The total order amount is divided across the payment legs, and each leg is processed and settled separately.
Why does order modification cause errors in mixed payment processing?
Changing items or prices after the first payment leg is authorized creates a mismatch between the authorized amount and the new order total. Oracle NetSuite’s POS guidance confirms that sequential tender capture requires a locked order to prevent these failures.
How do refunds work on split-tender transactions?
Refunds on split-tender orders must be distributed across the original payment methods in proportion to the original split. A $100 return on a $25 cash and $75 card payment requires two separate refund records, and the original payment card must be present for card refunds.
What is a canonical transaction ID and why does it matter?
A canonical transaction ID is a single internal identifier assigned to an order that links all payment legs, regardless of which PSP processed each one. Without it, multi-PSP reconciliation fails because each provider uses a different ID format that cannot be joined directly.
When should a retailer invest in a payment orchestration platform?
A retailer should invest in orchestration when they accept more than two payment methods, operate across more than one sales channel, or process enough volume that manual reconciliation produces regular errors. Orchestration platforms like Sensepass unify routing, reporting, and reconciliation across all providers from a single integration point.
Recommended
- Payment Gateway Selection Tips for Retail Success – Omnichannel payments at the Point Of Sale | Sensepass
- Payment Gateway Selection Tips for Retail Success – Omnichannel payments at the Point Of Sale | Sensepass
- Credit Card Payment Solutions That Transform Retail – Omnichannel payments at the Point Of Sale | Sensepass
- 7 Types of Retail Payment Methods for Your Business – Omnichannel payments at the Point Of Sale | Sensepass

 New York Office
260 Madison Ave Suite 8018 New York NY 10016

