
How to Maximize Payment Conversion Rates in 2026
July 10, 2026
TL;DR:
- Optimizing checkouts by fixing cost transparency and soft decline recovery can significantly increase payment success rates.
- Offering multiple local and digital payment options and embedding trust signals reduce friction and abandonment during the payment process.
Payment conversion rate is defined as the percentage of initiated checkouts that result in a completed, successful payment. For ecommerce managers and retail operators, this single metric determines how much revenue your traffic actually generates. Cart abandonment sits at 72.1% across ecommerce, with 47% of shoppers leaving due to unexpected costs and 31% citing trust and security concerns. Knowing how to maximize payment conversion rates means fixing the specific friction points that cause those exits, not adding more marketing spend to drive traffic into a leaky funnel.
How to maximize payment conversion rates: prerequisites and tools
Checkout optimization is the highest ROI opportunity available to most retailers. It generates more revenue from existing traffic without increasing ad budgets. Before applying any tactics, you need the right measurement and infrastructure in place.
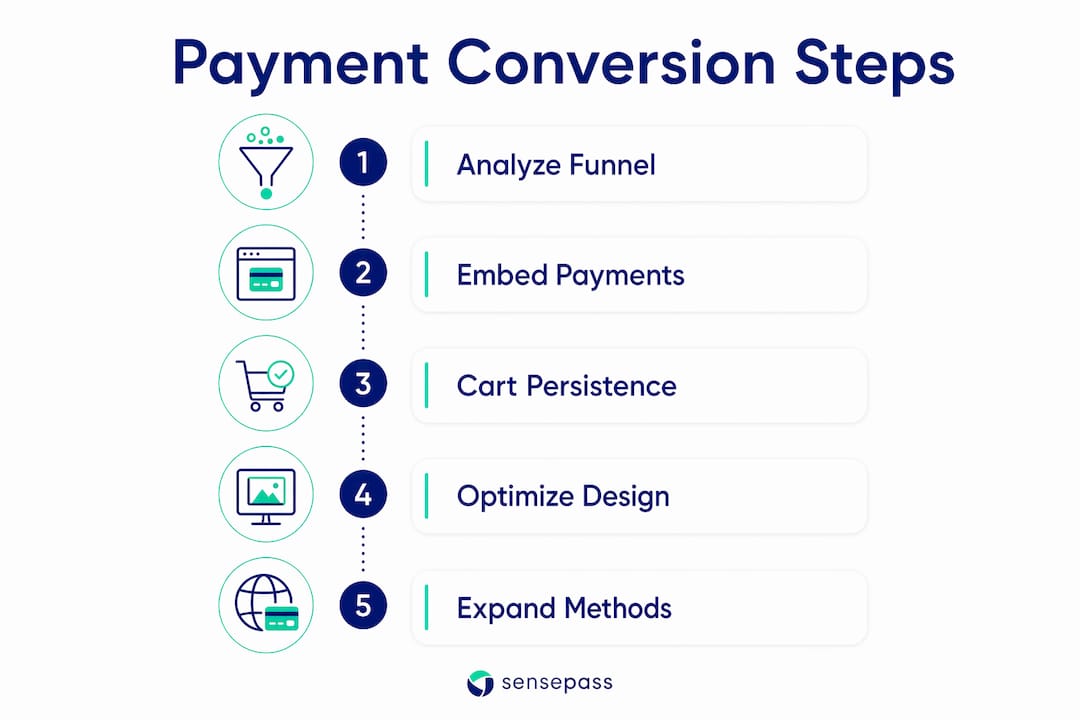
The three non-negotiable prerequisites are granular funnel analytics, embedded payment components, and cart persistence.
Granular funnel analytics means tracking drop-off by device type, payment method, and traffic source separately. A 15% abandonment rate on desktop and a 45% rate on mobile are two different problems requiring different fixes. Without this breakdown, you are solving the wrong problem.
Embedded payment elements keep customers on your domain throughout the entire checkout. Redirecting shoppers to a third-party payment page introduces a context switch that erodes trust and increases drop-off. Native payment UI components embedded within the merchant domain also reduce PCI compliance scope, which simplifies your security posture.
Cart persistence and session management allow returning visitors to resume a checkout they started earlier. Without this, a shopper who gets interrupted starts over and often does not finish.
| Tool or feature | Purpose |
|---|---|
| Funnel analytics by device and method | Identify where and why shoppers exit |
| Embedded payment UI | Reduce context switches and trust erosion |
| Cart and session persistence | Recover interrupted checkouts automatically |
| A/B testing platform | Validate design and copy changes with real data |
| Authorization success dashboard | Track approval rates by processor and card type |
Pro Tip: Set up a dedicated dashboard that tracks authorization success rate alongside cart abandonment. Most teams watch abandonment but ignore how many attempted payments simply fail at the processor level.
How can optimizing checkout design improve payment conversion rates?
Checkout design is where most conversion gains live. The fixes are structural, not cosmetic. Changing button colors or adding trust badges produces minimal lift compared to fixing cost disclosure and form length.
Showing all costs early eliminates the number one abandonment trigger, which accounts for 48% of exits. Shipping fees, taxes, and any service charges must appear before the customer reaches the payment step. Surprises at the final screen are the fastest way to lose a sale you already earned.
Guest checkout removes the registration barrier that stops a significant share of first-time buyers. Requiring account creation before payment is a conversion killer, particularly on mobile where typing is slower and patience is shorter.
Form length directly affects completion rates. One-page checkout reduces abandonment by 20% on mobile, and cutting form fields from 14–16 down to 7–8 fields measurably speeds up the process. Address autocomplete further reduces typing effort and error rates.
Trust signals matter most when placed near the payment fields themselves, not in the site header. SSL badges, recognizable payment method logos, and a clearly visible return policy at the point of payment address the 31% of shoppers who abandon due to security concerns.
- Show total cost including shipping and tax before the payment step
- Enable guest checkout with optional post-purchase account creation
- Reduce form fields to 7–8 and add address autocomplete
- Use one-page or minimal-step checkout on mobile
- Display SSL badges and payment logos adjacent to payment fields
- State the return policy in one clear sentence near the “Pay” button
- Prioritize page load speed, especially on mobile networks
Pro Tip: Test your checkout on a mid-range Android device on a 4G connection. That experience reflects the majority of your mobile shoppers, not the fast iPhone on Wi-Fi you use internally.
What payment methods and configurations maximize payment conversions?
Payment method selection is one of the most direct levers for improving checkout success. Offering three or more payment methods increases checkout conversion by 5–12% over card-only checkout. Enabling mobile wallets like Apple Pay and Google Pay can lift conversion by up to 22% by reducing the number of steps required to complete a purchase.
Digital wallets accounted for 49–56% of global ecommerce transaction value in 2025, and over 65% of US adults use them regularly. That share makes wallet support a baseline requirement, not a differentiator. Place mobile wallet buttons above the fold on mobile checkout pages so shoppers see them before they see a card form.
Buy Now Pay Later (BNPL) options reduce abandonment on higher-value orders by spreading the cost. Shoppers who hesitate at a $300 purchase often complete it when Klarna, Afterpay, or Sezzle is available. BNPL is particularly effective for apparel, electronics, and home goods categories.
Regional payment method matching is a frequently missed opportunity. Payment mismatch causes 5–10% abandonment when shoppers cannot find their preferred local method even when cards are accepted. Shoppers in the Netherlands expect iDEAL. Shoppers in Brazil expect Boleto. Offering only Visa and Mastercard to an international audience leaves real revenue on the table.
The right number of payment options is 3–5, curated for your specific audience. Displaying 12 payment logos creates choice paralysis and slows decision-making. More options do not always mean more conversions. The goal is to match your audience’s actual preferences, not to cover every possible method.
Pro Tip: Check your analytics for the top three countries driving your traffic, then verify that your checkout offers at least one preferred local payment method for each. This single audit often reveals an immediate fix.
How to manage and recover from payment declines to improve conversion
Payment declines are a hidden revenue drain that most ecommerce teams underestimate. Approximately 5% of legitimate orders are incorrectly declined as fraud. That is lost revenue from customers who wanted to buy and had the funds to do so.
The first step is distinguishing hard declines from soft declines. A hard decline means the card issuer permanently rejected the transaction, typically due to a stolen card or closed account. A soft decline is a temporary issue: insufficient funds at that moment, a bank timeout, or a fraud filter that can be cleared. Soft declines account for 40–60% of all declined transactions. That share represents a recoverable opportunity most merchants ignore.
- Identify soft decline codes from your processor response data and tag them separately from hard declines in your analytics.
- Build automated retry flows that attempt the transaction again after a short delay, or prompt the customer to try a different card or payment method.
- Tune merchant-defined fraud rules to your actual customer profile. Merchant-defined fraud rules calibrated to your business context reduce false declines without weakening security.
- Use card updater services to automatically refresh stored card details for returning customers, preventing declines caused by expired cards.
- Implement multi-gateway intelligent routing to send transactions through the processor with the highest approval rate for a given card type or region.
- Write clear error messages that tell the customer what happened and what to do next. “Payment declined” is not helpful. “Your card was declined. Please try a different card or use Apple Pay” is.
Pro Tip: Soft decline recovery is the most neglected revenue opportunity in ecommerce payments. A single automated retry flow for soft declines can recover a meaningful share of transactions that would otherwise be counted as lost.
How do trust and transparency affect payment conversion?
Trust is not a feeling. It is a set of specific signals that customers look for at the exact moment they decide whether to enter their card number. Getting those signals right at the payment step is more effective than building brand trust through content or social media.
Transparent pricing throughout the checkout process addresses the core abandonment trigger. Customers who see the final total before the payment screen are far less likely to exit. Structural fixes like upfront cost disclosure consistently outperform trust badges and pop-ups in conversion impact.
These trust signals produce the most consistent results at checkout:
- Display verified payment logos (Visa, Mastercard, PayPal, Apple Pay) directly adjacent to the payment form
- Show a security badge from a recognized provider near the “Pay” button
- State the return and refund policy in plain language, not a link to a long page
- Include customer review counts or satisfaction ratings on the checkout page
- Offer live chat or a visible support contact during checkout for high-value orders
- Provide post-purchase account creation as an option, not a requirement, to maintain positive momentum after the sale
Social proof placed at checkout, such as “Trusted by 50,000 customers” or a star rating, addresses hesitation without adding friction. The goal is to reduce the perceived risk of completing the transaction.
Key takeaways
Maximizing payment conversion rates requires fixing cost transparency, simplifying checkout flows, expanding payment method coverage, and recovering soft declines systematically.
| Point | Details |
|---|---|
| Show all costs early | Disclose shipping, taxes, and fees before the payment step to eliminate the top abandonment trigger. |
| Offer 3–5 curated payment methods | Include mobile wallets and BNPL to cover the majority of shopper preferences without creating choice paralysis. |
| Recover soft declines | Automate retry flows for soft declines, which represent 40–60% of all failed transactions. |
| Embed payment UI on your domain | Keep shoppers on your site throughout checkout to reduce trust erosion and drop-off. |
| Track authorization success | Monitor approval rates by processor and card type as a core payment performance KPI. |
What I’ve learned about payment conversion that most guides skip
I’ve worked with enough retail and ecommerce operations to know that most teams spend their optimization budget on the wrong things. They redesign the checkout page, add a new trust badge, and wonder why conversion barely moves. The real gains are almost always in the engineering layer, not the visual layer.
The two fixes that consistently produce the largest results are upfront cost disclosure and soft decline recovery. Both are unglamorous. Neither shows up in a design sprint. But abandoned cart recovery through email sequences and retry flows generates returns that no UI refresh can match.
Payment method diversity is the other area where I see consistent underinvestment. Retailers add Apple Pay and call it done. But if 20% of your traffic comes from markets where a local bank transfer or BNPL option is the default, you are leaving that revenue on the table every day. The multi-method checkout setup conversation should happen at the infrastructure level, not as an afterthought.
My honest advice: run a soft decline audit before you touch your checkout design. Pull your processor decline codes, separate hard from soft, and calculate what a 50% recovery rate on soft declines would mean in monthly revenue. That number usually reorders every other priority on the roadmap.
— Vlad
How Sensepass helps retailers boost checkout success
Sensepass is an omnichannel payment orchestration layer built for retailers who need both breadth of payment method support and flexibility in how they process transactions.

Sensepass integrates with major retail platforms including NetSuite, SuiteCommerce, Oracle Xstore, Aptos, Shopify POS, BigCommerce, Storis, NCR, and Dynamics365. On the payment method side, Sensepass supports digital wallets (PayPal, Venmo, WeChat, Apple Pay, Google Pay, Alipay, Amazon Pay), BNPL options (Klarna, Sezzle, ZIP, Splitit, Afterpay), financing through WeGetFinancing and Affirm, crypto payments via BitPay and Coinbase, and pay-by-bank through Trustly and LinkMoney. Sensepass is processor-agnostic, giving merchants access to 50+ card processors for maximum authorization flexibility. For retailers ready to put these payment optimization strategies into practice, the omnichannel payments guide covers how to configure the full payment stack across every channel.
FAQ
What is a good payment conversion rate for ecommerce?
A strong payment conversion rate varies by industry, but the goal is to minimize the 72.1% average cart abandonment rate. Tracking authorization success rate alongside checkout completion gives a more complete picture of payment performance.
How does offering more payment methods increase conversions?
Offering three or more payment methods increases checkout conversion by 5–12%, and enabling mobile wallets like Apple Pay and Google Pay can lift conversion by up to 22% by reducing checkout steps.
What causes the most payment drop-off at checkout?
Unexpected costs at checkout cause 48% of abandonment. Showing all fees, shipping, and taxes before the payment step is the single most effective fix for reducing drop-off.
What is a soft decline and why does it matter?
A soft decline is a temporary payment rejection caused by issues like a bank timeout or a fraud filter, not a permanent card problem. Soft declines account for 40–60% of all failed transactions and are recoverable with automated retry flows.
How can I reduce false fraud declines?
Merchant-defined fraud rules calibrated to your actual customer profile reduce false declines without weakening security. Approximately 5% of legitimate orders are incorrectly declined as fraud, representing direct lost revenue.
Recommended
- Mobile Payment Trends 2025: What Retailers Must Know – Omnichannel payments at the Point Of Sale | Sensepass
- Mobile Payment Trends 2026: What Retailers Must Know – Omnichannel payments at the Point Of Sale | Sensepass
- Mastering the Omnichannel Payment Workflow Guide – Omnichannel payments at the Point Of Sale | Sensepass
- Payment Methods Not Available with SuitePayments (and How to Add Them)

 New York Office
260 Madison Ave Suite 8018 New York NY 10016

