
How to Offer Buy Now Pay Later: 2026 Retail Guide
June 15, 2026
TL;DR:
- Offering buy now pay later increases average order value and conversion rates when integrated correctly. Key steps include choosing the right provider, implementing technical setup, displaying messaging early, and managing post-purchase workflows carefully. Proper execution maximizes revenue, protects margins, and enhances the customer shopping experience.
Buy now pay later (BNPL) is a point-of-sale financing method that lets customers split purchases into installments, typically interest-free, while merchants receive the full payment upfront minus provider fees. Retailers who know how to offer buy now pay later correctly see average order value rise 20%–30% and conversion rates climb by roughly 20%. Leading providers in this space include Klarna, Afterpay, Affirm, and PayPal Pay Later. The fees run 3%–6% per transaction, higher than standard card rates of 2.5%–3%, but the sales volume increase consistently offsets that cost. This guide walks you through every step: provider selection, technical integration, on-site messaging, and post-purchase workflow management.
How to offer buy now pay later: prerequisites and setup
Before you write a single line of integration code, you need three things in place: a verified merchant account with your chosen BNPL provider, a compatible eCommerce platform, and a clear understanding of your order thresholds.
Choose the right BNPL provider for your business
Provider selection depends on your average order value, product category, and customer geography. Klarna and Afterpay dominate North American and European markets. Affirm performs well for higher-ticket items like furniture and electronics. Sezzle targets younger, credit-thin shoppers in the U.S. and Canada. ZIP covers Australia and the U.S. with a broad demographic reach.
Consider these factors when evaluating providers:
- Minimum order thresholds: Most providers set minimums between $75 and $100. Hiding BNPL below $50–$75 orders protects your margins on low-value carts.
- Fee structures: Rates range from 3%–6% depending on provider and volume. Negotiate rates once your monthly BNPL volume exceeds $50,000.
- Geographic coverage: Afterpay and Klarna cover the widest range of countries. Affirm is U.S.-focused.
- Product eligibility: Exclude consumables and low-margin SKUs from BNPL eligibility to protect profitability while capturing conversion lift on higher-margin items.
- Platform compatibility: Confirm your cart supports the provider’s official plugin or API before signing a merchant agreement.
Platform compatibility at a glance
| Platform | Native BNPL Support | Recommended Providers |
|---|---|---|
| Shopify | Yes (Shop Pay Installments) | Klarna, Afterpay, Affirm |
| WooCommerce | Via plugin | Klarna, Afterpay, Sezzle |
| Magento / Adobe Commerce | Via plugin or API | Klarna, Afterpay, ZIP |
| BigCommerce | Via app marketplace | Afterpay, Sezzle, Affirm |
| Custom cart | API integration required | Any provider with REST API |
Pro Tip: Apply for merchant accounts with two providers simultaneously. Approval timelines vary from 24 hours to two weeks. Having a backup prevents launch delays.
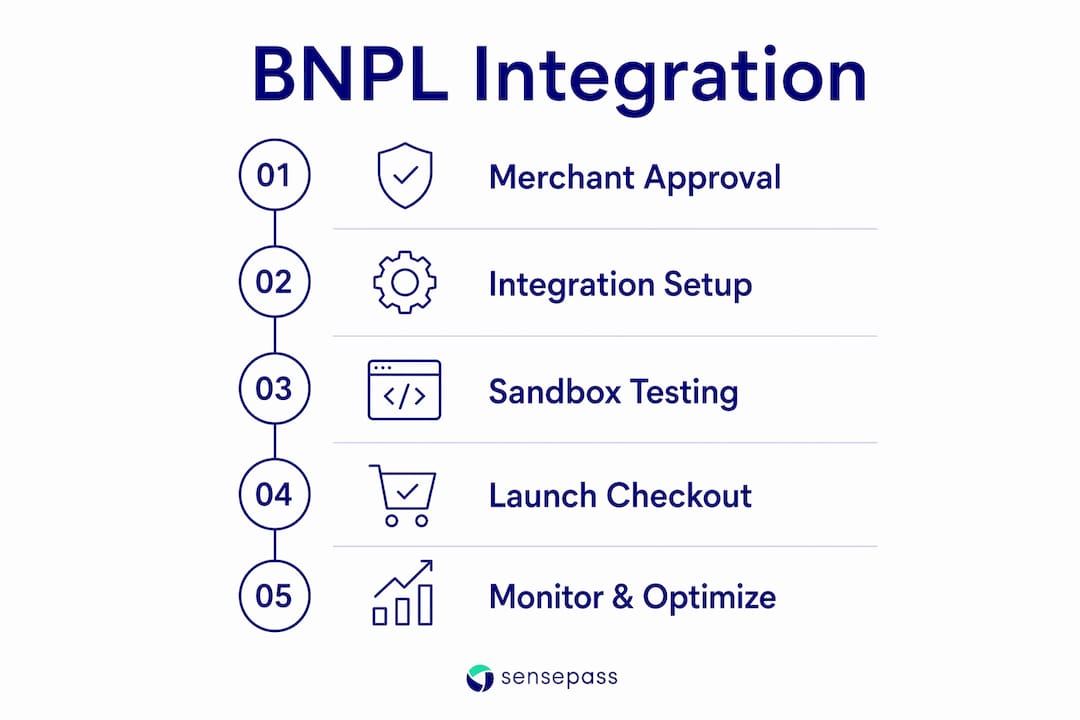
What are the steps to integrate BNPL into your checkout?
Technical integration follows a predictable sequence regardless of which provider you choose. The steps below apply to both plugin-based setups and direct API implementations.
-
Apply and complete merchant verification. Submit your business registration, bank account details, and website URL. Klarna and Afterpay typically approve within 48–72 hours for established businesses.
-
Install the provider plugin or SDK. Shopify merchants use Shop Pay Installments or the official Klarna and Afterpay apps from the Shopify App Store. WooCommerce and Magento merchants install provider-supplied plugins from their respective marketplaces. Custom carts require direct REST API integration using the provider’s developer documentation.
-
Add BNPL as a payment option at checkout. Place BNPL alongside credit cards, digital wallets like Apple Pay and Google Pay, and other payment methods. Never bury it below gift card fields or secondary options.
-
Implement conditional display logic. Configure your cart to show BNPL only when the order value meets the provider’s minimum threshold. Most provider dashboards and platform plugins include a threshold setting you can configure without custom code.
-
Separate authorization from capture. This step is critical. Capturing funds before shipment violates provider agreements and consumer protection laws. Set your payment capture to trigger only after goods ship, not at the moment of order placement.
-
Test on desktop and mobile. Run end-to-end test transactions covering approval, decline, partial approval, and refund scenarios. Verify that installment amounts calculate correctly across device types. Mobile checkout accounts for the majority of BNPL transactions, so mobile testing is non-negotiable.
Pro Tip: Use a staging environment with provider sandbox credentials before pushing to production. Klarna, Afterpay, and Affirm all provide sandbox API keys specifically for pre-launch testing.
For retailers connecting BNPL to physical stores, review how to add alternative payment methods to Shopify POS to cover both online and in-store channels from a single integration.
How do you display BNPL to maximize customer adoption?
Over 60% of U.S. online shoppers expect BNPL at checkout. That expectation does not start at checkout. It starts on the product page. Retailers who surface installment messaging early in the buyer journey convert at significantly higher rates than those who reveal BNPL only at the payment step.
Here is where and how to display BNPL messaging effectively:
- Product pages: Embed a JavaScript widget from your BNPL provider directly below the price. Klarna, Affirm, and Afterpay all provide real-time installment calculators that update dynamically as customers select product variants. A customer seeing “$37.50/month” next to a $150 item makes a different purchase decision than one seeing only “$150.”
- Shopping cart page: Add a BNPL reminder banner above the checkout button. This reinforces the option at the moment of highest purchase intent.
- Checkout page: Display BNPL as a first-class payment method, visually equal to Visa, Mastercard, and PayPal. Provider logos carry trust signals that reduce hesitation.
- Homepage and category pages: Use promotional banners during high-traffic periods like Black Friday or back-to-school season to drive awareness before shoppers reach a product page.
BNPL options buried below gift cards convert at roughly one-third the rate of options displayed alongside credit cards. That placement difference alone can represent a significant revenue gap over a full fiscal year.
Pro Tip: Run an A/B test on your product page with and without the BNPL installment widget for 30 days. The conversion data will justify the integration cost to any skeptical stakeholder.
To see how leading retailers handle BNPL visibility in physical and digital channels, the Afterpay retail implementation guide covers practical display strategies worth reviewing.
How do you manage BNPL workflows after purchase?
Post-purchase management is where most BNPL implementations break down. The technical integration works, but the operational workflow around fulfillment, refunds, and reconciliation creates problems if not planned carefully.
The core principle is this: BNPL providers assume the credit risk and handle customer approval entirely. You receive the full order amount, minus fees, after a settlement window of 1–5 business days. That arrangement protects you from default risk, but it creates specific obligations on your side.
Critical workflow rules to follow:
- Capture only after shipment. Authorize at order placement, capture at fulfillment. Premature capture violates provider agreements and triggers compliance issues.
- Handle partial shipments with partial captures. If an order ships in two packages, capture the value of the first shipment, then capture the remainder when the second ships. Release any unused authorization lines promptly to avoid reconciliation errors.
- Process refunds through your order management system. Your system sends the refund signal to the BNPL provider, which then cancels or adjusts the customer’s installment schedule. Refund windows typically run 120–180 days post-purchase, giving you flexibility for returns.
- Automate capture and release events. Manual capture workflows create reconciliation gaps. Connect your fulfillment system directly to your payment gateway so capture events trigger automatically at the shipping label stage.
- Monitor settlement reports weekly. Cross-reference BNPL settlements against your order management system to catch discrepancies early.
“Automation of partial captures and final releases of authorization lines is essential to avoid reconciliation errors and improve finance team workflows with BNPL.” — BNPL Checkout Best Practices
For a broader look at building a clean payment workflow, the retail payment workflow guide covers the full order-to-settlement lifecycle in practical terms.
Key takeaways
Offering BNPL successfully requires the right provider, a clean technical integration, early on-site messaging, and disciplined post-purchase workflow management to protect margins and maximize conversion lift.
| Point | Details |
|---|---|
| Provider selection matters | Match providers like Klarna, Afterpay, or Affirm to your order values, product margins, and customer geography. |
| Set order thresholds | Hide BNPL on carts below $50–$75 to avoid paying provider fees on orders that do not benefit from conversion lift. |
| Display early and prominently | Place installment widgets on product pages and cart pages, not only at checkout, to capture buyers earlier in the journey. |
| Capture after shipment | Never capture BNPL funds at order placement. Capture triggers at fulfillment to comply with provider rules and consumer protection law. |
| Automate post-purchase events | Connect fulfillment systems to your payment gateway so partial captures and authorization releases happen without manual intervention. |
Why most retailers get BNPL wrong on the first try
I have worked with enough retail and eCommerce teams to recognize a consistent pattern. The integration itself goes smoothly. The provider is live at checkout. The team celebrates. Then three months later, the BNPL adoption rate is 4% and nobody can explain why.
The problem is almost never technical. It is visibility and timing. Retailers treat BNPL as a payment method, when it is actually a merchandising tool. The moment you start showing “$37/month” on the product page instead of waiting for the customer to reach checkout, your numbers change. I have seen adoption rates double from that single change alone.
The second mistake is offering BNPL on every product regardless of margin. Strategically excluding low-margin or consumable products from BNPL eligibility preserves profitability while still capturing conversion lift on higher-margin items. Not every SKU deserves a BNPL callout. Be selective.
Staff training matters more than most merchants expect. When a customer calls about their installment schedule or a refund affecting their payment plan, your support team needs to understand the basics of how the provider handles those situations. A confused support agent erodes the trust that BNPL is supposed to build.
Finally, track your BNPL adoption rate, average order value for BNPL orders versus non-BNPL orders, and the fee cost as a percentage of BNPL revenue monthly. Those three numbers tell you whether your implementation is working or just sitting there.
— Vlad
Add BNPL to your omnichannel payment stack with Sensepass
If you are ready to implement BNPL across your retail and eCommerce channels, Sensepass makes the integration straightforward.
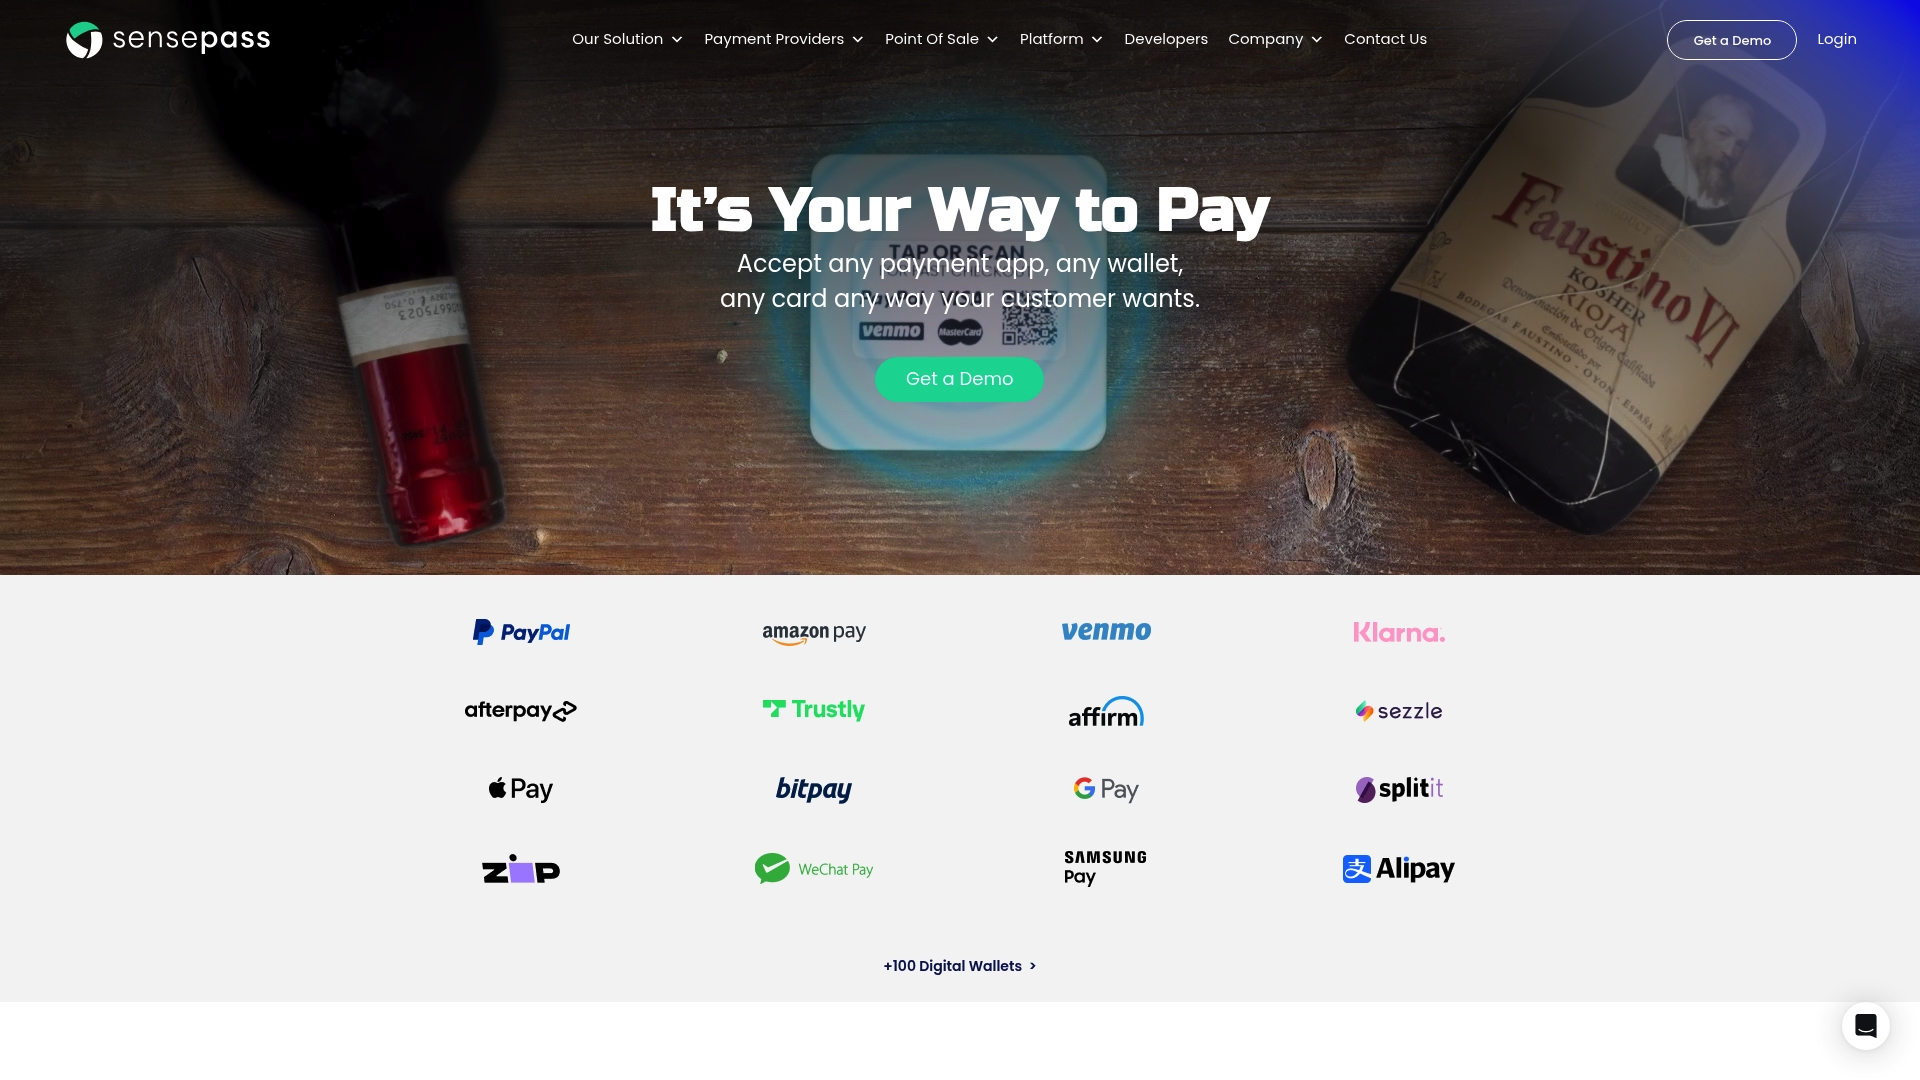
Sensepass is a processor-agnostic payment orchestration layer that connects your existing platforms to a full range of payment methods without replacing your current infrastructure. It integrates with NetSuite, SuiteCommerce, Oracle Xstore, Aptos, Shopify POS, BigCommerce, Storis, NCR, Dynamics365, and more. For BNPL specifically, Sensepass supports Klarna, Sezzle, ZIP, Splitit, and Afterpay alongside financing options like WeGetFinancing and Affirm. Beyond BNPL, you get digital wallets including PayPal, Venmo, Apple Pay, Google Pay, Alipay, WeChat, and Amazon Pay, plus crypto payments via BitPay and Coinbase, and pay-by-bank options through Trustly and LinkMoney. With 50+ card processors available, you choose the processing relationship that fits your cost structure. Explore the full omnichannel payments guide to see how Sensepass fits your payment stack.
FAQ
What is buy now pay later for merchants?
BNPL is a financing option where customers pay in installments and merchants receive the full order amount upfront, minus a provider fee of 3%–6%. The BNPL provider assumes all credit and default risk on behalf of the merchant.
How long does BNPL integration take?
Most plugin-based integrations on Shopify or WooCommerce take one to three days from merchant account approval to live checkout. Custom API integrations typically require one to two weeks of development and testing time.
Which BNPL provider should i choose?
Choose based on your average order value, customer geography, and product category. Klarna and Afterpay cover the broadest markets. Affirm works well for high-ticket items. Sezzle targets younger shoppers in the U.S. and Canada.
Does offering BNPL hurt my margins?
BNPL fees of 3%–6% are higher than standard card fees, but the 20%–30% increase in average order value typically offsets the cost. Protect margins by excluding low-margin products and setting minimum cart thresholds of $75–$100.
How do BNPL refunds work for merchants?
You process the refund through your order management system, which signals the BNPL provider to cancel or adjust the customer’s installment plan. Most providers allow refunds within 120–180 days of the original purchase date.
Recommended
- How To Connect Alternative Payment Methods to Shopify POS
- 7 Types of Retail Payment Methods for Your Business – Omnichannel payments at the Point Of Sale | Sensepass
- 7 Key Examples of Contactless Payments for Retailers – Omnichannel payments at the Point Of Sale | Sensepass
- Your Guide to Flexible Payment Options in Retail – Omnichannel payments at the Point Of Sale | Sensepass

 New York Office
260 Madison Ave Suite 8018 New York NY 10016

