
How to Reduce Payment Processing Costs: Retail Guide
April 18, 2026
TL;DR:
- Payment processing fees include non-negotiable interchange and assessments and a negotiable processor markup.
- Choosing in-person and lower-cost payment methods, plus optimizing transaction data, reduces overall costs.
- Seamless omnichannel payment experiences improve conversions and long-term margins more than rate discounts alone.
Payment processing fees quietly eat into retail margins every single day. For many store owners and eCommerce managers, these costs sit somewhere between 2.5% and 3.5% of every transaction, and they add up fast across thousands of monthly sales. Most retailers accept these fees as fixed costs when, in reality, a significant portion is negotiable or avoidable. This guide walks you through the exact steps to understand your fee structure, choose smarter payment methods, optimize each transaction, and negotiate better terms, all without reducing the payment options your customers expect.
Table of Contents
- Breaking down payment processing fees: What you need to know
- Choosing the right payment methods and platforms
- Tactics to minimize fees and optimize every transaction
- Negotiating and monitoring your processor markup and contract terms
- The overlooked key to reducing processing costs: Payment experience matters most
- Ready to cut your payment costs and boost your retail performance?
- Frequently asked questions
Key Takeaways
| Point | Details |
|---|---|
| Know your fees | Understanding each fee type is the first step toward smarter cost reduction. |
| Choose payment methods wisely | Opt for lower-cost payment types and integrate platforms that give flexibility and savings. |
| Optimize every transaction | Simple process changes like capturing more data and batching daily lower your rates. |
| Negotiate processor terms | Processor markups are often negotiable, and contract reviews can yield big savings. |
| Prioritize payment experience | The best savings come when seamless payment options also drive more sales. |
Breaking down payment processing fees: What you need to know
Before you can reduce your costs, you need to know exactly what you’re paying for. Most retailers see a single line item on their statement labeled “processing fees,” but that number is actually made up of three distinct components. Understanding each one is the foundation of any serious cost reduction effort.
The first component is interchange. This is the fee paid to the card-issuing bank every time a customer swipes, taps, or types in their card. Interchange is set by the card networks (Visa, Mastercard, etc.) and is largely non-negotiable. It averages between 1.5% and 2.6% per transaction, though rates vary based on card type, industry, and how the transaction is processed.
The second component is assessments. These are fees charged by the card networks themselves for using their infrastructure. They typically run between 0.1% and 0.2% and are also non-negotiable. The third component is the processor markup, which is what your payment processor charges on top of interchange and assessments. This portion, which typically ranges from 0.2% to 0.5% plus $0.10 per transaction, is where your negotiating power lives.
Here’s a quick breakdown of the three fee types:
| Fee component | Who charges it | Typical range | Negotiable? |
|---|---|---|---|
| Interchange | Card-issuing bank | 1.5% to 2.6% | No |
| Assessments | Card network | 0.1% to 0.2% | No |
| Processor markup | Your processor | 0.2% to 0.5% + $0.10 | Yes |
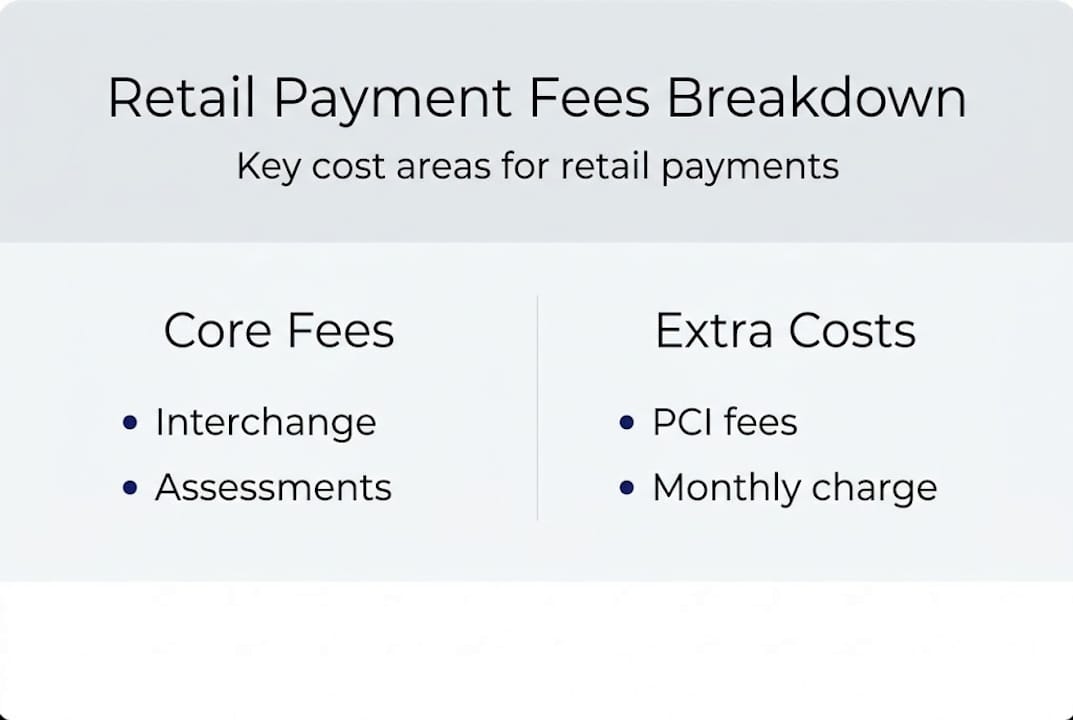
Beyond these core fees, retailers often get hit by hidden charges. Common culprits include PCI compliance fees, monthly minimum fees, batch processing fees, and chargeback fees. A solid payment fees breakdown review of your monthly statement can reveal charges you’ve been paying without realizing it.
Omnichannel retailers face added complexity because types of retail payments vary widely across in-store, online, and mobile channels, and each channel carries different fee structures. To stay ahead, familiarize yourself with the must-have payment features that keep your processing lean without limiting customer choice.
Choosing the right payment methods and platforms
Now that you know which fees to target, selecting the right payment methods and platforms is your next step. Not all payment types cost the same. The way a transaction is processed has a direct impact on how much you pay.
In-person and EMV chip or debit transactions are consistently cheaper than card-not-present (CNP) transactions, which include most eCommerce purchases. This is because in-person transactions carry lower fraud risk, which card networks reward with reduced interchange rates. Here’s how common payment methods compare:
| Payment method | Typical fee range | Customer preference | Integration complexity |
|---|---|---|---|
| EMV chip (in-store) | 1.5% to 2.2% | High | Low |
| Contactless/NFC | 1.6% to 2.3% | Very high | Low |
| Debit (PIN) | 0.05% + $0.21 (regulated) | High | Low |
| eCommerce/CNP | 2.2% to 3.5% | High | Medium |
| Digital wallets | 1.8% to 2.5% | Growing fast | Medium |
| BNPL | Varies by provider | Growing | Medium to high |
Your platform integration strategy also shapes your costs. Retailers using disconnected systems for in-store and online often pay more because of data mismatches and increased manual processing. When you automate financial transactions across channels, you reduce errors that trigger costly downgrades.
For gateway selection tips, prioritize solutions that give you flexibility without locking you into a single processor. Exploring omnichannel solutions that unify POS, eCommerce, and mobile into one payment layer often yields better negotiated rates because of consolidated volume. Understanding processor differences will also help you spot where you’re overpaying.
Pro Tip: If you process both in-store and online, bundling them under a single payment platform can qualify you for blended volume pricing, which is often 10% to 20% lower than managing two separate processor relationships.
Tactics to minimize fees and optimize every transaction
With the right payment mix in place, you can unlock further savings through smart transaction-level execution. These tactics sound technical, but they translate directly into lower costs per transaction.
- Capture AVS and CVV data on every online transaction. Address Verification Service (AVS) and card verification value (CVV) data signals to the card networks that you’ve done due diligence, which can qualify you for lower interchange rates.
- Collect Level 2 and Level 3 data for B2B transactions. If you sell to businesses, capturing detailed purchase order and line-item data can reduce interchange by up to 0.5% per transaction.
- Batch your transactions daily. Always settle your daily transactions within 24 hours. Late batching pushes transactions into higher-cost downgrade tiers.
- Monitor and reduce chargebacks. Capturing complete transaction data, batching daily, and keeping chargebacks under 1% can lower interchange costs by 0.1% to 0.5%.
- Enable contactless payments. Tap-to-pay and NFC options at contactless payments channels reduce friction and processing errors.
Pro Tip: Use AI fraud monitoring tools to flag suspicious transactions before they become chargebacks. Keeping your chargeback ratio below 1% is not just good practice. It’s the threshold that qualifies you for the most favorable interchange tiers.
Important: Chargebacks don’t just cost you the transaction amount. They trigger additional fees, can damage your processor relationship, and in high-volume cases, risk account termination. Proactive fraud controls are not optional.
These processing best practices work together. Follow the payment optimization steps consistently and you’ll see measurable fee reductions within one to two billing cycles.
Negotiating and monitoring your processor markup and contract terms
Even with every tactic deployed, your contract terms can make or break your savings. The processor markup is the one fee component fully within your control, and most retailers never negotiate it.
Your processor markup is typically quoted as a percentage plus a per-transaction fee. The standard range is 0.2% to 0.5% plus $0.10 per transaction, but volume, business type, and processing history all affect what you can realistically achieve. Processors expect merchants to accept the first quote. Don’t.
Here’s your contract review action list:
- Request an interchange-plus pricing model. This is more transparent than flat-rate or tiered pricing because you see exactly what you’re paying in markup versus interchange.
- Identify all monthly and annual fees. Look for PCI compliance fees, gateway fees, minimum monthly charges, and statement fees. Each is negotiable.
- Ask for rate caps. Some processors include clauses that allow automatic rate increases. Push back and request fixed markup rates for the contract term.
- Benchmark against competitors. Get quotes from at least two other processors before your next contract renewal. Use those quotes as leverage.
- Review your statement monthly. Rates can creep up quietly. A monthly review catches changes early.
Watch out: Some processor contracts include “evergreen” clauses that auto-renew annually with little notice. Missing the cancellation window can lock you in for another year at rates you’ve already identified as too high. Mark your renewal dates now.
For deeper insight into financial processing systems and how contract structures affect long-term costs, it’s worth reviewing industry benchmarks. Applying established cost reduction strategies from financial management can also give you a framework for ongoing rate management and budget planning.
The goal is not to switch processors every year. It’s to create a relationship where you’re regularly reviewed, fairly priced, and not paying for services you don’t use. Visit cut payment costs for more detail on structuring these conversations.
The overlooked key to reducing processing costs: Payment experience matters most
Here’s the perspective shift most cost-focused retailers miss. Obsessing purely over your per-transaction rate is a short-sighted strategy. We’ve worked with retailers who squeezed their processor markup to the minimum but still watched margins erode because of high cart abandonment, excessive customer support calls about payment failures, and clunky checkout experiences that drove customers to competitors.
The retailers who win long-term are those who invest in seamless, omnichannel payment experiences. When checkout is fast, familiar, and flexible, customers complete purchases. That means offering Apple Pay, Google Pay, PayPal, Klarna, Afterpay, and even crypto options like BitPay where relevant. It means your in-store POS and online cart talk to each other. It means fewer failed transactions, fewer chargebacks, and lower operational costs from reduced support volume.
Cutting costs with omnichannel solutions is not just about rate negotiation. It’s about designing a payment experience that converts more customers, which ultimately drives your cost-per-sale down more effectively than shaving 0.1% off your markup ever will. The smartest retailers treat payment infrastructure as a revenue driver, not just a cost center.
Ready to cut your payment costs and boost your retail performance?
If you’re ready to move from theory to action, SensePass is built for exactly this challenge. We help retailers and eCommerce managers integrate low-cost, high-conversion payment options across every channel.

SensePass is a processor-agnostic orchestration layer that connects seamlessly with 50+ card processors and major platforms including NetSuite, SuiteCommerce, Oracle Xstore, Aptos, Shopify POS, BigCommerce, NCR, Storis, and Dynamics365. We support digital wallets like PayPal, Venmo, Apple Pay, Google Pay, and Alipay, BNPL options like Klarna, Sezzle, ZIP, Splitit, and Afterpay, financing through Affirm and WeGetFinancing, crypto via BitPay and Coinbase, and pay-by-bank through Trustly and LinkMoney. Explore our omnichannel payments guide or get tailored gateway selection insights to start saving today.
Frequently asked questions
What is a good average payment processing fee for retail?
A reasonable total processing fee falls between 2.5% and 3.5% plus fixed charges per transaction for online retail. If you’re consistently above 3.5%, it’s time to review your pricing model and processor contract.
What’s the fastest way to cut payment processing costs?
The quickest wins come from switching to EMV and debit where possible, negotiating your processor markup directly, and ensuring you batch transactions every single day without exception.
How can chargebacks affect my processing rates?
Chargebacks raise your effective processing cost immediately through per-chargeback fees, and keeping them below 1% is the threshold most processors use to qualify merchants for preferred interchange tiers.
Are payment processing fees negotiable?
The processor markup portion is negotiable in nearly every case. Interchange and assessment fees are set by card networks, but your processor’s cut is always worth a direct conversation, especially if your monthly volume justifies it.
Recommended
- Cut retail payment costs with omnichannel solutions – Omnichannel payments at the Point Of Sale | Sensepass
- Essential Payment Gateway Selection Tips for Retailers – Omnichannel payments at the Point Of Sale | Sensepass
- Master Payment Processing Best Practices for Your Business – Omnichannel payments at the Point Of Sale | Sensepass
- Retail payment optimization: 7 steps to boost omnichannel sales – Omnichannel payments at the Point Of Sale | Sensepass

 New York Office
260 Madison Ave Suite 8018 New York NY 10016

