
How to Set Up Multi-Method Checkout for Retailers
June 11, 2026
TL;DR:
- A multi-method checkout enables customers to pay using various methods within a single transaction, improving conversion and loyalty. Retailers should select an integration approach—hosted pages, SDKs, or direct APIs—based on their compliance capacity and customization needs, while implementing routing logic to optimize payment processing. Proper webhook verification, idempotency keys, and dynamic UI design are essential for secure, reliable, and user-friendly checkout experiences.
A multi-method checkout is a unified payment system that lets customers pay using any combination of credit cards, digital wallets, buy now pay later services, or bank transfers within a single transaction flow. Retailers who configure payment methods this way consistently see higher conversion rates, fewer abandoned carts, and stronger customer loyalty. The industry term for this architecture is “payment orchestration,” and it goes well beyond simply adding a PayPal button. This guide covers how to set up multi-method checkout from integration selection through routing logic, security, and conversion optimization, so you can make informed decisions at every step.
What are the main integration approaches to set up a multi-method checkout?
Setting up a multi-method checkout involves three primary integration approaches, each with distinct trade-offs across development time, compliance burden, and design control.
Hosted payment pages
A hosted payment page redirects customers to a provider’s secure environment to complete payment. Stripe Checkout is a common example. The key advantage is PCI scope reduction: hosted gateway checkouts qualify for SAQ A PCI compliance, the lowest possible burden, because card data never touches your servers. For retailers without a dedicated security team, this is the fastest path to a compliant, multi-payment setup. The trade-off is limited control over the visual experience.
Direct API integration
Direct API integration means your front end collects payment data and your server communicates directly with each provider’s API. This gives you full brand control over the checkout UI and lets you support any combination of payment methods without redirects. The cost is significant: direct API integrations require handling sensitive payment data and full PCI DSS compliance, which demands ongoing security audits, tokenization, and strict data handling protocols. This path suits retailers with engineering resources and a need for deep customization.
SDK and plugin-based integration
SDKs and plugins sit between the two extremes. Providers like Stripe, Adyen, and PayPal offer JavaScript SDKs that render secure, hosted input fields inside your own page. You control the layout and branding while the SDK handles sensitive data capture. This is the most practical starting point for most retail operators, balancing speed with flexibility.
| Method | Complexity | PCI Scope | Setup Speed | Customization |
|---|---|---|---|---|
| Hosted payment page | Low | SAQ A (lowest) | Hours | Limited |
| SDK / plugin | Medium | SAQ A-EP | 1 to 3 days | High |
| Direct API | High | SAQ D (full) | Weeks | Full |
- Hosted pages work best for small teams prioritizing compliance speed.
- SDKs suit most mid-market retailers who need brand consistency.
- Direct APIs are reserved for large operations with dedicated engineering.
Pro Tip: If you are evaluating payment gateway selection for the first time, start with an SDK integration. You can migrate to a direct API later once your transaction volume justifies the compliance investment.
How to implement routing logic to optimize payment processing
Routing logic is the decision engine behind which payment processor handles each transaction. Retailers use routing logic to optimize checkouts based on geography, currency, or transaction size, improving approval rates and reducing processing costs. Without it, you are sending every transaction through a single processor regardless of whether that processor is the best fit for that specific payment.
Here is a practical sequence for configuring routing rules:
-
Define your routing criteria. Start with geography: route EU card transactions to a European processor like Adyen to avoid cross-border fees. Route USD transactions to your primary domestic processor. This alone can reduce interchange costs meaningfully.
-
Set transaction size thresholds. Transactions under $100 may route to a lower-cost processor optimized for small-ticket volume. Transactions above $500 may route to a processor with stronger fraud detection and higher authorization rates for large purchases.
-
Add payment method routing. Buy now pay later transactions from Klarna or Afterpay route to those providers directly. Crypto payments via BitPay or Coinbase follow a separate path entirely. Each method has its own authorization flow and should not compete for the same processor slot.
-
Use an orchestration layer for management. Centralizing multiple PSPs with a unified orchestration layer simplifies transaction monitoring and reconciliation. Instead of logging into separate dashboards for Adyen, PayPal, and your bank processor, you manage everything from one control plane.
-
Monitor and adapt. Pull weekly approval rate reports by processor and payment method. If one processor shows declining authorization rates for a specific card network, shift that traffic to a backup provider.
Pro Tip: Track your payment routing performance by processor and card type monthly. Approval rates shift as processors update their risk models, and routing rules that worked in Q1 may underperform by Q3.
Step-by-step process for building a secure multi-method checkout
Integration is more than a UI change. It involves managing the entire order lifecycle including database idempotency, webhook validation, and failure recovery. Here is how to build it correctly.
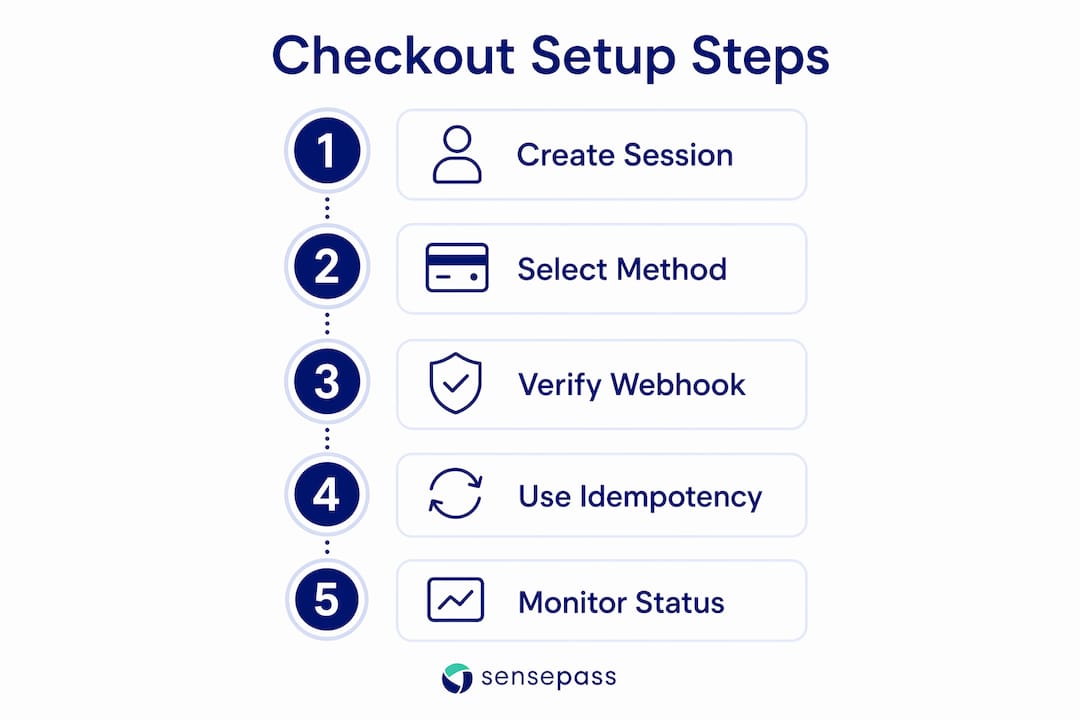
Step 1: Create payment sessions server-side. Never initialize a payment session from the browser. Use your server to call the provider API (Stripe, PayPal, Adyen) and return a client secret or session token to the front end. This keeps your API keys secure and gives you control over session parameters.
Step 2: Implement the payment method selector in your UI. Display available methods based on the customer’s location, device, and cart value. A customer in Germany should see SEPA bank transfer and Klarna. A customer in the US should see Apple Pay, Google Pay, and Affirm. Use the provider’s SDK to render the appropriate input fields for each selected method.
Step 3: Handle webhook notifications with signature verification. Server-to-server webhooks with cryptographic signature verification are the authoritative source for payment status. Every provider sends a signed payload to your endpoint when a payment succeeds, fails, or is disputed. Verify the signature on every incoming webhook before updating your order database.
Step 4: Implement idempotency keys. Idempotency keys prevent double processing during network retries or webhook re-deliveries. Assign a unique key to every payment request. If the same request arrives twice (due to a timeout or retry), your system processes it once and returns the cached result.
Step 5: Test every payment flow before going live. Use sandbox environments from Stripe, PayPal, and your other providers. Test successful payments, declined cards, webhook delivery failures, and refund flows. AI-assisted coding tools and pre-built SDKs let developers implement multi-provider checkouts in as little as one to two hours in sandbox mode, though production hardening takes longer.
Key items to verify before launch:
- Webhook endpoints return HTTP 200 within 5 seconds to avoid re-delivery loops.
- Idempotency keys are stored in your database and checked before processing.
- Refund flows are tested for each payment method independently.
- Failed payment states update the order status correctly without leaving orphaned records.
Pro Tip: Build a simple internal dashboard that shows real-time webhook delivery status per provider. When a provider has an outage, you will see failed deliveries immediately rather than discovering the issue through customer complaints.
Common mistakes to avoid when configuring payment methods
Most checkout failures trace back to a short list of recurring errors. Knowing them in advance saves significant debugging time.
-
Overloading the payment selector. Offering too many payment methods at once causes choice paralysis and increases cart abandonment. Showing 12 options to every customer is not a feature. It is friction. Filter by context and show three to five relevant methods per session.
-
Underestimating PCI compliance for direct APIs. Businesses consistently underestimate PCI DSS compliance requirements when building direct API integrations. If you are not ready for a full SAQ D audit, use an SDK or hosted page instead.
-
Relying on client-side confirmation. Relying on client-side payment confirmation or URL redirects is a major anti-pattern. A customer’s browser can close, lose connectivity, or be manipulated. Never rely on frontend redirects for payment confirmation. Backend webhook verification is the only authoritative source.
-
Ignoring routing logic errors. Improper routing rules send transactions to processors with low approval rates for that card type or geography, which raises costs and frustrates customers. Audit your routing table every quarter.
-
Skipping refund testing. Refund flows differ by provider. PayPal refunds process differently than Klarna BNPL refunds or Coinbase crypto refunds. Test each one in sandbox before launch.
Pro Tip: Run a checkout conversion audit every 90 days. Compare abandonment rates by payment method to identify which options are underperforming and whether a routing or UI change is the fix.
How to optimize the checkout experience to improve conversions
A technically correct checkout can still underperform if the user experience is poor. Optimization at this stage focuses on what the customer sees and how quickly they can complete payment.
-
Surface payment options dynamically. Show Apple Pay and Google Pay prominently to mobile users. Show Klarna or Sezzle for carts above $200. Show WeChat Pay or Alipay for customers browsing from China. Dynamic surfacing of relevant payment options based on buyer context reduces cognitive load and cart abandonment compared to showing all methods at once.
-
Design for mobile first. More than half of retail transactions now originate on mobile devices. Buttons must be large enough to tap accurately. Payment method logos must be recognizable at small sizes. Input fields must trigger the correct keyboard type automatically.
-
Offer saved payment methods. Returning customers who can pay with a saved card or wallet complete checkout in seconds. Implement tokenized card storage through your provider so customers can set a default payment method without re-entering details.
-
Integrate refund and transaction history views. Customers who can see their payment history and initiate refunds from within your platform trust it more. This reduces chargebacks and support tickets simultaneously.
-
Use real-time monitoring and analytics. Track authorization rates, decline codes, and average checkout completion time by payment method. A sudden drop in Venmo authorizations, for example, signals a configuration issue or a provider outage that needs immediate attention.
Key takeaways
A secure, high-converting multi-method checkout requires the right integration approach, well-configured routing logic, webhook-based payment verification, and context-aware UI design working together.
| Point | Details |
|---|---|
| Choose the right integration method | Match hosted pages, SDKs, or direct APIs to your team’s compliance capacity and customization needs. |
| Configure routing by context | Route transactions by geography, currency, and size to maximize approval rates and minimize processing costs. |
| Verify payments via webhooks | Use cryptographic signature verification on every webhook; never trust client-side confirmation. |
| Use idempotency keys | Assign unique keys to every payment request to prevent duplicate charges during retries. |
| Surface options dynamically | Show three to five relevant payment methods per session based on device, location, and cart value. |
Why most retailers get multi-method checkout wrong the first time
I have worked with retail operators across a wide range of transaction volumes, and the pattern is consistent. The technical integration gets most of the attention. The routing logic and operational layer get almost none. A team spends two weeks building a beautiful checkout UI with Stripe, PayPal, and Klarna, then goes live with a single routing rule that sends everything through one processor. Six months later, they are paying 30 basis points more than necessary on European transactions and wondering why their approval rate in Germany is lower than expected.
The other mistake I see constantly is treating the checkout as a one-time build. Payment providers update their APIs, change their webhook formats, and adjust their authorization logic. A checkout that works perfectly in January can develop silent failures by June if no one is monitoring it. Real-time dashboards and quarterly routing audits are not optional extras. They are the maintenance schedule for a revenue-critical system.
The good news is that orchestration platforms have made this dramatically more manageable. Instead of maintaining separate integrations for each provider, you configure rules once and let the platform handle routing, failover, and reconciliation. That is the architecture worth building toward, regardless of where you start.
— Vlad
How Sensepass makes multi-method checkout simple for retailers
If you are ready to move beyond single-processor setups, Sensepass is built specifically for this challenge.

Sensepass is a processor-agnostic orchestration layer that connects your retail operation to 50+ card processors and a broad catalog of payment methods from one integration. It integrates with major POS platforms including NetSuite, SuiteCommerce, Oracle Xstore, Aptos, Shopify POS, BigCommerce, Storis, NCR, and Dynamics365. On the payment method side, Sensepass supports digital wallets (PayPal, Venmo, WeChat, Apple Pay, Google Pay, Alipay, Amazon Pay), BNPL options (Klarna, Sezzle, ZIP, Splitit, Afterpay), financing (WeGetFinancing, Affirm), crypto (BitPay, Coinbase), and pay by bank (Trustly, LinkMoney). Explore the full scope of what is possible with omnichannel payment solutions built for retail.
FAQ
What does “multi-method checkout” mean?
A multi-method checkout is a payment system that accepts multiple payment types, such as credit cards, digital wallets, BNPL, and bank transfers, within a single unified checkout flow. The industry term for the underlying architecture is payment orchestration.
Which integration method is best for a small retail business?
An SDK-based integration is the best starting point for most small retailers. It reduces PCI compliance burden to SAQ A-EP while giving you control over branding and layout, and most providers offer pre-built SDKs that can be deployed in one to three days.
Why should I use webhooks instead of redirect confirmation?
Webhooks provide server-to-server payment confirmation with cryptographic signature verification, making them the only reliable source of payment status. Client-side redirects can fail due to browser closures or network issues, leading to missed or duplicate order records.
How many payment methods should I display at checkout?
Display three to five payment methods per session, filtered by the customer’s location, device type, and cart value. Showing too many options at once increases decision fatigue and cart abandonment without meaningfully improving conversion rates.
What is an idempotency key and why does it matter?
An idempotency key is a unique identifier attached to each payment request that prevents duplicate charges when a request is retried due to a network error or webhook re-delivery. Every multi-provider checkout system should implement idempotency keys at the API request level.
Recommended
- Optimize retail checkout for higher conversions: 70% loss – Omnichannel payments at the Point Of Sale | Sensepass
- Streamline checkout for retail success in 2026 – Omnichannel payments at the Point Of Sale | Sensepass
- How to offer seamless checkout for retail success – Omnichannel payments at the Point Of Sale | Sensepass
- How to Accept Klarna on Shopify POS Without Extra Hardware – Omnichannel payments at the Point Of Sale | Sensepass

 New York Office
260 Madison Ave Suite 8018 New York NY 10016

