
How to Simplify Call Center Payments: A 2026 Guide
June 30, 2026
TL;DR:
- Simplifying call center payments involves automating multi-channel workflows like IVR, SMS, and agent-assisted channels to enhance security and customer convenience. A phased rollout, beginning with IVR and DTMF masking, ensures operational stability, while supporting diverse payment methods reduces friction. Emphasizing PCI compliance through technology choices improves efficiency, reduces risk, and enhances agent morale.
Call center payment simplification is defined as the process of replacing manual, fragmented billing workflows with automated, multi-channel systems that handle transactions securely across IVR, SMS, and agent-assisted channels. Businesses that know how to simplify call center payments reduce average handle time, lower PCI compliance risk, and give customers the ability to pay at any hour without agent involvement. The core technologies behind this shift include Interactive Voice Response (IVR) systems, DTMF masking, tokenization, and processor-agnostic platforms like Sensepass. Getting these elements working together is not complicated, but it does require a clear sequence and the right infrastructure from the start.
How to simplify call center payments with the right technology
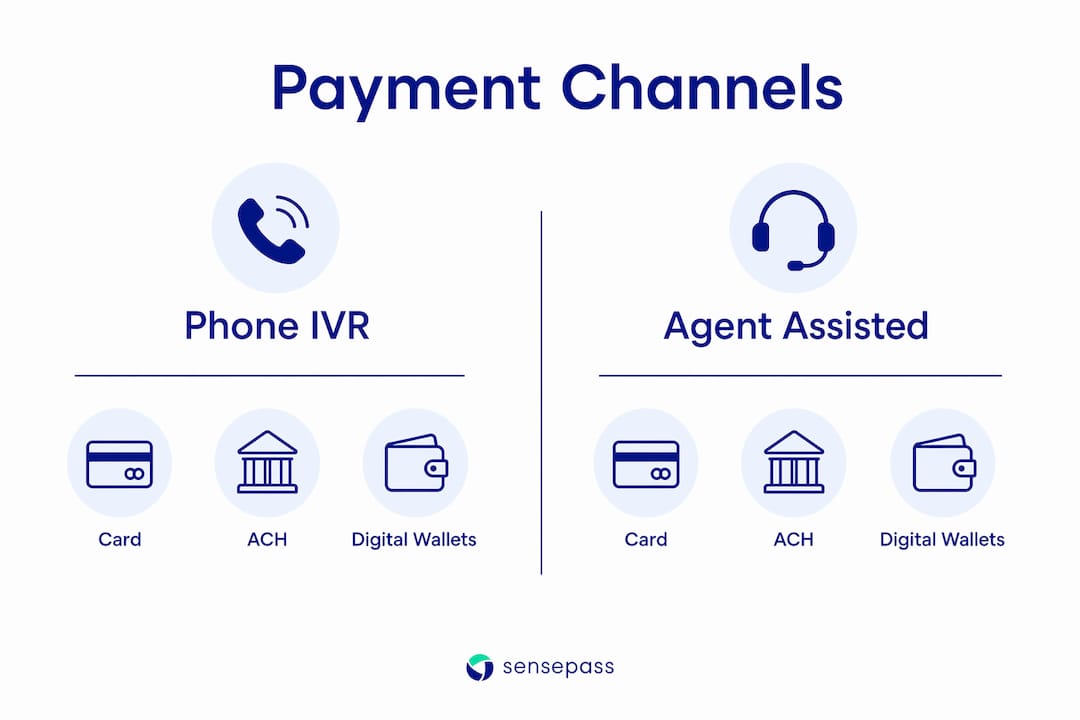
The first decision is choosing which payment channels your call center will support. Most operations benefit from three core channels: phone IVR for self-service, agent-assisted payments for complex transactions, and SMS or click-to-pay links for customers who prefer digital confirmation.

IVR payment systems let customers enter card details using their phone keypad without speaking numbers aloud to an agent. This matters for two reasons: it protects cardholder data, and it reduces average handle time by removing the agent from routine billing calls entirely. Agents can then focus on high-value interactions that actually require a human.
Text-to-pay and click-to-pay via SMS extend that same self-service logic to customers who are not on a call. You send a secure payment link, the customer completes the transaction on their own device, and the account updates in real time. This approach reduces phone wait times and improves collections during off-hours when agents are unavailable.
Pro Tip: Start with IVR before rolling out SMS-to-pay. Agents and supervisors need to understand the self-service flow before you add more channels, or you risk inconsistent customer experiences.
The payment methods your platform supports matter as much as the channels. A unified call center payment solution should accept credit and debit cards, ACH transfers, and digital wallets. Sensepass supports PayPal, Venmo, Apple Pay, Google Pay, Alipay, WeChat, and Amazon Pay. It also covers Buy Now Pay Later options including Klarna, Sezzle, ZIP, Splitit, and Afterpay, plus financing through WeGetFinancing and Affirm, crypto payments via BitPay and Coinbase, and Pay by Bank through Trustly and LinkMoney. Sensepass is processor-agnostic, connecting merchants to 50+ card processors so you are never locked into a single provider.
| Channel | Payment Methods Supported | Agent Involvement |
|---|---|---|
| Phone IVR | Card, ACH, digital wallets | None (self-service) |
| Agent-assisted | Card, ACH, BNPL | Full |
| SMS / click-to-pay | Card, digital wallets | None (self-service) |
| Web chat checkout | Card, BNPL, financing | Partial |
How to implement automated, multi-channel payment solutions
Implementation works best as a phased rollout. Jumping straight to full omnichannel deployment without a clear sequence creates operational gaps and confuses both agents and customers.
Follow this order:
- Audit your current infrastructure. Map every point where a payment is collected today, including phone, email, and paper check. Identify which channels carry the highest volume and the most compliance risk.
- Select a scalable payment platform. Choose a platform with multi-channel support, API access, and CRM integration. Sensepass integrates with NetSuite, SuiteCommerce, Oracle Xstore, Aptos, Shopify POS, BigCommerce, Storis, NCR, and Dynamics365, among others.
- Deploy IVR with DTMF masking first. Configure your IVR using a SIP redirect with a conference bridge to isolate the customer’s DTMF tones from the agent. This architecture preserves call quality while keeping card data out of the agent’s environment entirely.
- Integrate with your CRM and billing system. Real-time CRM integration updates customer accounts immediately after payment, which eliminates manual reconciliation and prevents duplicate follow-up calls.
- Roll out SMS and web chat payment channels. Once IVR is stable, extend to text-to-pay and web chat checkout. Sequential channel adoption starting with phone IVR, then web chat, web checkout, and SMS reduces operational risk at each stage.
Pro Tip: Before going live on any new channel, run a parallel test period where agents manually verify that automated payment confirmations match what appears in your billing system. Catch reconciliation gaps before customers do.
The integration step is where most implementations stall. Teams underestimate how many downstream systems touch a payment record. Map every system that needs a payment status update, including your CRM, ERP, collections platform, and customer notification engine, before you write a single API call.
What are the compliance and security best practices for call center payments?
PCI DSS compliance in a call center environment depends almost entirely on how much cardholder data your agents can access. The less they see, the smaller your compliance scope.
The key techniques for reducing PCI scope are:
- DTMF masking: Suppresses the audio tones of keypad entries so agents cannot hear card numbers being entered. This single control removes cardholder data from the call center environment and drastically simplifies PCI audits.
- Channel separation: Routes payment entry to a secure IVR or web form rather than through the agent’s workstation. Agents never see, hear, or type card data.
- Tokenization: Replaces card numbers with tokens for storage and recurring billing. Tokens are useless to attackers even if intercepted.
- Encryption in transit: All payment data must travel over TLS 1.2 or higher between your call center systems and the payment processor.
“PCI compliance in call centers largely depends on removing cardholder data access from agents, achievable through technologies like DTMF masking and channel separation.” — PCI compliance best practices for call centers
Eliminating risky channels is equally important. Email payment requests, where customers reply with card numbers, are never PCI-compliant and should be removed from your process entirely. Replace them with secure click-to-pay links that expire after a single use.
Automation also reduces audit complexity. When payments flow through a single platform with a consistent audit trail, your compliance team reviews one system instead of five. That cuts both the time and cost of your annual PCI assessment.
How does payment automation improve operational efficiency?
Payment automation is a control improvement as much as an efficiency gain. Manual bank reconciliations can take days and uncover errors late, while automated platforms provide immediate error detection and reconciliation. That difference matters when your collections team is chasing overdue accounts.
The operational benefits stack up quickly:
- Lower average handle time. Agents spend less time on routine billing calls when customers can self-pay through IVR or SMS.
- 24/7 payment capability. Self-service channels accept payments outside business hours without additional staffing.
- Higher electronic payment conversion. Consolidating ACH, virtual cards, and traditional card payments into one platform multiplies conversion rates to electronic payments by 2–3x compared to manual methods.
- Real-time reconciliation. Automated platforms validate, authorize, and reconcile payments immediately, giving your AP team accurate data without end-of-day batch processing.
- Rebates from virtual card transactions. Businesses using payment automation platforms earn rebates on virtual card spend that partially offset processing costs.
The agent experience improves too. When routine billing calls drop, agents handle fewer repetitive interactions and spend more time on work that requires judgment. That shift tends to reduce turnover, which is a real cost in high-volume call centers.
For a detailed walkthrough of the execution steps, the 2026 call center payments guide covers the full process from infrastructure audit to live deployment.
What common challenges occur when simplifying call center payments?
The most common failure point is a poorly sequenced channel rollout. Inconsistent customer payment experiences and operational disruption are the direct result of launching multiple channels simultaneously without a tested cutover plan.
Watch for these specific pitfalls:
- Skipping the infrastructure audit. Teams that skip this step discover mid-rollout that their CRM cannot accept real-time payment status updates. Fix this before deployment, not after.
- Inconsistent authentication across channels. A customer who verifies identity one way on IVR and a different way on SMS will notice the inconsistency. Standardize your authentication logic across all channels from day one.
- Ignoring agent training. Automation handles the transaction, but agents still field questions about it. Train agents on what the self-service flow looks like from the customer’s perspective.
- Delaying compliance review. Bring your PCI QSA (Qualified Security Assessor) into the planning process early. Retrofitting compliance controls after deployment costs significantly more than building them in from the start.
Pro Tip: After each channel goes live, run a two-week monitoring period where your team reviews failed transactions, authentication errors, and reconciliation mismatches daily. Catching these early prevents them from becoming systemic.
The businesses that simplify call center billing most successfully treat the rollout as a continuous process, not a one-time project. Set a quarterly review cadence to assess channel performance, update payment method support, and address any new compliance requirements.
Key Takeaways
Simplifying call center payments requires a phased rollout of IVR, SMS, and agent-assisted channels, backed by DTMF masking, tokenization, and real-time CRM integration to reduce compliance scope and manual workload.
| Point | Details |
|---|---|
| Start with IVR | Deploy phone IVR with DTMF masking first to reduce PCI scope and agent handle time. |
| Sequence your channels | Roll out IVR before SMS and web chat to avoid inconsistent customer experiences. |
| Automate reconciliation | Real-time payment platforms eliminate manual batch processing and catch errors immediately. |
| Remove risky channels | Eliminate email-based payment requests and replace them with expiring click-to-pay links. |
| Choose processor-agnostic platforms | Platforms like Sensepass connect to 50+ processors, preventing vendor lock-in and maximizing flexibility. |
Why compliance should be your first efficiency argument
I have seen call center payment projects stall for one consistent reason: the compliance conversation happens too late. Teams spend months selecting a platform and designing the customer flow, then hand the project to their QSA three weeks before go-live. That sequence almost always results in delays, rework, and budget overruns.
The more useful framing is to treat PCI compliance as the architecture constraint that shapes everything else. When you start with the question “how do we keep card data out of the agent environment entirely,” the technology choices become obvious. DTMF masking, channel separation, and tokenization are not compliance burdens. They are the design decisions that make the rest of the system simpler.
I have also watched agent morale improve noticeably when routine billing calls drop. Agents who spend their day on complex customer problems are more engaged than agents who read card numbers into a system for eight hours. That is a real retention benefit, and it is one that rarely shows up in the ROI model for payment automation projects.
The businesses that get this right align their payment technology choices with their existing call workflows rather than forcing agents to adapt to a new system mid-call. The technology should be invisible to the agent. If an agent has to think about the payment platform during a call, the implementation needs more work.
— Vlad
Sensepass powers call center payments across every channel
Call centers that need a single platform to handle IVR, SMS, agent-assisted, and web checkout payments will find that Sensepass covers the full range.

Sensepass integrates with NetSuite, SuiteCommerce, Oracle Xstore, Aptos, Shopify POS, BigCommerce, Storis, NCR, and Dynamics365. It accepts digital wallets (PayPal, Venmo, Apple Pay, Google Pay, Alipay, WeChat, Amazon Pay), BNPL options (Klarna, Sezzle, ZIP, Splitit, Afterpay), financing through WeGetFinancing and Affirm, crypto via BitPay and Coinbase, and Pay by Bank through Trustly and LinkMoney. As a processor-agnostic platform, Sensepass connects to 50+ card processors so you choose the processor that fits your cost structure. For a full overview of how unified payment channels work together, the omnichannel payments guide covers every layer of the architecture.
FAQ
What is the fastest way to reduce PCI scope in a call center?
Deploy DTMF masking on your IVR system so agents never hear or access card numbers. This single control removes cardholder data from the call center environment and significantly reduces your PCI audit scope.
How does IVR improve call center payment efficiency?
IVR lets customers complete payments without agent involvement, which reduces average handle time and enables 24/7 payment acceptance. Agents are freed to handle interactions that require judgment rather than routine billing.
What payment methods should a call center platform support?
A complete call center payment solution should accept credit and debit cards, ACH, digital wallets like Apple Pay and Google Pay, BNPL options like Klarna and Afterpay, and bank transfer methods. Supporting multiple methods increases the percentage of customers who complete payment on the first contact.
What is the right order to roll out payment channels?
Start with phone IVR, then add web chat, web checkout, and SMS-to-pay in sequence. This phased approach reduces operational risk and gives your team time to validate each channel before adding the next.
How does payment automation affect reconciliation?
Automated platforms validate, authorize, and reconcile transactions in real time, replacing manual batch processes that can take days. Immediate reconciliation reduces errors and gives your finance team accurate data without end-of-day delays.
Recommended
- Step by Step Call Center Payments: 2026 Guide – Omnichannel payments at the Point Of Sale | Sensepass
- Mastering the Omnichannel Payment Workflow Guide – Omnichannel payments at the Point Of Sale | Sensepass
- Call Center – Omnichannel payments at the Point Of Sale | Sensepass
- Master Payment Processing Best Practices for Your Business – Omnichannel payments at the Point Of Sale | Sensepass

 New York Office
260 Madison Ave Suite 8018 New York NY 10016

