
How to improve the in-store payment experience: 5 steps
April 1, 2026
Friction at checkout is not a minor inconvenience. It is a direct revenue leak. 83% of shoppers say quick checkout is the most important aspect of their in-store visit, and 32% will abandon a purchase entirely if the wait exceeds five minutes. For retail executives managing multi-location operations, aging POS infrastructure, or a limited mix of payment options, the cost of inaction compounds daily. This guide walks you through a clear, step-by-step approach to modernizing your in-store payment experience, from diagnosing current friction points to future-proofing your checkout ecosystem with the payment methods and integrations today’s shoppers expect.
Table of Contents
- Assess current pain points in the payment process
- Select and integrate diverse payment methods
- Implement and test streamlined checkout flows
- Address self-service, security, and shrinkage risks
- Monitor, optimize, and future-proof the payment experience
- Why payment experience is your silent differentiator
- Simplify next steps with seamless omnichannel payments
- Frequently asked questions
Key Takeaways
| Point | Details |
|---|---|
| Speed wins loyalty | Fast, flexible payment options boost satisfaction and prevent abandonment at checkout. |
| Diversity drives sales | Offering digital wallets, contactless, and traditional payment methods covers every customer preference. |
| Testing prevents issues | Simulating real checkout flows exposes bottlenecks before customers do. |
| Security matters | Balancing self-service with smart loss prevention keeps profit margins healthy. |
| Continuous optimization | Regularly reviewing analytics and customer feedback ensures your payment experience stays ahead. |
Assess current pain points in the payment process
With the stakes clear, it’s vital to first pinpoint precisely where your payment experience breaks down. Most retailers assume their checkout works well until they measure it. The gap between perception and reality is often significant.
Common friction points include:
- Slow POS response times that add seconds to every transaction and create visible queue buildup
- Limited payment method acceptance, forcing customers to use their second or third choice
- Poorly trained staff who hesitate during edge cases, slowing the line
- Outdated hardware that fails to read contactless cards or mobile wallets reliably
- No self-checkout option, which 73% of consumers prefer for routine purchases
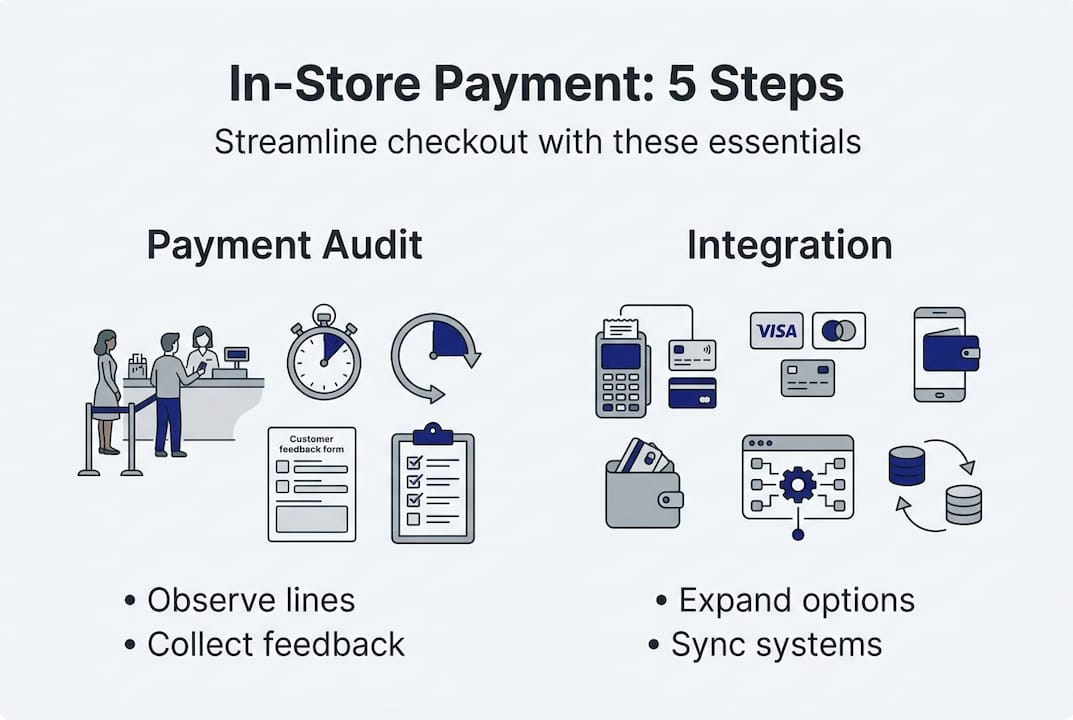
Start with a structured self-audit. Observe peak-hour checkout lines in person. Collect direct feedback from both customers and frontline staff. Measure scan-to-payment latency on your current system. Even a 10-second improvement per transaction can meaningfully reduce queue length during high-traffic periods.
Here is a quick benchmark table to orient your assessment:
| Metric | Industry benchmark | Action threshold |
|---|---|---|
| Average transaction time | Under 30 seconds | Over 45 seconds |
| Checkout abandonment rate | Under 5% | Over 10% |
| Contactless acceptance | 90%+ of terminals | Below 70% |
| Payment method variety | 6+ methods | Fewer than 4 |
The contactless payment benefits for retail stores go beyond speed. They reduce physical touchpoints, lower error rates, and signal to customers that your store is current. If your audit reveals gaps in any of the metrics above, you have a clear starting point for improvement.
Select and integrate diverse payment methods
Once you’ve mapped the main issues, the next step is expanding your payment toolkit in a way that fits your customer base. Payment method variety is not about offering everything. It is about offering the right things, integrated correctly.
By 2024, 82% of US consumers had used digital wallets, and contactless payments accounted for 53% of all transactions. Meanwhile, wallet POS transactions grew from 3% in 2014 to 32% in 2024, with projections reaching 45% by 2030. These are not niche preferences. They are mainstream expectations.
Here is how leading payment methods compare across key dimensions:
| Payment method | Speed | Fraud risk | Primary demographic | Processing cost |
|---|---|---|---|---|
| Contactless card | Fast | Low | All ages | Low to medium |
| Mobile wallet (Apple Pay, Google Pay) | Very fast | Very low | Under 45 | Low |
| BNPL (Klarna, Afterpay) | Medium | Medium | 18 to 35 | Medium to high |
| Cash | Slow | High (shrink) | All ages | Low |
| Crypto (BitPay, Coinbase) | Medium | Low | Tech-forward | Variable |
Integration is where many retailers stumble. Adding a new payment method that does not sync with your inventory or accounting system creates reconciliation headaches that cost more than the revenue gained. Prioritize methods that connect cleanly to your existing stack.
Pro Tip: When accepting digital wallets, lead with the wallets your younger shoppers already use, such as Apple Pay, Google Pay, and PayPal. But do not phase out traditional card acceptance. Older demographics still rely on physical cards, and losing that segment is a real cost.
For retailers looking at mobile payment technology, the key is ensuring your POS hardware and software can handle multiple tender types without requiring staff to switch modes or reboot systems between transactions.
Implement and test streamlined checkout flows
With the right array of properly integrated payment tools, it’s time to make the checkout flow feel frictionless for all users. A well-chosen payment method that is poorly implemented will still frustrate customers.
Follow this numbered rollout sequence:
- Configure hardware first. Install updated terminals, confirm contactless readers are active, and verify that all payment methods appear correctly on the customer-facing display.
- Run internal test payments. Use real cards, real wallets, and real BNPL apps. Do not rely on sandbox simulations alone.
- Train staff with scenario-based drills. Cover declined cards, wallet errors, and BNPL approval flows. Staff confidence directly reduces queue time.
- Measure baseline queue times before going live with the new setup, so you have a comparison point.
- Launch a pilot period at one or two locations before full rollout. Collect structured feedback from customers and staff daily.
- Iterate based on real data. Adjust signage, terminal placement, or staff scripts as issues surface.
“Phygital testing and user walkthroughs with real payment instruments are essential for smooth omnichannel experiences.”
Pro Tip: Use both mystery shoppers and direct staff observations during the pilot. Mystery shoppers catch the experience gaps that staff become blind to over time. Together, they give you a complete picture.
A solid mobile POS overview can help you understand where mobile terminals fit into your floor layout, especially for line-busting during peak hours. For deeper guidance on mobile payment workflows, look at how leading retailers structure their queue management alongside their payment stack.
Address self-service, security, and shrinkage risks
But as checkout gets faster and more autonomous, new risks emerge that you must proactively manage. Self-checkout is popular. It is also expensive when shrinkage is not controlled.
Self-checkout shrinkage runs at 3.5 to 4%, compared to under 1% for attended lanes. Critically, 36% of unscanned items are unintentional, meaning customers are not always trying to steal. They are confused, distracted, or dealing with scanner errors.
Shrinkage causes and mitigations to address now:
- Unintentional scan failures: Improve scanner sensitivity and add clear audio or visual confirmation for each item scanned
- Intentional theft: Deploy AI-assisted computer vision at self-checkout bays to flag unscanned items in real time
- Receipt check gaps: Implement randomized receipt verification without creating the same queue friction you eliminated
- Access control weaknesses: Restrict POS override functions to authorized staff only, with logged audit trails
- Bagging area confusion: Redesign bagging zones to reduce weight sensor errors that frustrate honest customers
The retail payment security tips that matter most are the ones that protect revenue without degrading the customer experience. Security theater, such as checks that slow everyone down equally, erodes the speed advantage self-checkout is supposed to deliver. Focus on targeted interventions that catch real loss without punishing the majority of honest shoppers.
Monitor, optimize, and future-proof the payment experience
After systems are running smoothly, continual improvement is key to keeping the edge and avoiding obsolescence. Payment technology moves fast. What feels modern in 2026 may feel dated by 2028.
Set clear KPIs from day one:
- Conversion rate at checkout: Are fewer customers abandoning after approaching the register?
- Average transaction time: Is it trending down across all payment types?
- Shrinkage rate: Is self-checkout loss staying within acceptable bounds?
- Customer satisfaction scores: Are post-visit surveys reflecting a better experience?
- Staff error rate: Are training investments reducing override requests and manual corrections?
The mobile POS market is projected to grow from $30 billion in 2024 to $80 billion by 2034, and unified customer profiles are becoming the standard for seamless omnichannel flow. Retailers who build their payment infrastructure with that trajectory in mind will spend less on future upgrades.
Practical optimization actions to schedule quarterly:
- A/B test different checkout flow layouts at pilot locations
- Retrain staff on any newly added payment methods or updated workflows
- Update in-store signage to reflect current accepted payment options
- Review payment processing best practices as new standards emerge
- Survey customers on payment method preferences at least twice per year
Biometric payments and offline digital wallet functionality are two areas worth watching closely. Both are moving from pilot to mainstream faster than most retailers expect.
Why payment experience is your silent differentiator
With the groundwork laid, it’s time to zoom out and challenge how payment is perceived within your operations. Most retail leaders treat payment infrastructure as plumbing: necessary, invisible, and only worth attention when something breaks. That framing is costing you customers you never know you lost.
A shopper who hits a declined wallet, waits through a slow terminal reboot, or can’t use their preferred BNPL option does not always complain. They just don’t come back. That silent churn is the most dangerous kind because it never shows up in your complaint data.
The contrarian truth is this: the retailers winning on payment experience are not always the ones with the newest hardware. They are the ones who invested in staff training, real-world testing, and honest feedback loops. Technology without process discipline is just expensive friction in a different form.
As one useful frame from processing best practices makes clear, the checkout moment is the last brand impression you leave. Make it count. A fast, flexible, error-free payment experience is not a backend detail. It is a competitive signal that customers feel even when they can’t articulate it.
Simplify next steps with seamless omnichannel payments
For leaders ready to close the gap between payment potential and reality, here’s how to move into action.
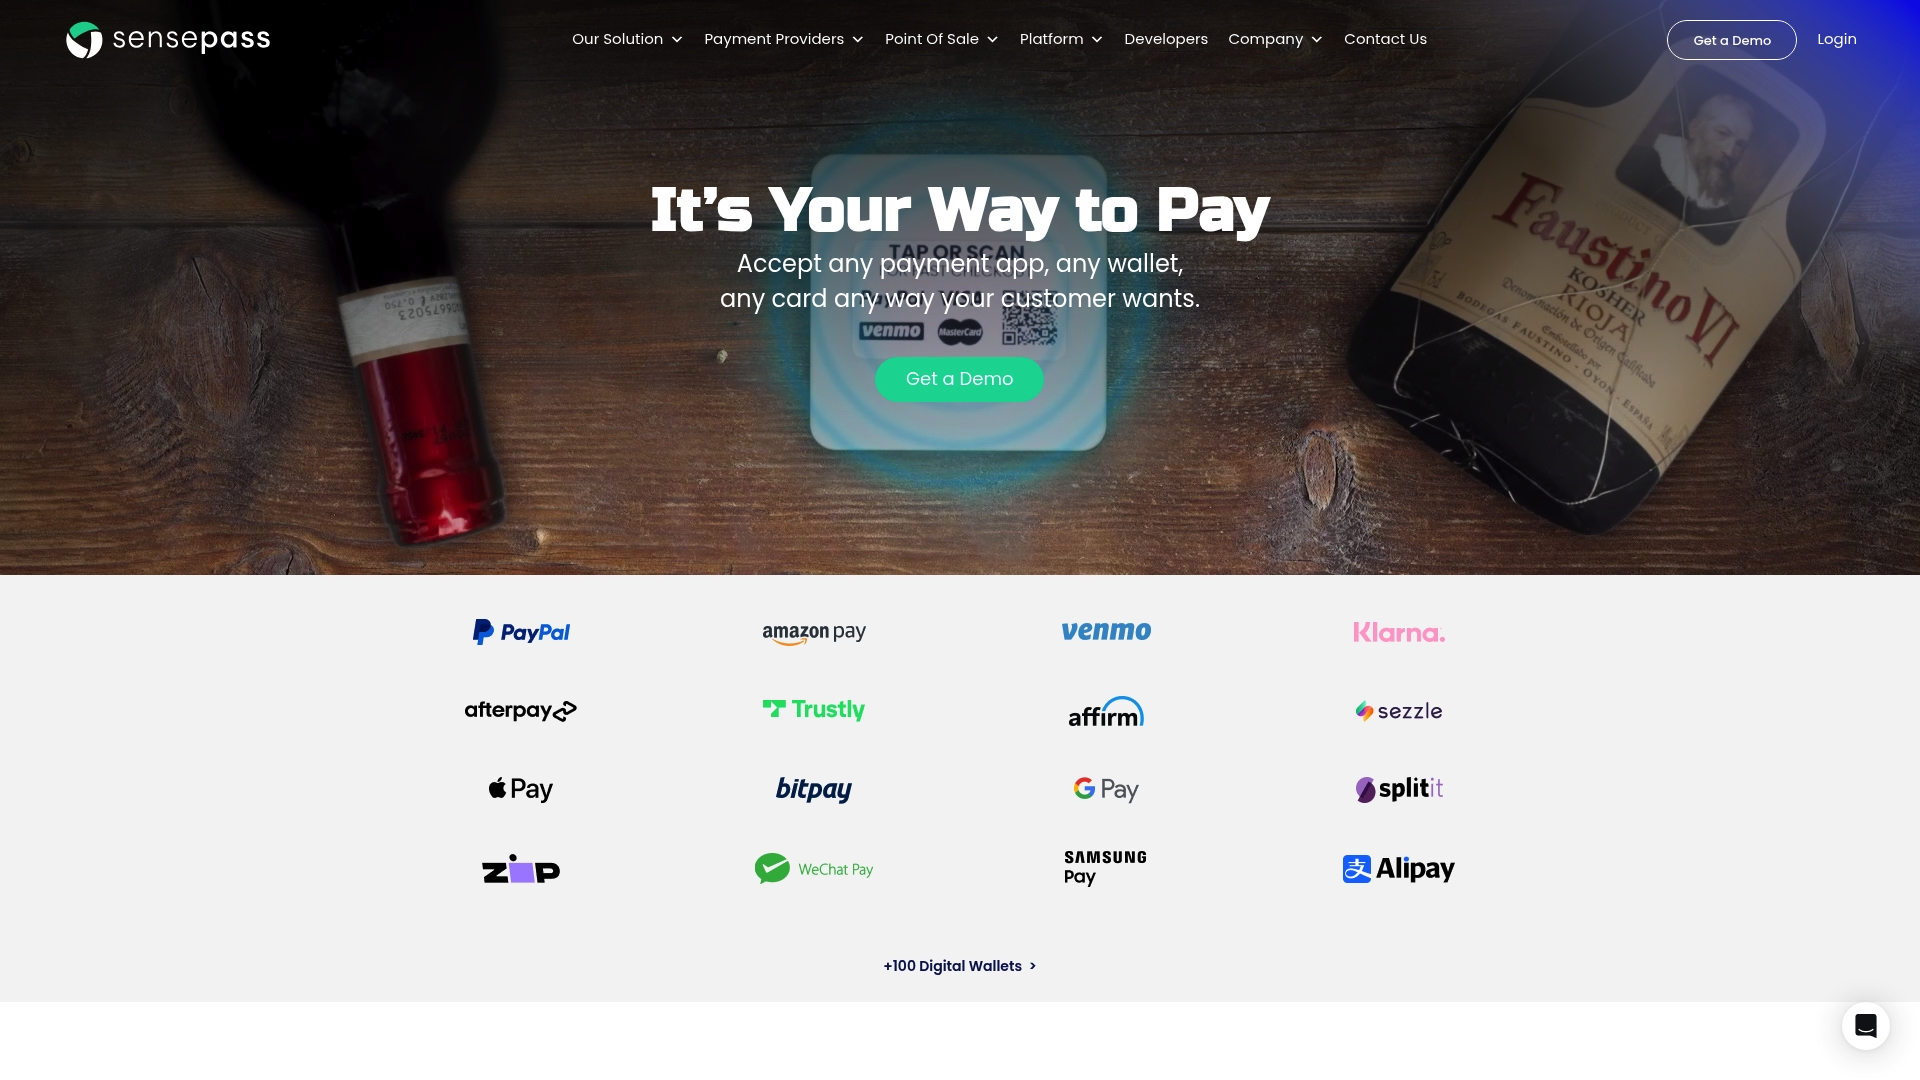
SensePass is built specifically for retailers who need a single orchestration layer that connects every payment method and every channel without the integration headache. SensePass integrates seamlessly with major platforms including NetSuite, SuiteCommerce, Oracle Xstore, Aptos, Shopify POS, BigCommerce, Storis, NCR, and Dynamics365. It supports digital wallets like PayPal, Venmo, Apple Pay, Google Pay, Alipay, WeChat, and Amazon Pay, BNPL options including Klarna, Sezzle, ZIP, Splitit, and Afterpay, financing through Affirm and WeGetFinancing, crypto via BitPay and Coinbase, and Pay by Bank through Trustly and LinkMoney. SensePass is also processor-agnostic, giving you access to 50+ card processors.
Explore omnichannel payments for retailers to see how SensePass fits your operation, and review the payment gateway selection tips to make a confident, informed decision for your next upgrade.
Frequently asked questions
Which in-store payment option is fastest for customers?
Contactless and mobile payments are now 30% faster than card or cash transactions, with biometric authentication reducing friction even further at high-volume checkout points.
How does self-checkout affect retail shrinkage?
Self-checkout shrinkage ranges from 3.5 to 4%, compared to under 1% for attended lanes, meaning the labor savings can be partially or fully offset without proper loss prevention controls in place.
What’s the biggest benefit of integrating digital wallets at POS?
Digital wallet integration meets the payment preferences of the majority of shoppers, and wallet POS transactions have grown from 3% to 32% over the past decade, with projections pointing to 45% by 2030.
How should retailers test new payment flows?
Phygital testing and hands-on walkthroughs with real payment instruments surface real-world issues before full rollout, giving your team the chance to fix problems before customers encounter them.
Recommended
- In-store mobile payment workflows: 30% faster checkout – Omnichannel payments at the Point Of Sale | Sensepass
- Master Payment Processing Best Practices for Your Business – Omnichannel payments at the Point Of Sale | Sensepass
- 7 Key Benefits of Contactless Payments for Retail Stores – Omnichannel payments at the Point Of Sale | Sensepass
- 7 Types of Retail Payment Methods for Your Business – Omnichannel payments at the Point Of Sale | Sensepass

 New York Office
260 Madison Ave Suite 8018 New York NY 10016

