
In-store mobile payment workflows: 30% faster checkout
March 30, 2026
Slow checkout lines cost retailers more than time. They cost sales. When a customer reaches the register and their preferred payment method isn’t supported, that friction translates directly into abandoned carts and lost loyalty. 53% of retail transactions are now contactless, and 82% of US consumers use digital wallets regularly. If your in-store payment workflow hasn’t kept pace, this guide walks you through every step: from preparing your hardware and staff to running a live transaction and optimizing for long-term performance.
Table of Contents
- Why in-store mobile payments matter
- Key components and prerequisites
- Step-by-step: In-store mobile payment workflow
- Troubleshooting and edge cases
- Verifying and optimizing your workflow
- Upgrade your in-store payment experience
- Frequently asked questions
Key Takeaways
| Point | Details |
|---|---|
| Mainstream adoption | Over half of all retail transactions now rely on contactless or mobile payment methods. |
| Fast, secure workflow | Implementing the right POS integration speeds up checkout while protecting customer data. |
| Technology readiness | NFC-enabled POS terminals and software compatibility are critical to seamless payment experience. |
| Staff and troubleshooting | Proper staff training and clear troubleshooting steps minimize workflow disruptions. |
| Continuous improvement | Monitor, test, and regularly update systems and training for ongoing mobile payment success. |
Why in-store mobile payments matter
Mobile payments are no longer a novelty. They are the baseline expectation for a growing segment of your customers. Apple Pay and Google Pay dominate wallet usage in the US, but platforms like PayPal, Venmo, Alipay, and WeChat are gaining ground fast, especially among younger and international shoppers.
The business case is concrete. Seamless POS integration reduces checkout time by 30 to 41% and boosts revenue by up to 9.5%. That’s not a marginal improvement. That’s a measurable shift in throughput and customer satisfaction.
Here’s what retailers consistently report after upgrading to mobile-ready checkout:
- Shorter lines and faster table turns in food and beverage settings
- Fewer cashier errors from manual card entry
- Higher average transaction values when BNPL options are available
- Stronger customer retention from a frictionless experience
Understanding the advantages of contactless payments goes beyond speed. It includes hygiene, security, and the ability to serve customers who carry no physical wallet at all. If you want a broader overview of how this technology works, the contactless payment overview is a solid starting point.
Stat to know: Retailers who integrate mobile payments with their POS systems see up to a 9.5% revenue lift, according to industry statistics.
Key components and prerequisites
Before you flip the switch on mobile payments, your infrastructure needs to be ready. Rushing deployment without the right hardware or configuration is the fastest way to create checkout failures.
In-store mobile payments rely on NFC (Near Field Communication) and EMV (Europay, Mastercard, Visa) standards. NFC handles the wireless data exchange between the customer’s device and your terminal. EMV governs the security protocols that protect that transaction.
Here’s what you need in place before going live:
- NFC-enabled POS terminals: Not all terminals support NFC. Verify your hardware model before assuming compatibility.
- EMV certification: Your terminal must be EMV-certified to process chip and contactless transactions securely.
- Tokenization support: This replaces sensitive card data with a unique token during transmission, protecting both you and your customer.
- Wallet acceptance configuration: You need to enable Apple Pay, Google Pay, and other wallets at the processor level, not just the hardware level.
- Stable network connectivity: Mobile payments require a live internet connection. Offline fallback options are limited.
For a deeper look at the technology behind these requirements, the mobile payment technology guide covers the architecture in practical terms. If you’re evaluating hardware options, the mobile POS systems guide compares the leading terminal types.
| Requirement | Why it matters | Common gap |
|---|---|---|
| NFC hardware | Enables tap-to-pay | Older terminals lack NFC |
| EMV certification | Fraud liability protection | Uncertified = liability shift |
| Tokenization | Protects card data | Not all processors include this |
| Wallet enablement | Accepts Apple Pay, Google Pay | Requires processor-level setup |
| Network reliability | Authorizes transactions in real time | Dead zones at checkout |
For a curated list of tools and platforms, the mobile payment solutions list is worth reviewing before you finalize your stack.
Also confirm your setup supports Apple Pay at the merchant level, which requires a separate enrollment step with your payment processor.
Pro Tip: Ask your terminal vendor specifically whether NFC is enabled by default or requires a firmware update. Many retailers discover their hardware supports NFC but it was never activated.
Step-by-step: In-store mobile payment workflow
Once your infrastructure is ready, the actual transaction flow is straightforward. Here’s exactly what happens from the moment a customer reaches the register.
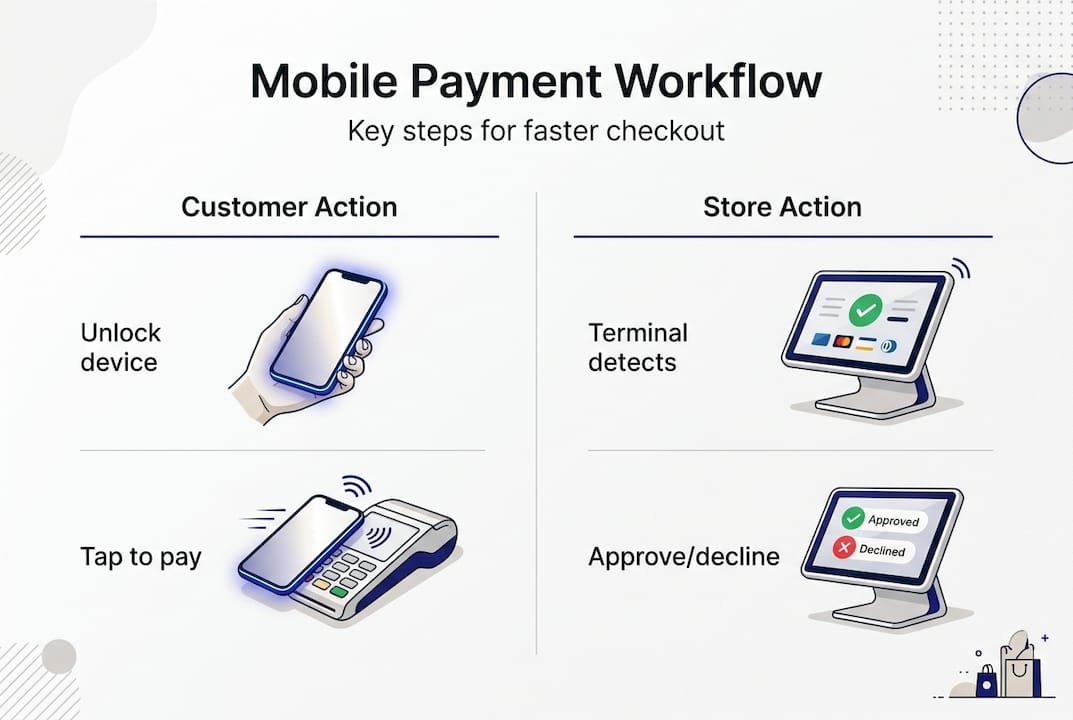
- Customer initiates payment: The customer opens their wallet app (Apple Pay, Google Pay, PayPal, etc.) or holds their device near the terminal. Some wallets activate automatically when the screen is on.
- NFC handshake: The terminal broadcasts a short-range NFC signal. When the customer’s device enters range (typically within 4 cm), the two devices exchange encrypted payment data.
- Tokenization occurs: The payment data is tokenized and authorized in real time. The actual card number is never transmitted.
- Authorization request: Your POS sends the tokenized data to your payment processor, which routes it to the card network and issuing bank for approval.
- Approval and confirmation: The terminal displays a confirmation (checkmark, beep, or both). The customer’s device also shows a confirmation notification.
- POS record update: Your POS system logs the transaction automatically, updates inventory if integrated, and triggers a receipt via print, email, or SMS.
Different wallets behave slightly differently at step one. Apple Pay requires Face ID or Touch ID before the transaction. Google Pay can work with the screen unlocked. Other wallets like Venmo or Alipay may require the customer to open the app manually.
| Wallet | Authentication method | Offline capability | Refund support |
|---|---|---|---|
| Apple Pay | Face ID / Touch ID | No | Yes |
| Google Pay | Screen unlock / biometric | No | Yes |
| PayPal | App open / biometric | No | Yes |
| Alipay | App QR or NFC | Limited | Yes |
| Venmo | App open | No | Yes |
For real-world contactless payment examples across different retail formats, that resource shows how the workflow adapts to grocery, apparel, and food service environments. If you’re running Shopify POS, the Shopify POS integration with wallets guide covers wallet enablement in that specific environment.
For WooCommerce users, the Stripe Terminal integration documentation walks through the SDK setup for in-person payments.
Pro Tip: Run a test transaction with each wallet type before going live. Authorization speeds vary, and knowing what to expect helps staff avoid interrupting a transaction that’s still processing.
Troubleshooting and edge cases
Even a well-configured setup will encounter failures. Knowing the most common causes helps you resolve them fast and keep lines moving.
Leading causes of mobile payment failure include network connectivity issues, NFC misalignment between device and terminal, thick phone cases blocking the NFC signal, low battery mode disabling wallet functions, and outdated POS firmware.
Here’s how to address each:
- NFC misalignment: Train staff to guide customers to hold their device flat and centered over the terminal, not at an angle.
- Thick cases: Some cases, especially those with metal components, block NFC entirely. Ask the customer to remove the case.
- Low battery mode: Both iOS and Android disable NFC wallet functions in low-power mode. The customer needs to charge or disable battery saver.
- Outdated POS firmware: Schedule regular firmware updates. An outdated terminal may reject newer wallet versions.
- Network dead zones: This is the most common and most fixable issue. Test your signal at every checkout counter before deployment.
“Indoor network blackspots are one of the most overlooked causes of payment failure. A terminal that works perfectly in testing can fail consistently at a specific register due to signal interference.”
For additional NFC troubleshooting steps, that guide covers Android-specific fixes in detail. Always have a backup payment method available, whether that’s a traditional card swipe or a QR code fallback, so no sale is lost during a technical issue.
Understanding the business case for mobile payments also helps you justify the investment in redundancy and staff training to stakeholders who may question the cost.
The mobile commerce omnichannel growth data reinforces why solving these edge cases matters: retailers who fail to deliver consistent mobile payment experiences lose customers to competitors who do.
Verifying and optimizing your workflow
Deployment is not the finish line. Ongoing verification and optimization are what separate retailers who see sustained ROI from those who see initial gains plateau.
Use this checklist before and after going live:
- POS readiness check: Confirm NFC is active, firmware is current, and wallet acceptance is enabled at the processor level.
- Device compatibility test: Run test transactions with at least three wallet types (Apple Pay, Google Pay, and one additional).
- Staff readiness review: Confirm every cashier knows the standard workflow, the most common failure causes, and the backup process.
- Connectivity audit: Test signal strength at each checkout counter during peak hours, not just during setup.
- Transaction monitoring: Track decline rates by terminal and by wallet type. A spike in declines at one register usually points to a hardware or network issue.
- Customer feedback loop: Add a simple post-transaction prompt asking about checkout experience. Patterns in negative feedback often surface issues before they become systemic.
- Scheduled updates: Set a quarterly calendar reminder to check for terminal firmware updates and processor configuration changes.
For a broader look at how to improve overall checkout performance, the POS optimization strategies guide covers conversion-focused improvements beyond mobile payments.
Monitor your average transaction time weekly for the first 90 days. If mobile payment transactions are taking longer than card swipes, that’s a signal to investigate NFC positioning, network latency, or processor routing.
Upgrade your in-store payment experience
You now have the full picture: from hardware requirements to live transaction flow to ongoing optimization. The next step is making sure your payment infrastructure can support not just today’s wallets, but every method your customers will expect tomorrow.

SensePass is an omnichannel payment orchestration layer built specifically for retailers. It integrates seamlessly with major POS platforms including NetSuite, SuiteCommerce, Oracle Xstore, Aptos, Shopify POS, BigCommerce, Storis, NCR, Dynamics365, and more. Beyond POS integration, SensePass supports digital wallets (Apple Pay, Google Pay, PayPal, Venmo, WeChat, Alipay, Amazon Pay), BNPL options (Klarna, Afterpay, Sezzle, ZIP, Splitit), financing (Affirm, WeGetFinancing), crypto (BitPay, Coinbase), and Pay by Bank (Trustly, LinkMoney). It’s also processor-agnostic, giving you access to 50+ card processors. Explore omnichannel payments for retailers, learn what omnichannel payment means for your business, and review payment gateway tips to make the right infrastructure decisions.
Frequently asked questions
How does NFC work for in-store payments?
NFC enables contactless data transfer between a mobile device and the POS terminal when held within a few centimeters, using tokenization to replace sensitive card data with a secure token before transmission.
What is the biggest cause of mobile payment failure at checkout?
Indoor network blackspots at checkout counters are the leading cause of mobile payment failures, making signal testing before deployment a critical step.
Which POS systems support digital wallets like Apple Pay and Google Pay?
Most modern NFC-enabled POS systems support Apple Pay and Google Pay, including Stripe Terminal for WooCommerce, Shopify Tap to Pay, and platforms integrated through SensePass.
How do I prepare my staff for mobile payments?
Train staff on correct device positioning over the NFC reader, the most common failure causes, and the backup payment workflow so they can handle exceptions without slowing the line.
Can in-store mobile payments be used for refunds or partial payments?
Yes. Most integrated mPOS systems, including Shopify Tap to Pay, support full refunds, partial refunds, and split payments using mobile wallets.
Recommended
- Streamline checkout for retail success in 2026 – Omnichannel payments at the Point Of Sale | Sensepass
- 7 Key Benefits of Contactless Payments for Retail Stores – Omnichannel payments at the Point Of Sale | Sensepass
- InStore – Omnichannel payments at the Point Of Sale | Sensepass
- Understanding Mobile Payment Advantages for Businesses – Omnichannel payments at the Point Of Sale | Sensepass
- Optimise WooCommerce Checkout for Higher UK Conversions – WPCTO
- Ecommerce Growth Workflow for Faster Multichannel Success – Reddog Consulting Group

 New York Office
260 Madison Ave Suite 8018 New York NY 10016

