
Integrate online payments for retail: omnichannel guide
April 23, 2026
TL;DR:
- Omnichannel payment integration can boost retail sales by 20 and lower costs by 31 percent.
- Proper preparation, testing, and continuous optimization are crucial for successful payment system integration.
- Viewing payments as strategic infrastructure enables retailers to improve authorization rates, customer experience, and scalability.
Retailers running disconnected payment systems leave money on the table every single day. Slow checkouts frustrate customers, missed payment methods push shoppers to competitors, and siloed data makes it nearly impossible to track performance across channels. The good news? Omnichannel payment integration delivers a 20% sales increase, 1.7x higher customer lifetime value, and 31% lower fulfillment costs. This guide walks you through every stage: from assessing your current setup and preparing your tech stack, to executing integration and optimizing ongoing performance. Each section gives you practical steps you can act on immediately.
Table of Contents
- Assess your payment integration needs
- Prepare for integration: Technical and operational requirements
- Execute the integration: Step-by-step process
- Verify results and optimize ongoing performance
- Why most retailers miss out on true omnichannel integration
- Get started with SensePass for seamless payment integration
- Frequently asked questions
Key Takeaways
| Point | Details |
|---|---|
| Boost sales and retention | Integrated payments across all channels increase sales and customer lifetime value. |
| Optimize operations | Omnichannel payment integration leads to cost savings and more efficient fulfillment. |
| Avoid technical pitfalls | Proper API setup, idempotency, and cross-channel monitoring prevent costly errors. |
| Ongoing monitoring matters | Continuous optimization with AI/ML minimizes fraud and keeps processes efficient. |
Assess your payment integration needs
Before you touch a single API or reconfigure your point-of-sale system, you need a clear picture of where you stand today. What payment methods do your customers expect? Where do transactions fail or slow down? Which channels operate in silos right now? Answering these questions shapes every decision that follows.
Start by mapping your current customer journey across every touchpoint: in-store, mobile, online, and call center. Note where payment options differ or where checkout steps feel inconsistent. Customers who get a seamless experience in your app but hit friction at the register will notice, and some will walk.
Key factors to evaluate before choosing an integration path:
- Desired customer experience: Do you need one-tap mobile checkout, buy now pay later (BNPL) options, or crypto acceptance?
- Cross-channel consistency: Are loyalty points, coupons, and order history visible regardless of where a customer shops?
- Compatible payment options: Which digital wallets, card networks, and alternative methods do your top customer segments actually use?
- System compatibility: Does your existing POS or eCommerce platform support the integrations you need?
Understanding the difference between multichannel and omnichannel is critical here. Multichannel means accepting payments in multiple places. Omnichannel means those places are connected: inventory, customer data, and payment records flow together. That distinction matters for integration complexity and long-term ROI.
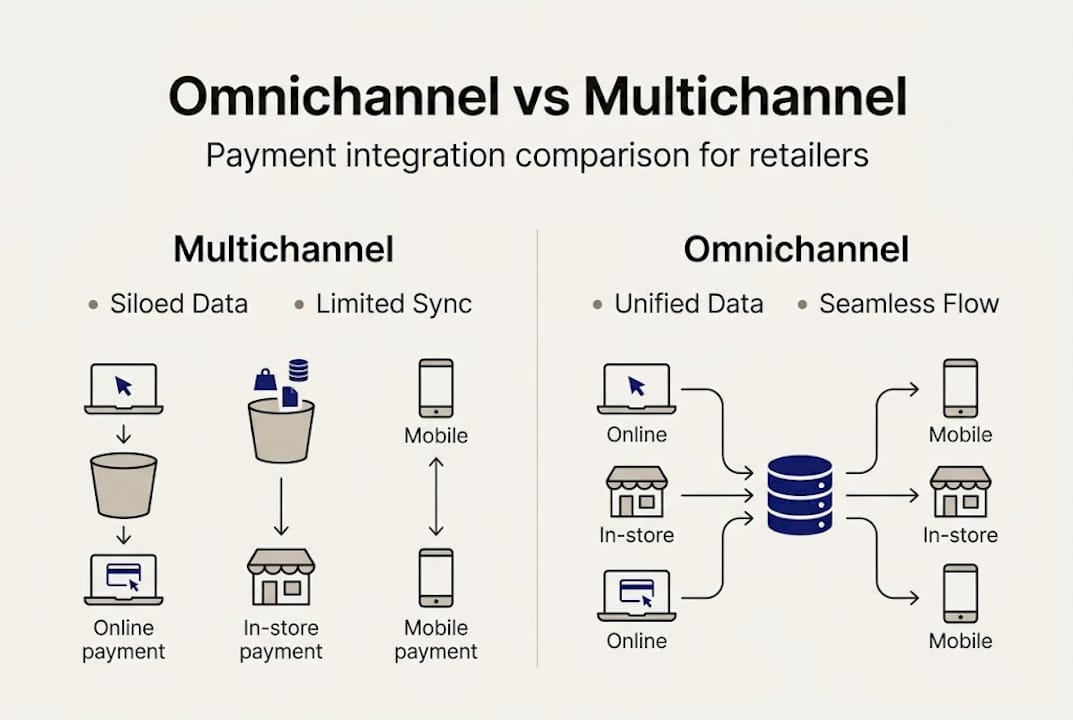
| Feature | Multichannel | Omnichannel |
|---|---|---|
| Payment data | Siloed per channel | Unified across channels |
| Customer view | Fragmented | Single profile |
| Checkout consistency | Varies by channel | Consistent everywhere |
| Reporting | Per-channel only | Cross-channel analytics |
Payment leaders offer 38% more sophisticated payment mixes compared to their peers and prioritize mobile-first, multi-currency processing under two seconds. That benchmark matters because 60% of cart abandonments trace back to slow or limited checkouts. Explore how omnichannel payments for retailers can address these gaps, and review the omnichannel commerce overview if you want a broader strategic framework.
Pro Tip: Survey your top 20% of customers about their preferred payment methods before integration. You may discover that a segment heavily uses PayPal, Venmo, or Klarna, and supporting those methods could meaningfully lift conversion.
Prepare for integration: Technical and operational requirements
Once your needs are clear, the next step is preparing the technical and operational foundations for integration. This stage often gets underestimated. Retailers focus on the shiny front-end experience and overlook the plumbing that makes it work reliably at scale.
On the technical side, your preparation checklist should cover:
- Hardware: Are your terminals NFC-enabled for Apple Pay and Google Pay? Do your mobile POS devices support the latest card-present standards?
- Gateway APIs: Does your payment gateway expose RESTful APIs with proper sandbox environments for testing?
- Middleware: If you’re connecting multiple systems (ERP, CRM, eCommerce), you may need a middleware layer or orchestration platform to route transactions correctly.
- Security and compliance: PCI DSS compliance is non-negotiable. Confirm your stack supports tokenization and end-to-end encryption.
On the operational side, integration is not just a tech project. Staff training, updated settlement workflows, and clear escalation paths for payment failures are just as important. A beautifully integrated system fails in practice if your team doesn’t know how to handle a declined transaction across channels.
| Channel | Key requirement | Common gap |
|---|---|---|
| In-store POS | NFC terminals, EMV chip readers | Outdated hardware |
| eCommerce | API gateway, fraud tools | Missing alternative methods |
| Mobile app | SDK integration, biometric auth | Poor UX at checkout |
| Call center | Virtual terminal, PCI scope | Agent training gaps |
| Self-checkout | Real-time processing, fallback flows | No offline mode |
Well-executed omnichannel payments reduce payment costs by 26%, cut cross-border costs by 59%, and lower fulfillment costs by 31%. These numbers reflect what’s possible when your infrastructure is built correctly from the start. Review payment processing best practices to benchmark your current setup, and see what purpose-built payment solutions for retail look like in practice.
Pro Tip: Build a requirements matrix before talking to any vendor. List every channel, every payment method you want to support, and every compliance requirement. This prevents scope creep and gives vendors a clear brief to work from.
Execute the integration: Step-by-step process
With all tools and requirements ready, you’re set to begin the integration process with confidence. This is where planning turns into action, and where small oversights create big problems later. Move methodically.
- Select your platform and gateway. Choose a payment gateway that connects to your existing POS and eCommerce stack. Platforms like NetSuite, Oracle Xstore, Aptos, Shopify POS, BigCommerce, Storis, NCR, and Dynamics365 all have documented integration paths. Confirm your gateway supports the payment methods your customers need.
- Configure your API connections. Use sandbox environments to set up each API endpoint. Test authentication, transaction requests, and error responses before touching production data.
- Link channels to a unified data layer. Route all transactions through a single orchestration layer so customer records, inventory, and payment data stay synchronized across every touchpoint.
- Implement customer-facing features. Configure your checkout UI to display the right payment options per channel: digital wallets like Apple Pay, Google Pay, PayPal, Alipay, and Amazon Pay for mobile; BNPL options like Klarna, Afterpay, Sezzle, ZIP, and Splitit for higher-ticket purchases; and crypto options via BitPay or Coinbase where relevant.
- Test every edge case before launch. This step separates successful integrations from costly failures.
Common pitfall warning: Webhook retries are one of the most overlooked failure points. If your system processes the same webhook twice, you can charge a customer twice. Implement idempotency keys for every webhook handler. Also, currency conversion in refunds carries real risk: if exchange rates shift between purchase and refund, you may owe more than you collected. And payment method availability varies significantly by country, so always check coverage before enabling a method globally.
- Run end-to-end QA. Simulate successful payments, declines, timeouts, and refunds across every channel. Involve real staff in testing to catch usability issues.
Pro Tip: Follow payment gateway best practices when configuring routing rules. Intelligent routing can improve authorization rates by directing transactions to the processor most likely to approve them, which directly impacts revenue. Learn more about why omnichannel payment matters to keep your team aligned on the strategic goal.
Verify results and optimize ongoing performance
With integration complete, it’s essential to systematically verify and refine your system for lasting success. Going live is not the finish line. It’s the starting line for continuous improvement.
Start by establishing your core monitoring metrics:
- Transaction speed: Average time from payment initiation to authorization confirmation (target under two seconds)
- Error rates: Declined transactions, gateway timeouts, and failed webhooks by channel
- Abandonment rates: Where in the checkout flow do customers drop off?
- Customer satisfaction scores: Post-purchase surveys and support ticket volume related to payment issues
- Chargeback rates: A direct signal of fraud risk and process gaps
Once you have baseline data, move to optimization. Rules-based fraud detection is the most common approach, but AI and machine learning tools reduce chargebacks by 62% compared to static rules. That’s not a marginal gain. It’s a structural improvement in profitability.
Automation also plays a role beyond fraud. Automated reconciliation reduces manual settlement errors. Automated retries for soft declines recover revenue that would otherwise be lost. Scheduled audits of your payment method mix ensure you’re keeping pace with shifting customer preferences.
| Optimization area | Action | Expected impact |
|---|---|---|
| Fraud detection | Implement AI/ML models | 62% chargeback reduction |
| Decline recovery | Automated retry logic | 5-15% revenue recovery |
| Checkout speed | Optimize API response times | Lower abandonment rates |
| Payment mix | Add BNPL and digital wallets | Higher average order value |
| Reporting | Cross-channel analytics dashboard | Faster business decisions |
Use the omnichannel retail guide to benchmark your performance against industry standards, and apply gateway selection tips if you find your current processor is limiting your authorization rates or adding unnecessary cost.
Why most retailers miss out on true omnichannel integration
Here’s the uncomfortable truth: most retailers treat payment as a feature to bolt on, not as infrastructure to build around. They integrate a gateway, flip the switch, and move on. Then they wonder why authorization rates stay flat, chargebacks creep up, and customers still complain about checkout friction.
The retailers who gain a real competitive edge view payments as a strategic layer of their business. They monitor it continuously, optimize it deliberately, and treat it the same way they treat inventory or logistics. Embedded payments as infrastructure versus a product feature requires vertical integration and ongoing investment, not a one-time setup.
AI and ML tools reduce fraud, recover declined transactions, and surface insights that rules-based systems simply cannot. Retailers who invest here don’t just save money; they build a payment layer that scales with growth. If you want a practical starting point, review our top payment tips for actionable frameworks you can apply today.
Get started with SensePass for seamless payment integration
If you’re ready to move from disconnected payment systems to a unified, high-performance setup, SensePass is built for exactly that.

SensePass is a processor-agnostic orchestration layer that connects your retail channels to 50+ card processors and a broad spectrum of payment methods: digital wallets (PayPal, Venmo, WeChat, Apple Pay, Google Pay, Alipay, Amazon Pay), BNPL options (Klarna, Sezzle, ZIP, Splitit, Afterpay), financing via WeGetFinancing and Affirm, crypto through BitPay and Coinbase, and Pay by Bank via Trustly and LinkMoney. We integrate natively with NetSuite, SuiteCommerce, Oracle Xstore, Aptos, Shopify POS, BigCommerce, Storis, NCR, Dynamics365, and more. Explore our omnichannel payment solutions, review gateway selection strategies, or get a full picture at our omnichannel payment overview.
Frequently asked questions
How does omnichannel payment integration improve retail sales?
Omnichannel payment integration increases sales by 20%, boosts customer lifetime value by 1.7x, and cuts fulfillment costs by 31% by making transactions smooth and consistent across every channel.
What are the main technical requirements for integrating online payments?
You need NFC-capable hardware, gateway APIs with sandbox environments, PCI DSS compliance, tokenization support, and trained staff to handle cross-channel payment flows without gaps.
How can I prevent payment failures during integration?
Implement idempotency keys for all webhook handlers, manage currency conversion risks in refund flows carefully, and always verify payment method availability country by country before enabling global rollout.
What ongoing optimizations should retailers make to payment integrations?
Monitor transaction speed, error rates, and abandonment continuously, and layer in AI tools that reduce chargebacks by 62% compared to static rules-based detection systems.
Recommended
- Payment Gateway Selection Tips for Retail Success – Omnichannel payments at the Point Of Sale | Sensepass
- Payment Gateway Selection Tips for Retail Success – Omnichannel payments at the Point Of Sale | Sensepass
- Master Payment Processing Best Practices for Your Business – Omnichannel payments at the Point Of Sale | Sensepass
- Complete Guide to Omnichannel Payments for Retailers – Omnichannel payments at the Point Of Sale | Sensepass
- Customer experience automation: a guide to seamless e-commerce CX | SuperSocial Blog

 New York Office
260 Madison Ave Suite 8018 New York NY 10016

