
Offering Financing at Checkout: A Retailer’s 2026 Guide
July 3, 2026
TL;DR:
- Offering checkout financing increases sales and order values while enabling merchants to receive full payment within 24 to 48 hours. The program requires careful provider selection, seamless integration, compliance, and active marketing from product pages onward. Proper implementation eliminates credit risk and minimizes customer abandonment, driving long-term revenue growth.
Checkout financing is defined as a payment arrangement where customers split a purchase into installments while the merchant receives the full invoice amount upfront from a lending partner. This guide to offering financing at checkout covers everything retailers and eCommerce businesses need to act: provider selection, technical integration, compliance, and performance measurement. Merchants implementing checkout financing report 20–30% higher sales conversion and 30–50% growth in average order values. The lender assumes all credit and collection risk, so you get paid in full within 24–48 hours and carry zero exposure to customer default. Platforms like Sensepass make this practical by connecting financing options like WeGetFinancing and Affirm to major POS systems and eCommerce platforms in a single integration.
What do you need before offering financing at checkout?
Preparation determines whether your financing program drives revenue or creates friction. Start by reviewing your customer demographics and average transaction values. Financing options deliver the strongest lift on purchases above $200, where the gap between “I want it” and “I can afford it right now” is widest.
Understanding the financing models available
Three models dominate retail checkout financing:
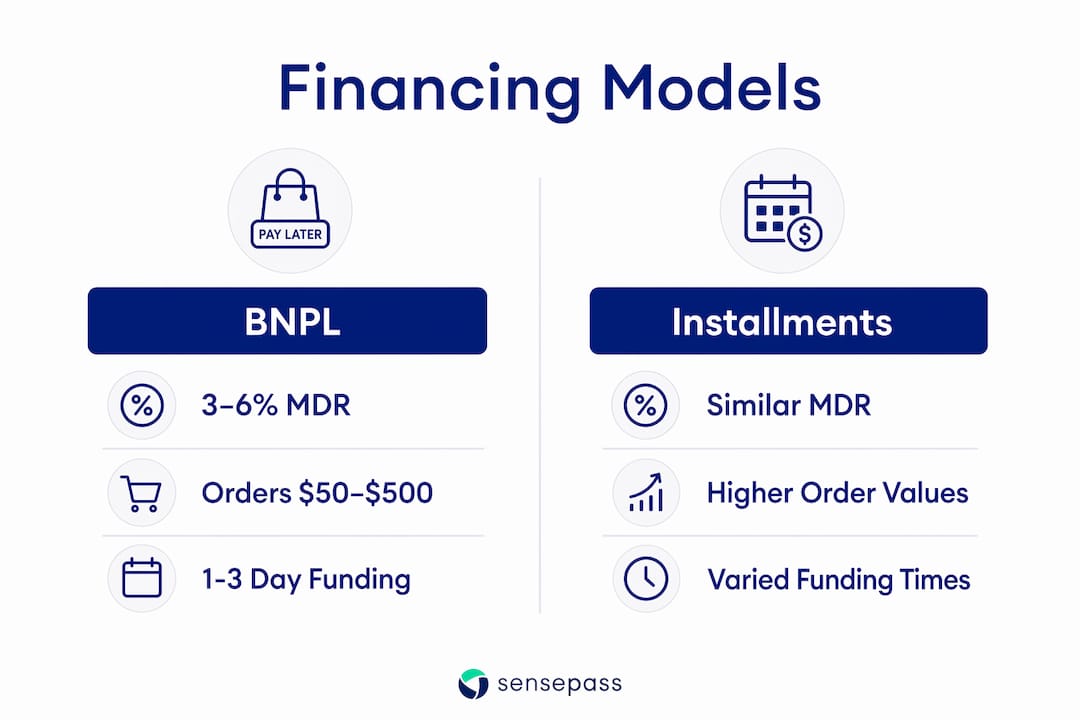
- Buy Now Pay Later (BNPL): Short-term, often interest-free installments. Providers like Klarna, Afterpay, Sezzle, ZIP, and Splitit fall here. Best for fashion, electronics, and home goods.
- Installment loans: Longer terms with interest, typically 6–36 months. Providers like Affirm and WeGetFinancing cover higher-ticket purchases in furniture, appliances, and specialty retail.
- Point-of-sale credit: A revolving credit line issued at checkout. Less common but effective for repeat-purchase categories.
Each model carries a different Merchant Discount Rate. BNPL and installment providers charge merchants 3–6% per transaction. That fee replaces your credit risk and collection overhead entirely.
| Financing type | Typical MDR | Best for | Funding timeline |
|---|---|---|---|
| BNPL | 3–6% | Orders $50–$500 | 24–48 hours |
| Installment loan | 3–6% | Orders $500+ | 24–48 hours |
| POS revolving credit | Varies | High-frequency buyers | 24–48 hours |
Technical requirements for integration
Your POS software and eCommerce platform must support the financing provider’s API or SDK. Most providers offer pre-built plugins for Shopify POS, BigCommerce, and WooCommerce. For enterprise environments running NetSuite, Oracle Xstore, or Dynamics365, you need a payment orchestration layer that handles routing without custom development for each provider.
Sensepass integrates with NetSuite, SuiteCommerce, Oracle Xstore, Aptos, Shopify POS, BigCommerce, Storis, NCR, Dynamics365, and more. It connects financing options alongside digital wallets like PayPal, Venmo, Apple Pay, Google Pay, Alipay, and Amazon Pay, plus crypto payments via BitPay and Coinbase, and Pay by Bank options like Trustly and LinkMoney. Sensepass is also processor-agnostic, giving you access to 50+ card processors. That architecture means you add financing without rebuilding your existing payment stack.
Pro Tip: Before signing with any financing provider, confirm they support your specific POS version. A mismatch at the API level can delay your launch by weeks.
How to implement checkout financing step by step
A structured rollout prevents the most common launch failures. Follow this sequence to go live cleanly.
-
Partner with a regulated provider. Review commercial terms carefully: MDR, approval rates by customer segment, funding timelines, and dispute resolution. Confirm the provider holds the required lending licenses in every state or country where you sell.
-
Integrate across all sales channels. Online, in-store, and call center channels each need separate configuration. Use a retail financing setup process that maps each channel to the correct API endpoint. Omnichannel consistency matters because customers switch channels mid-purchase.
-
Configure the checkout user experience. Display financing offers on product pages, not just at the final payment step. Placing financing early in the shopping journey captures buyer intent before cart abandonment occurs. Show estimated monthly payments next to the product price. A line like “From $42/month with Affirm” on a $499 item changes the buying decision before the customer even adds to cart.
-
Train your staff. Well-trained in-store staff who mention financing confidently and early in the sales conversation increase program adoption significantly. Train your team to introduce financing as a convenience, not a last resort for customers who hesitate on price. Avoid high-pressure tactics. The goal is informed choice, not manipulation.
-
Test the full lifecycle before launch. Run the complete approval flow, a successful purchase, a payment decline, an order cancellation, and a customer support case. Each scenario must resolve cleanly. Gaps in any of these paths damage customer trust and generate chargebacks.
-
Go live with compliance-ready messaging. Every touchpoint displaying financing terms must include clear disclosures: eligibility criteria, interest rate, fees, and repayment schedule. Balanced disclosure is not optional. It protects your customers and your brand.
Pro Tip: Run a soft launch with a single product category first. Measure approval rates and conversion lift for two weeks before rolling out site-wide. You will catch integration issues with minimal customer impact.
Merchants receive the full payment upfront within 24–48 hours after customer approval. That speed eliminates the cash flow gap that installment billing would otherwise create.
What mistakes should retailers avoid with checkout financing?
Most financing program failures trace back to a small set of avoidable errors. Knowing them in advance saves you from costly fixes post-launch.
-
Highlighting low monthly payments without full disclosure. Promoting “$0 down, $29/month” without stating the APR and total repayment amount violates consumer finance regulations. Clear, balanced disclosures stating eligibility, interest rates, fees, and repayment terms are required. Regulatory scrutiny in this area is increasing, and fines are significant.
-
Burying financing offers at the final checkout step. Customers who reach the payment page without knowing financing is available have already formed a price objection. Move financing messaging to product pages and the cart stage.
-
Skipping edge-case testing. End-to-end lifecycle testing including payment declines, cancellations, and support interactions is critical before launch. A customer whose financing application is declined with no clear next step will abandon and not return.
-
Ignoring margin impact on low-ticket items. A 5% MDR on a $30 item with a 20% gross margin eliminates a quarter of your profit. Model the MDR fee against your margin before enabling financing on every product category.
-
Undertrained staff creating mis-selling risk. A staff member who describes financing incorrectly creates liability. Regular refresher training and clear written scripts reduce this risk.
“Retailers who treat financing as an active marketing channel, not just a payment option, see the strongest long-term results. The checkout is the last step. The financing offer needs to start on the product page.”
Use customer feedback collection after launch to identify friction points in the financing flow that your internal testing missed. Customers who attempted financing but did not complete it are your most valuable source of improvement data.
What are the measurable benefits of offering financing at checkout?
The business case for checkout financing is well-documented. Retailers implementing financing report conversion lifts of 20–30%, average order value increases of 30–50%, and cart abandonment reductions of up to 28%. Each of those metrics compounds: more customers completing purchase, spending more per order, at a higher close rate.
| Metric | Reported impact |
|---|---|
| Sales conversion rate | +20–30% |
| Average order value | +30–50% |
| Cart abandonment | Reduced up to 28% |
| Merchant funding timeline | 24–48 hours |
| Merchant Discount Rate | 3–6% per transaction |
The MDR cost is real, but the math typically favors financing. A 5% MDR on a transaction that would not have happened without financing is a net gain. The more relevant calculation is whether financing converts marginal buyers, not whether it costs more than a standard card transaction.
Consumer financing options like BNPL let shoppers split payments while merchants pay the MDR and receive full payment upfront. That structure means you never wait for installments to clear. Your cash flow stays predictable regardless of how the customer repays the lender.
Ongoing optimization matters as much as the initial launch. Integrate financing offer performance into your regular marketing reporting. Track approval rates by product category, financing adoption by traffic source, and AOV by financing type. Use those signals to adjust which products display financing prominently and which financing providers you prioritize.
Pro Tip: Connect your financing program data to your email marketing platform. Customers who used financing once are strong candidates for repeat financing offers on their next purchase. An eCommerce retention strategy that includes financing reminders can materially lift repeat purchase rates.
Key Takeaways
Offering financing at checkout increases conversion, raises average order values, and eliminates credit risk for merchants, provided the program is integrated across all channels, disclosed compliantly, and actively marketed from the product page forward.
| Point | Details |
|---|---|
| Financing lifts key metrics | Merchants report 20–30% conversion gains and 30–50% higher average order values. |
| Merchants get paid upfront | Lenders fund the full invoice within 24–48 hours; merchants carry zero collection risk. |
| MDR fees require margin modeling | The 3–6% MDR must be modeled against product margins before enabling financing on every SKU. |
| Early placement drives adoption | Showing financing on product pages, not just at checkout, captures intent before abandonment. |
| Compliance is non-negotiable | Every financing touchpoint must display clear, balanced disclosures covering rates, fees, and terms. |
Why I think most retailers get checkout financing backwards
Most retailers I’ve worked with treat financing as a payment method. They add it to the checkout page, call it done, and wonder why adoption is low. The insight that changes everything is simple: financing is a marketing tool that happens to live at checkout.
The retailers who see the strongest results put financing messaging on product pages, in email campaigns, and in staff scripts from the first moment a customer expresses interest. By the time that customer reaches checkout, financing feels like the obvious choice, not a new option they’re seeing for the first time.
Compliance is the other area where I see retailers cut corners and pay for it later. Showing a low monthly payment without the full terms is not a gray area. It’s a regulatory violation. The brands that build long-term trust are the ones that show the full picture and let the math speak for itself.
My practical recommendation: start with one financing provider on your highest-AOV product category. Measure for 30 days. Then expand based on data, not assumptions. And use a platform that gives you the flexibility to add or swap providers without rebuilding your checkout. That flexibility is what separates a financing program that scales from one that stalls.
— Vlad
How Sensepass connects financing to your full payment stack
Sensepass is built for retailers who need financing options to work alongside every other payment method, across every channel, without custom development for each integration.

Sensepass connects to NetSuite, SuiteCommerce, Oracle Xstore, Aptos, Shopify POS, BigCommerce, Storis, NCR, Dynamics365, and more. It supports financing through WeGetFinancing and Affirm, BNPL via Klarna, Sezzle, ZIP, Splitit, and Afterpay, digital wallets including PayPal, Venmo, WeChat, Apple Pay, Google Pay, Alipay, and Amazon Pay, crypto payments through BitPay and Coinbase, and Pay by Bank via Trustly and LinkMoney. As a processor-agnostic platform with access to 50+ card processors, Sensepass gives you maximum flexibility without locking you into a single provider. Explore Sensepass’s omnichannel payment solutions to see how financing fits into your complete checkout architecture.
FAQ
What is checkout financing for retailers?
Checkout financing is a payment option where customers pay for purchases in installments while the merchant receives the full payment upfront from a lending partner. The lender assumes all credit and collection risk.
How much does offering financing at checkout cost?
Merchants pay a Merchant Discount Rate of 3–6% per transaction to the financing provider. This fee replaces the cost and risk of carrying customer credit in-house.
How quickly do merchants get paid with checkout financing?
Merchants typically receive full payment within 24–48 hours of customer approval, regardless of the customer’s repayment schedule with the lender.
What compliance rules apply to checkout financing?
Every financing touchpoint must include clear disclosures covering eligibility, interest rates, fees, and repayment terms. Promoting low monthly payments without full terms risks regulatory action.
Does checkout financing work for in-store and online sales?
Yes. Financing options can be configured for online checkout, in-store POS, and call center channels. Platforms like Sensepass support omnichannel financing integration across all three environments from a single setup.
Recommended
- Retail Financing Option Setup Steps for Retailers – Omnichannel payments at the Point Of Sale | Sensepass
- Stepwise Flexible Checkout Process: 2026 Retail Guide – Omnichannel payments at the Point Of Sale | Sensepass
- Your Guide to Flexible Payment Options in Retail – Omnichannel payments at the Point Of Sale | Sensepass
- Master Payment Processing Best Practices for Your Business – Omnichannel payments at the Point Of Sale | Sensepass

 New York Office
260 Madison Ave Suite 8018 New York NY 10016

