
Optimize fashion retail payments: 20-30% sales boost proven
March 26, 2026
Fashion retailers lose billions annually to payment failures and cart abandonment. Studies show that payment failure rates average 15-20%, costing the industry $47 billion globally each year. When customers encounter declined transactions or clunky checkout experiences across channels, they abandon purchases and rarely return. Integrating omnichannel payment solutions addresses these challenges by creating unified, seamless transaction experiences that reduce declines, boost authorization rates, and increase customer lifetime value. This guide walks you through preparing, executing, and verifying an optimized payment system that transforms how your fashion business captures revenue.
Table of Contents
- Key takeaways
- Understanding payment challenges in fashion retail
- Preparing for payment optimization in fashion retail
- Executing omnichannel payment integration effectively
- Verifying results and optimizing payment performance
- Enhance your fashion retail payments with Sensepass
- Frequently asked questions
Key Takeaways
| Point | Details |
|---|---|
| Omnichannel integration | Unified payment experiences across channels reduce declines and increase authorization rates, boosting revenue and customer lifetime value. |
| Gateway selection impact | Choosing the right gateways and implementing payment orchestration significantly improves authorization success and lowers declines. |
| Resilience to edge cases | Design systems to prevent double clicks and cope with slow connections to protect revenue and maintain trust. |
| Failure analytics by customer type | Track failure reasons separately for new and returning customers to target optimization where it matters most. |
Understanding payment challenges in fashion retail
Fashion ecommerce faces distinctive payment obstacles that directly impact your bottom line. High cart abandonment rates stem from payment failures, while product returns create complex refund scenarios that strain processing systems. Understanding these challenges helps you build resilient payment infrastructure.
Payment failure rates average 15-20% across ecommerce globally, causing $47 billion in annual revenue leakage. Fashion retail experiences particularly high failure rates due to return rates of 20-30%, which complicate authorization decisions and fraud detection. Every declined transaction represents lost revenue and damaged customer trust. When shoppers encounter payment issues, 70% never complete their purchase.
Conversion rates vary significantly across fashion segments. Fashion ecommerce conversion rates median 2.4%, but luxury brands often see lower rates between 0.8-1.4% due to higher price points and longer consideration cycles. Mass market fashion typically converts at 2-3%, while fast fashion can reach 3-5%. These benchmarks highlight how payment friction disproportionately affects conversion in different retail segments.
Returns create unique payment processing challenges in fashion retail:
- Processing refunds to original payment methods increases costs and delays customer satisfaction
- Store credit options require integrated systems to track and apply across channels
- Exchanges demand flexible payment adjustments when price differences exist
- Fraud concerns rise with high return rates, triggering false declines on legitimate purchases
Modern consumers expect unified payment experiences across every touchpoint. They want to start a purchase on mobile, complete it in-store, and use the same saved payment methods everywhere. Fragmented systems that require re-entering payment details or offer different payment options per channel create frustration and abandonment. Payment gateway selection directly impacts your ability to deliver this seamless experience.
Pro Tip: Track payment failure reasons separately for new versus returning customers. New customers often experience higher decline rates due to fraud filters, while returning customers face issues with expired cards or changed billing addresses. This segmentation reveals where to focus optimization efforts.
Preparing for payment optimization in fashion retail
Successful payment optimization starts with strategic preparation. You need to audit existing systems, select appropriate gateways, and ensure compliance before integration begins. This groundwork determines whether your implementation succeeds or creates new problems.
Start by reviewing your current payment infrastructure across all channels. Map every payment touchpoint: online checkout, mobile app, in-store POS, call center, and any subscription services. Identify inconsistencies where different systems handle transactions separately. Unified gateways eliminate these silos and create consistent customer experiences while simplifying reconciliation and reporting.
Gateway selection depends on your specific retail segment and transaction volume. Consider these factors:
- Transaction fees and monthly costs relative to your volume
- Support for payment methods your customers prefer
- Authorization rates in your geographic markets
- Integration complexity with your existing POS and ecommerce platforms
- Compliance certifications for security standards
Payment orchestration routes transactions to optimal processors based on real-time criteria, improving authorization rates. Instead of sending all transactions through a single gateway, orchestration layers analyze factors like customer location, payment method, transaction amount, and processor performance to select the best routing path. This intelligence reduces declines and maximizes approval rates.
| Preparation Element | Purpose | Timeline |
|---|---|---|
| System audit | Identify integration points and data flows | 1-2 weeks |
| Gateway evaluation | Compare fees, features, and authorization rates | 2-3 weeks |
| Compliance review | Ensure PSD2, SCA, and PCI DSS readiness | 2-4 weeks |
| Testing environment setup | Create sandbox for integration testing | 1 week |
Security compliance is non-negotiable in payment processing. Strong Customer Authentication (SCA) requirements under PSD2 mandate two-factor authentication for many transactions in Europe. Implementing SCA correctly prevents legitimate transactions from being declined while maintaining fraud protection. Retail payment security requires balancing friction reduction with risk management.
Emerging payment methods like Buy Now Pay Later (BNPL) significantly impact fashion retail conversion rates. BNPL options appeal to younger consumers and enable higher average order values by spreading payments over time. However, BNPL is a business decision based on your customer segments, margins, and risk tolerance. Luxury brands may avoid BNPL to maintain exclusivity, while mass market retailers embrace it to compete.
Pro Tip: Create a payment method priority matrix based on customer demographics and purchase patterns. Not every payment option suits every fashion segment. Use analytics to identify which methods your highest-value customers prefer, then optimize those experiences first.
Omnichannel payment solutions unify online, mobile, and in-store transactions through integrated platforms. This preparation phase establishes the foundation for seamless customer experiences and operational efficiency.
Executing omnichannel payment integration effectively
Integration execution requires methodical steps and attention to edge cases that break customer experiences. Follow this process to implement payment optimization while avoiding common pitfalls that cause post-launch issues.
Step-by-step integration process:
- Establish unified API connections between your payment gateway and all transaction endpoints (ecommerce platform, POS systems, mobile apps, call center software)
- Configure payment routing rules in your orchestration layer based on transaction characteristics, customer location, and processor performance metrics
- Implement tokenization to securely store payment credentials for returning customers across all channels
- Set up real-time analytics dashboards to monitor authorization rates, decline reasons, and transaction flows
- Create comprehensive test scenarios covering standard purchases, refunds, exchanges, partial payments, and multi-channel transactions
- Deploy gradually starting with a small percentage of traffic, monitoring closely before full rollout
Edge cases like double-click payments, slow internet connections, and high-load periods require resilient design. Prevent double charges by implementing idempotency keys that identify duplicate requests. Display clear error messages when network issues occur, explaining what happened and what action customers should take. Build retry logic that automatically reattempts failed transactions without requiring customer intervention.
| Architecture Type | Pros | Cons | Best For |
|---|---|---|---|
| Direct gateway integration | Lower initial cost, simpler setup | Limited flexibility, single point of failure | Small retailers, single channel |
| Payment orchestration | Optimized routing, multiple processors, higher authorization | Higher complexity, additional cost | Multi-channel retailers, high volume |
| Hybrid approach | Balance cost and flexibility | Requires careful planning | Growing retailers transitioning to omnichannel |
Common integration mistakes destroy customer experiences and waste resources. Ignoring peak load issues causes payment system failures during high-traffic events like sales and product launches. Failing to comply with geo-specific regulations results in blocked transactions in certain markets. Neglecting mobile optimization creates friction for the majority of fashion shoppers who browse and buy on smartphones.
Pro Tip: Test your payment system under realistic load conditions before major sales events. Use load testing tools to simulate 3-5x your normal traffic and identify bottlenecks. Payment systems that work fine at baseline often fail catastrophically during flash sales.
Post-integration analytics reveal optimization opportunities. Monitor authorization rates by payment method, processor, and customer segment. Track where customers drop off in the checkout flow to identify friction points. Payment gateway selection impacts these metrics significantly, so compare performance across different routing strategies.
Payment orchestration routes transactions to processors with the highest approval likelihood based on multiple criteria. This dynamic routing considers customer location, payment method type, transaction amount, time of day, and historical processor performance. The result is measurably higher authorization rates compared to static routing.
Implement clear UI feedback throughout the payment process. Show customers when their payment is processing, when it succeeds, and specific next steps if it fails. Vague error messages like “Payment failed” frustrate customers and increase support costs. Specific guidance like “Your card was declined. Please verify the billing address matches your card statement” empowers customers to resolve issues independently.
Top omnichannel payment tips emphasize consistency across channels while respecting context-specific needs. In-store payments prioritize speed, while online checkout allows more payment method choices. Mobile experiences require thumb-friendly interfaces and minimal typing.
Verifying results and optimizing payment performance
Measuring payment optimization success requires tracking specific metrics and continuously refining your approach. Verification transforms initial improvements into sustained competitive advantages through data-driven iteration.
Track these key performance indicators:
- Cart abandonment rate: Percentage of initiated checkouts not completed, segmented by abandonment stage
- Payment failure rate: Declined transactions as a percentage of authorization attempts, broken down by decline reason
- Authorization success rate: Approved transactions compared to total attempts, tracked by payment method and processor
- Customer lifetime value: Total revenue per customer over their relationship with your brand
- Average order value: Transaction size trends as you introduce flexible payment options
| Metric | Baseline | Target Improvement | Measurement Frequency |
|---|---|---|---|
| Cart abandonment | Industry avg 70% | Reduce to 55-60% | Daily |
| Payment failures | 15-20% | Reduce to 8-12% | Real-time |
| Authorization rate | 80-85% | Increase to 90-95% | Real-time |
| Customer lifetime value | Varies by segment | Increase by 30% | Monthly |
Real-time analytics dashboards enable rapid response to payment issues. When authorization rates suddenly drop for a specific processor or payment method, you can investigate immediately rather than discovering the problem in weekly reports. Set up alerts for anomalies like unusual decline rate spikes or authorization latency increases.
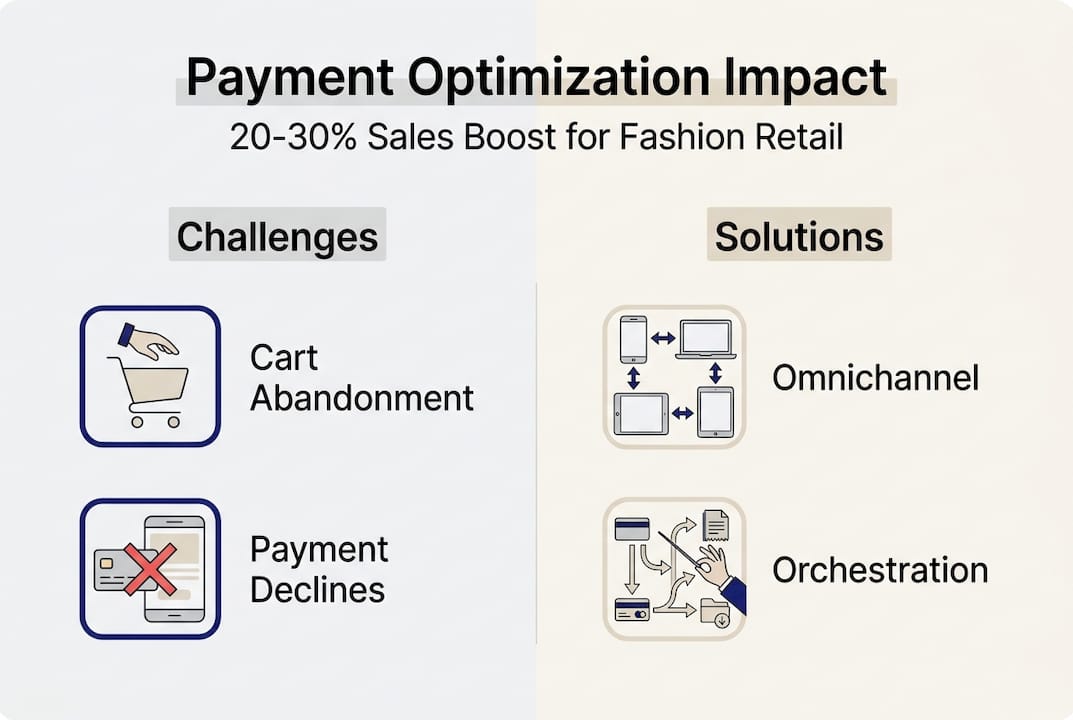
Omnichannel payment integration reduces cart abandonment and boosts sales by 20-30% when implemented effectively. These improvements compound over time as you refine routing rules and expand payment method options based on customer preferences.
Regularly audit payment decline reasons to optimize fraud filters and security rules. Many declines result from overly aggressive fraud detection that blocks legitimate customers. Review false positive rates and adjust risk thresholds based on actual fraud losses versus revenue lost to unnecessary declines. Balance security with customer experience.
Implement feedback loops with customer service teams to identify friction points. Support agents hear directly from frustrated customers about payment issues. Weekly reviews of payment-related support tickets reveal patterns that analytics alone might miss. Common complaints like “My card keeps getting declined” or “I can’t use my preferred payment method” signal optimization opportunities.
Continuously test and update payment methods to meet evolving consumer preferences. Digital wallet adoption grows rapidly, with younger consumers preferring Apple Pay, Google Pay, and PayPal over traditional card entry. BNPL usage spikes during economic uncertainty as customers seek payment flexibility. Monitor adoption rates for each payment method and prioritize optimization for high-growth options.
Pro Tip: Run A/B tests on checkout flow variations to quantify improvement opportunities. Test payment method ordering, form field requirements, and trust signals like security badges. Small changes often yield significant conversion lifts when validated through controlled experiments.
Omnichannel payments require ongoing optimization rather than one-time implementation. Consumer behavior shifts, new payment technologies emerge, and competitive pressures evolve. Retailers who treat payment optimization as a continuous process maintain advantages over competitors who implement once and neglect updates.
Enhance your fashion retail payments with Sensepass
Implementing the strategies outlined in this guide requires robust payment infrastructure designed specifically for fashion retail’s unique challenges. Sensepass delivers omnichannel payment solutions that unify online, in-store, and mobile transactions while supporting the diverse payment methods your customers expect.
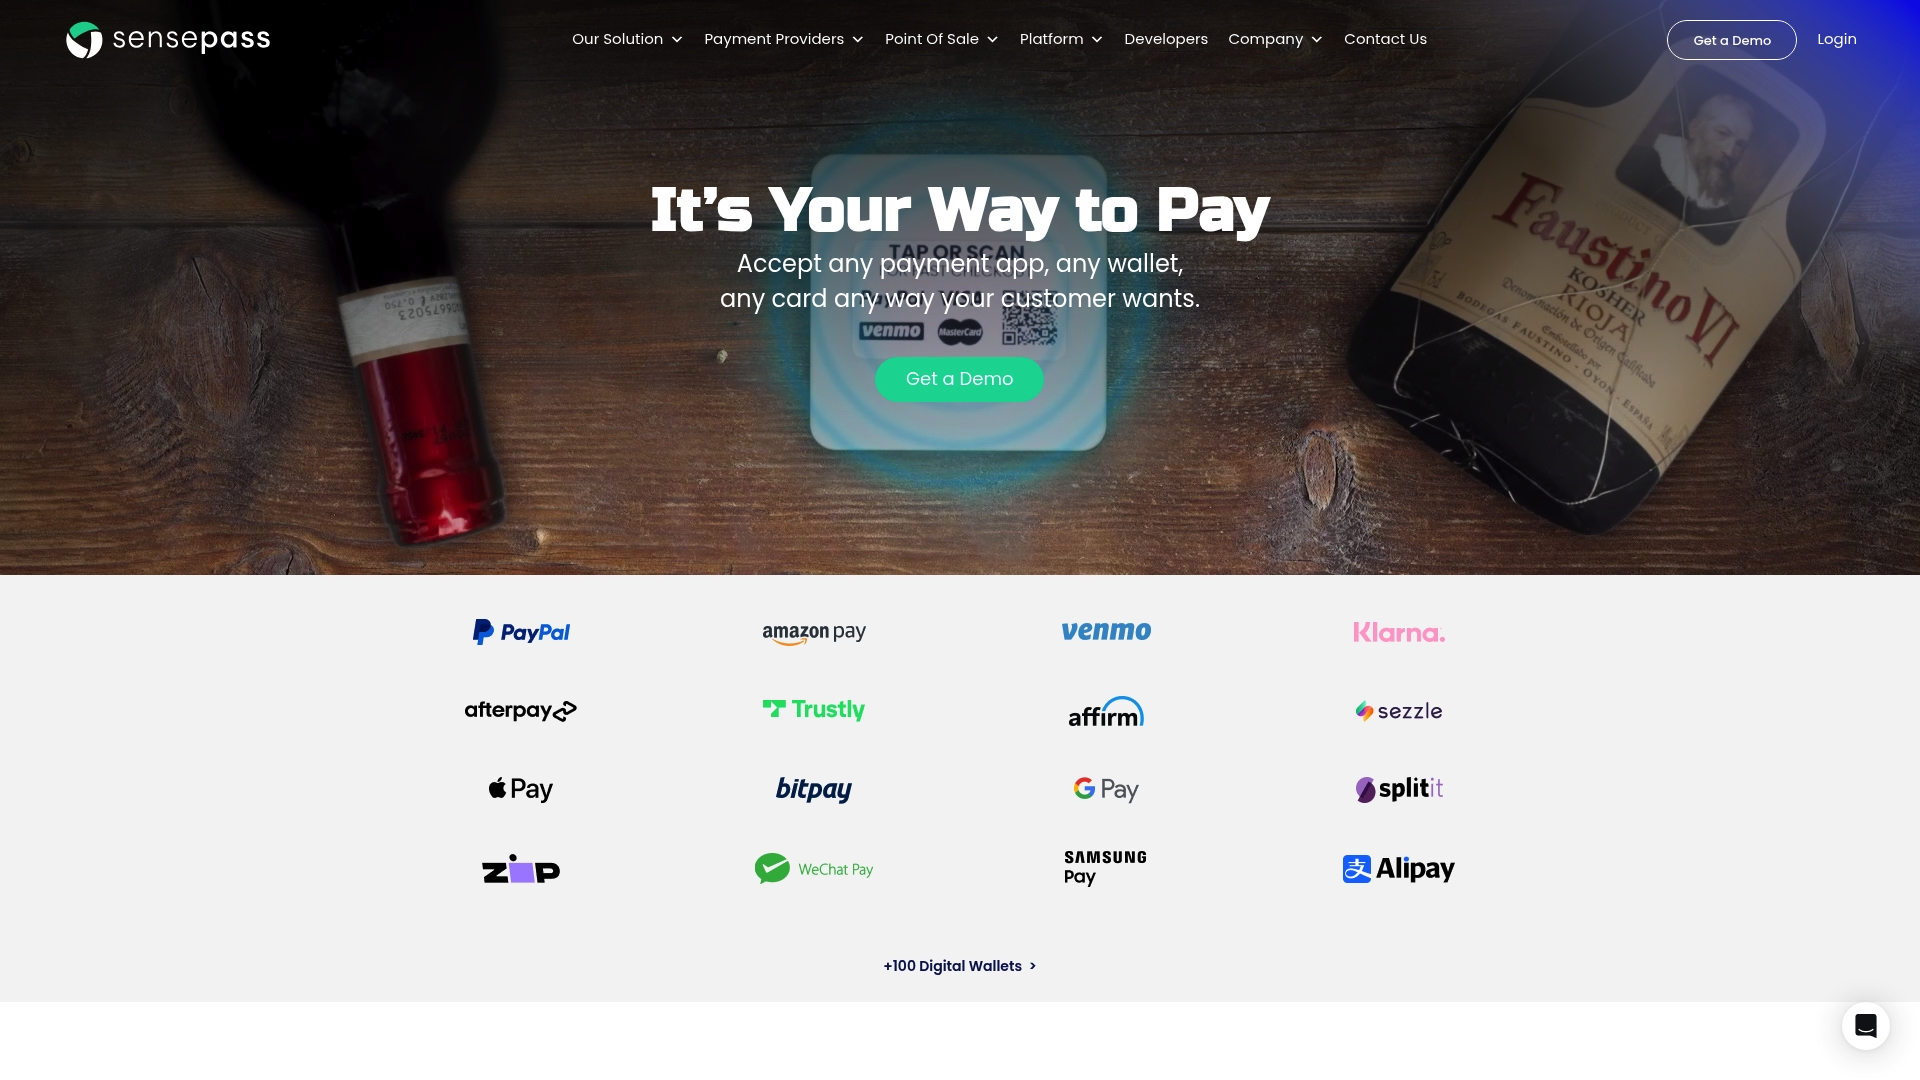
Sensepass integrates seamlessly with major platforms including NetSuite, SuiteCommerce, Oracle Xstore, Aptos, Shopify POS, BigCommerce, Storis, NCR, and Dynamics365. This compatibility ensures smooth implementation regardless of your existing technology stack. The platform supports extensive payment methods: digital wallets like PayPal, Venmo, WeChat, Apple Pay, Google Pay, Alipay, and Amazon Pay; BNPL options including Klarna, Sezzle, ZIP, Splitit, and Afterpay; financing through WeGetFinancing and Affirm; crypto payments via BitPay and Coinbase; and pay by bank solutions like Trustly and LinkMoney. As a processor-agnostic platform, Sensepass lets you choose from 50+ card processors for maximum flexibility and optimized routing.
Omnichannel payment solutions from Sensepass reduce payment failures, increase authorization rates, and deliver the seamless customer experiences that drive loyalty. Explore payment gateway selection strategies and discover top omnichannel payment tips to transform your fashion retail payment performance.
Frequently asked questions
What is omnichannel payment in fashion retail?
Omnichannel payment is a unified system integrating multiple channels like online, mobile, and in-store to create consistent customer experiences. It enables customers to use saved payment methods across all touchpoints, start transactions on one channel and complete them on another, and receive unified loyalty rewards. This integration reduces payment failures by optimizing transaction routing and offering diverse payment methods that match customer preferences.
How does payment orchestration improve authorization rates?
Payment orchestration dynamically routes transactions to processors with the highest approval likelihood based on criteria like customer location, payment method type, transaction amount, and real-time processor performance. This intelligent routing reduces declines by avoiding processors experiencing technical issues or those with lower approval rates for specific transaction types. The result is measurably higher checkout success rates compared to static, single-processor approaches.
What are common edge cases in payment systems and how to handle them?
Common edge cases include double-click payments where customers click submit multiple times, network interruptions that leave transaction status uncertain, and fraud false positives that decline legitimate purchases. Handle double-click scenarios with idempotency keys that identify duplicate requests. Address network issues with clear UI messaging, automatic retries, and transaction status checks. Reduce false positives by fine-tuning fraud detection rules based on decline reason analysis and implementing risk-based authentication that adds friction only for suspicious transactions.
Why do fashion retailers experience higher payment failure rates?
Fashion retail sees elevated failure rates due to high return rates of 20-30%, which complicate fraud detection algorithms and cause legitimate customers to be flagged as risky. International transactions are common as customers purchase from global brands, increasing cross-border decline rates. Higher average order values in luxury fashion trigger more stringent fraud checks. Seasonal traffic spikes during sales events strain payment systems, causing timeout errors and processing delays that result in failed transactions.
How quickly can omnichannel payment optimization impact sales?
Most retailers see measurable improvements within 30-60 days of implementing optimized payment systems. Authorization rate increases appear immediately as better routing reduces declines. Cart abandonment reduction takes 2-4 weeks as customers experience smoother checkout flows. Customer lifetime value growth emerges over 3-6 months as improved payment experiences drive repeat purchases and loyalty. The full 20-30% sales boost typically materializes within one quarter as all optimization elements compound.
Recommended
- Retail payment optimization: 7 steps to boost omnichannel sales – Omnichannel payments at the Point Of Sale | Sensepass
- 7 Key Benefits of Contactless Payments for Retail Stores – Omnichannel payments at the Point Of Sale | Sensepass
- Retail Animation – Omnichannel payments at the Point Of Sale | Sensepass
- Retail – Omnichannel payments at the Point Of Sale | Sensepass
- Smile and Pay TPE | Shifter

 New York Office
260 Madison Ave Suite 8018 New York NY 10016

