
Optimizing BNPL at Checkout: 2026 Merchant Guide
July 23, 2026
The single most effective move you can make for checkout conversion right now is placing BNPL options at equal visual weight alongside credit cards and digital wallets, not buried in an accordion menu. Merchants who treat BNPL as a configurable revenue channel rather than a checkbox feature see significant conversion lifts and average order value increases. The strategies below give you the exact framework to get there.
The core actions that move the needle:
- Place BNPL payment options at the same visual level as credit cards and digital wallets at checkout
- Use native platform plugins rather than third-party wrappers to avoid mobile redirect failures
- Apply dynamic payment sequencing to surface BNPL based on cart value and shopper signals
- Display installment messaging on product pages and cart pages, not only at checkout
- Set a minimum order threshold to protect margins from BNPL fees
- Limit visible BNPL providers to one or two to prevent decision paralysis
- Track BNPL metrics in GA4 by payment method segment, including conversion rate, average order value, return rate, and net margin
What BNPL is and how it works for your store
Buy now, pay later lets customers split a purchase into installments, typically four interest-free payments over six to eight weeks, while you receive the full order amount upfront. The BNPL provider pays you within one to three business days, minus their merchant fee, and then collects the remaining installments from the customer directly. The credit risk sits entirely with the provider.
The checkout flow works like this: the customer selects a BNPL option at payment, the provider runs an instant soft credit check with no impact on the customer’s credit score, approval is granted in seconds, and the customer pays the first installment (usually 25% of the total). You receive the full amount minus the provider’s fee. The provider handles all subsequent collections.
For merchants, the appeal is straightforward. You get paid immediately, you take on no credit risk, and you offer a payment structure that reduces the psychological weight of a large purchase. The trade-off is a merchant fee that runs higher than standard card processing, which is why margin management is central to any well-run BNPL program.
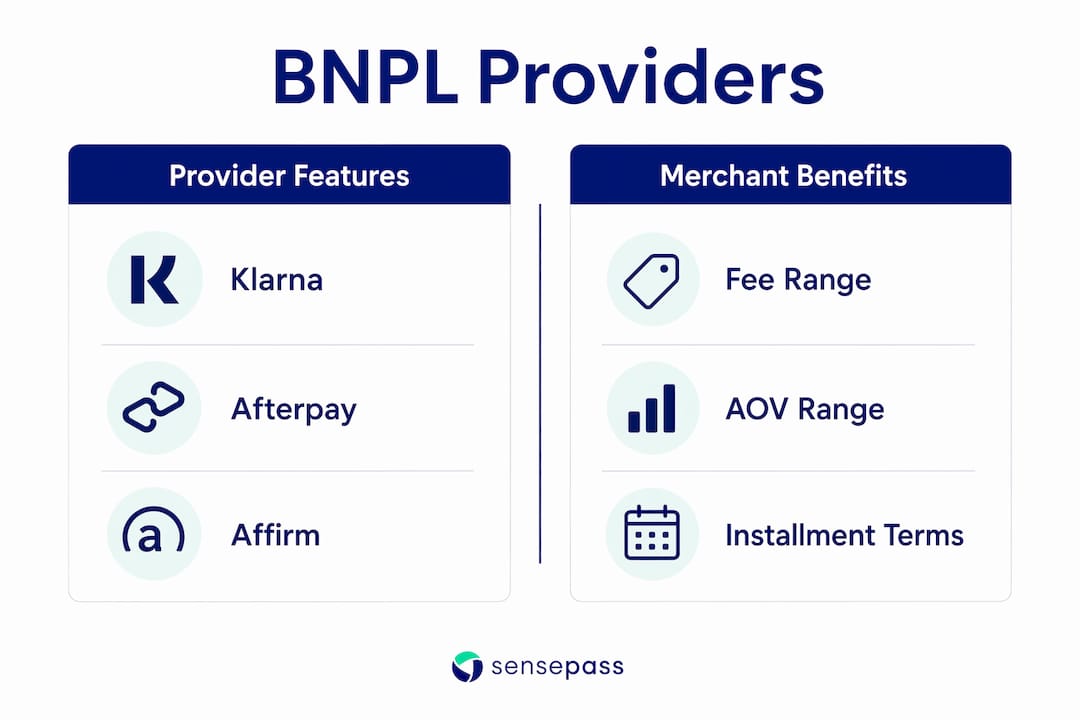
Leading BNPL providers in the US market
Not every provider fits every store. The right choice depends on your average order value, your customer demographics, and how each provider’s fee structure interacts with your margins.
Provider profiles:
- Klarna — Strong with fashion, beauty, and lifestyle merchants. Its sweet spot is for average order values in the mid-range category. Offers Pay in 4, Pay in 30 Days, and monthly financing. Merchant fees typically include a percentage plus a fixed per-transaction fee.
- Afterpay — Four payments over six weeks, with strong recognition among shoppers aged 18–35. Merchant fees typically include a percentage plus a fixed per-transaction fee. Works well for apparel, beauty, and home goods.
- Affirm — Best suited for higher AOV categories. Offers monthly installment terms from 3 to 36 months, making it the natural fit for furniture, electronics, and fitness equipment. Fees vary depending on negotiated rates and financing terms.
- Sezzle — Pay-in-four model with a focus on younger shoppers and mid-market price points. Transparent fee structure and strong approval rates for first-time credit users.
- ZIP — Formerly Quadpay in the US. Four payments over six weeks, with a broad merchant network and solid mobile checkout experience.
- Splitit — Splits purchases across a customer’s existing credit card with no new credit application. Converts well with older, higher-income customers who are cautious about new credit products. Particularly effective for AOVs above $500.
- WeGetFinancing and Affirm (longer-term financing) — Both serve merchants who need extended financing terms beyond six weeks, covering purchases from a few hundred dollars into the thousands.
| Provider | Best AOV Range | Installment Structure | Merchant Fee Range |
|---|---|---|---|
| Klarna | $50–$500 | Pay in 4 / Pay in 30 / Monthly | percentage plus a fixed per-transaction fee |
| Afterpay | $50–$400 | 4 payments / 6 weeks | 4–6% + fixed fee |
| Affirm | $150+ | 3–36 months | — |
| Sezzle | $35–$100 | 4 payments / 6 weeks | ~6% |
| ZIP | $35–$400 | 4 payments / 6 weeks | ~4–6% |
| Splitit | $500+ | Existing card split | Variable |
| WeGetFinancing | $500+ | Extended financing | Variable |
Consumer trust and provider recognition matter as much as fee structure. Shoppers often prefer their known BNPL provider, so limiting provider count to one or two carefully chosen options can improve performance.
What merchants actually gain by offering BNPL
The conversion data on BNPL is consistent across categories. Offering it at checkout increases conversion rates by 20–30% and average order value by 30–50%. Cart abandonment decreases by 20% overall, and up to 29% among shoppers ages 18–34 for higher-value orders.
The primary benefits for merchants:
- Higher conversion rates, particularly on orders in the $75–$500 range where installment framing meaningfully changes purchase psychology
- Larger average order values as customers feel comfortable adding more to their cart when payments are split
- Reduced cart abandonment, especially among younger demographics and on higher-ticket items
- Access to a broader customer base, including shoppers who prefer not to use credit cards or who want to manage cash flow
- Repeat purchase behavior driven by positive BNPL experiences
Statistic callout: 43% of consumers abandon a purchase when BNPL is unavailable, according to PYMNTS Intelligence research with PayPal. Payment flexibility has moved from a checkout feature to a merchandising decision.
Merchants also report that BNPL customers, particularly in home goods and fitness categories, tend to become strong repeat buyers. The installment structure removes the upfront price barrier for customers who were previously excluded by cost, and those customers often return.
Risks and considerations you need to manage
BNPL fees are higher than standard card processing rates and can meaningfully reduce margins on transactions depending on order size and fee percentage. The math only works if BNPL genuinely lifts conversion or order value for that product category.
Key risks to plan for:
- Margin erosion on low-AOV orders. Offering BNPL on a $30 item creates a $7.50 installment that feels trivial to the customer and costs you a disproportionate fee. Set a minimum cart value to prevent this.
- Higher return rates. BNPL can increase returns, particularly in apparel, because the lower upfront commitment reduces purchase hesitation in ways that don’t always survive the buyer’s remorse window. Monitor return rates by payment method from day one.
- Mobile redirect failures. BNPL redirect flows behave differently on iOS Safari than in a desktop browser emulator. A broken redirect on an iPhone loses the sale entirely.
- Decision paralysis from too many providers. Stacking four BNPL widgets at checkout confuses shoppers and splits your performance data so thin that neither provider can be optimized.
- Compliance and regulatory exposure. US regulators, including the Consumer Financial Protection Bureau, have increased scrutiny of BNPL products. Merchants must ensure their checkout disclosures accurately represent payment terms, and they should monitor provider compliance updates as the regulatory environment continues to evolve.
- Return fee clauses. Some providers do not refund their merchant fee on returned orders. At high return rates, this compounds margin pressure quickly.
How to choose the right BNPL provider for your store
Start with your average order value and your customer demographics. Those two variables determine which provider’s approval rates and fee structures actually work in your favor.
Decision framework:
- AOV under $150: Afterpay and Klarna are the natural fit. Both have strong consumer recognition in this range and low-friction onboarding for shoppers.
- AOV $150–$500: Klarna’s Pay in 4 still converts well here. Consider piloting Affirm’s monthly installment option alongside it for customers who want longer terms.
- AOV above $500: Affirm and Splitit dominate. Splitit’s model converts well with older, higher-income customers who distrust new credit applications.
Beyond AOV, evaluate each provider’s integration quality for your platform. A provider with a native Shopify checkout extension will deliver a cleaner mobile experience than one requiring a third-party wrapper. Check whether the provider offers on-site messaging widgets for product pages, what their merchant dashboard looks like for performance tracking, and whether they have co-marketing assets you can use in paid social.
Limit your active providers to two at most. One short-term option (four payments over six weeks) for orders in the $80–$400 range, and one longer-term financing option for orders above $400, covers the vast majority of use cases without creating checkout confusion.
Pro Tip: Request a merchant rate review every 12 months. Volume thresholds that unlock lower rates are rarely communicated proactively by providers. If you’re processing more than $500,000 annually through a single BNPL provider, you have real negotiating leverage.
Best practices and advanced strategies for BNPL checkout performance
The merchants seeing the largest lifts in 2026 are not just activating BNPL and waiting. They treat it as a managed financial product with deliberate placement, margin-aware configuration, and regular performance review.
Use native platform integrations
Native platform plugins avoid mobile redirect conflicts that third-party wrappers frequently cause. On Shopify, Klarna, Afterpay, and Affirm all offer native checkout extensions through Shopify’s Checkout Extensibility framework. On WooCommerce, use the official gateway plugin from each provider. Test on real iOS and Android devices before going live, not just desktop browser emulators.
Apply dynamic payment sequencing
Dynamic payment sequencing surfaces BNPL based on cart value thresholds and shopper cohort signals rather than displaying every payment method to every visitor. Brands deploying this approach report average order value lifts of 22% and checkout conversion improvements of 18–31% compared to static payment display logic.
Surface BNPL messaging upstream
Displaying installment messaging early on product detail pages and cart pages shapes purchase intent before the customer has mentally committed to a price. “Or 4 payments of $24.75” placed directly below the product price converts BNPL at a meaningfully higher rate than stores that surface it only at checkout. Merchants using upstream messaging and Pay Later button placement recorded a 4.4% increase in overall sales in PayPal’s research. Use specific dollar amounts, not generic “Pay in 4” copy. Dynamic widgets that update when a customer changes product variants or cart contents outperform static messaging.
For product pages specifically, optimizing the full product page experience alongside BNPL widget placement compounds the conversion benefit. Price framing and BNPL messaging work together.
Set minimum order thresholds
Set a minimum cart value of $75–$100 for BNPL eligibility. Below that threshold, the installment amounts feel trivial to the customer and the merchant fee is disproportionately high relative to margin. Also disable BNPL on heavily discounted SKUs during promotional periods. If you’re running a 20% sitewide sale and paying a 5–6% BNPL fee on top, the margin math collapses.
Limit visible payment options
Limiting visible BNPL options at checkout reduces choice paralysis and improves data clarity for optimization. A checkout page with four BNPL widgets stacked vertically, each with its own branding and call to action, causes shoppers to freeze. The practical rule: digital wallets, card, and one BNPL provider as primary options. Use progressive disclosure for secondary methods.
Measure incrementality, not just adoption
Segment BNPL transactions in GA4 by payment method and track conversion rate, average order value, return rate, and net revenue per order. Adoption rate alone is a vanity metric. Run geo-holdout tests when volume allows: disable BNPL messaging in two matched markets for 30 days while keeping it active elsewhere. The conversion delta between markets gives you the cleanest signal of true incremental revenue.
| Metric | What it tells you |
|---|---|
| BNPL vs. non-BNPL AOV | Whether installment framing is unlocking larger baskets |
| BNPL conversion rate | Whether placement and messaging are working |
| Return rate by payment method | Whether BNPL is enabling aspirational purchases that don’t stick |
| Net revenue per BNPL order | Whether the channel is profitable after fees and returns |
| Geo-holdout conversion delta | True incremental lift, not payment method shift |
Pro Tip: Embed BNPL installment messaging in your cart abandonment emails and SMS flows. A “your $220 order breaks down to 4 payments of $55” reminder addresses affordability hesitation directly. Merchants using this tactic in abandonment recovery flows report meaningful improvement in recovery rates compared to price-only messaging.
How Sensepass fits into your broader payment strategy
BNPL performs best when it’s one part of a well-structured, multi-method payment environment. Offering installments alongside digital wallets, card payments, and alternative payment methods gives every customer a path to purchase that fits their preference.
Sensepass is built for exactly this. As a processor-agnostic payment orchestration layer, Sensepass integrates with 50+ card processors and connects merchants to a broad range of payment methods across online and in-store channels. You can enable BNPL for your retail store alongside the full Sensepass payment suite without rebuilding your checkout from scratch.
Sensepass supports the following payment methods natively:
- BNPL: Klarna, Sezzle, ZIP, Splitit, Afterpay
- Financing: WeGetFinancing, Affirm
- Digital wallets: PayPal, Venmo, WeChat, Apple Pay, Google Pay, Alipay, Amazon Pay
- Crypto: BitPay, Coinbase
- Pay by bank: Trustly, LinkMoney
Sensepass integrates with major platforms including NetSuite, SuiteCommerce, Oracle Xstore, Aptos, Shopify POS, BigCommerce, Storis, NCR, and Dynamics365. Whether you’re running a single-location retail store or a multi-channel operation across POS, self-checkout, and ecommerce, the same payment infrastructure covers all of it.
The processor-agnostic model matters because it means you’re not locked into a single card processor’s rates or BNPL partner agreements. You choose the processors and providers that work for your margin structure, and Sensepass routes transactions accordingly. For merchants managing omnichannel payment flows across both physical and digital channels, that flexibility is the difference between a payment stack that serves your business and one that constrains it.
BNPL optimization doesn’t happen in isolation. The merchants winning with it in 2026 are the ones who’ve built a checkout environment where every payment method, from Apple Pay to Affirm to Splitit, is presented clearly, works reliably on mobile, and is tracked at the transaction level. That’s the standard Sensepass is built to support.

Key Takeaways
Optimizing BNPL at checkout requires deliberate placement, margin-aware configuration, and consistent measurement to drive real conversion lifts rather than just payment method shifts.
| Point | Details |
|---|---|
| Place BNPL at equal visual weight | BNPL hidden in accordion menus loses conversions; surface it alongside cards and digital wallets. |
| Set a $75–$100 minimum order threshold | Protects margins from disproportionate BNPL fees on low-value orders. |
| Surface installment messaging upstream | Product and cart page placement drives a 4.4% overall sales lift versus checkout-only display. |
| Limit providers to one or two | More than two BNPL options at checkout causes decision paralysis and splits performance data. |
| Measure net revenue, not adoption rate | Track conversion rate, AOV, return rate, and net margin per BNPL order in GA4 by payment method. |
Recommended
- How to Enable BNPL Payments for Your Retail Store – Omnichannel payments at the Point Of Sale | Sensepass
- BNPL Payment Setup Process for Retailers: 2026 Guide – Omnichannel payments at the Point Of Sale | Sensepass
- How to Offer Buy Now Pay Later: 2026 Retail Guide – Omnichannel payments at the Point Of Sale | Sensepass
- Streamline checkout for retail success in 2026 – Omnichannel payments at the Point Of Sale | Sensepass

 New York Office
260 Madison Ave Suite 8018 New York NY 10016

