
Payment Flexibility Strategies 2026: A Retailer’s Guide
July 8, 2026
TL;DR:
- Payment flexibility involves selecting and orchestrating multiple payment methods to match customer preferences, improving approval rates. Retailers must focus on full orchestration, token portability, and segment-specific routing to maximize transaction success and conversion. Accepting cash remains essential, and smart method deployment based on AOV enhances overall payment strategy effectiveness.
Payment flexibility strategy is defined as the deliberate selection and orchestration of multiple payment methods to match customer preferences, order profiles, and channel requirements. 70% of consumers choose retailers based on available payment options, making this one of the highest-leverage decisions you can make in 2026. The retailers who win are not simply adding more payment buttons at checkout. They are building adaptive payment plans that route transactions intelligently, manage tokens efficiently, and cover every rail their customers actually use.
What payment flexibility strategies 2026 retailers need to know
Payment flexibility, in industry terms, is often called payment method diversification combined with payment orchestration. Both concepts work together. Diversification covers which methods you accept. Orchestration covers how transactions flow through those methods to maximize approvals and minimize friction.
The gap between retailers who treat payment as a utility and those who treat it as a conversion tool is growing fast. A retailer accepting only cards and one digital wallet is leaving money on the table every day. The payment methods future 2026 belongs to businesses that think in rails, not just processors.
Which payment methods should retailers offer in 2026?
The right payment mix covers primary rails first, then secondary rails based on your customer segments and average order values (AOV). Primary rails are credit cards, debit cards, and major digital wallets. These account for the majority of transactions and carry the highest baseline trust.
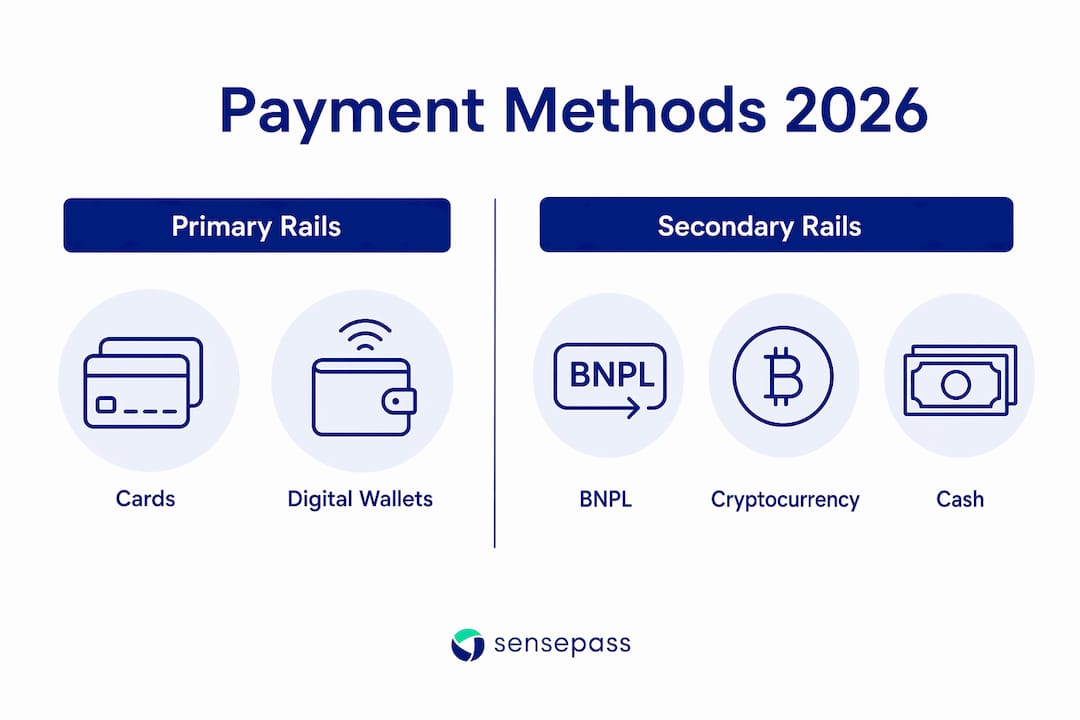
Secondary rails add conversion at the margins. Buy Now Pay Later (BNPL) options like Klarna, Sezzle, ZIP, Splitit, and Afterpay perform best on higher AOV purchases where customers want to spread cost. Pay by Bank options like Trustly and LinkMoney reduce processing fees and appeal to customers who prefer direct account transfers. Crypto payments through BitPay and Coinbase serve a smaller but loyal segment. Digital wallets including PayPal, Venmo, Apple Pay, Google Pay, Alipay, Amazon Pay, and WeChat cover the broadest range of mobile-first shoppers.
Cash remains a baseline expectation in physical retail. 4 out of 5 consumers used cash in the last 30 days, and 90% plan to continue doing so. Cash still represents about 1 in 7 payments, which means removing it from your in-store checkout is a real exclusion decision, not a minor operational choice.
The core retail payment methods to evaluate for your 2026 mix include:
- Credit and debit cards: The dominant rail for most retail segments
- Digital wallets: Apple Pay, Google Pay, PayPal, Venmo, Alipay, Amazon Pay, WeChat
- BNPL: Klarna, Afterpay, Sezzle, ZIP, Splitit for higher AOV categories
- Financing: WeGetFinancing and Affirm for large-ticket purchases
- Pay by Bank: Trustly and LinkMoney for fee-sensitive or high-volume transactions
- Crypto: BitPay and Coinbase for tech-forward customer segments
- Cash: Non-negotiable for omnichannel inclusivity in physical stores
Pro Tip: Prioritize trust and widespread acceptance before adding niche methods. Consumers only scale adoption of new payment methods after core security and fraud protection requirements are met. Launch your primary rails first, then layer in secondary options once your fraud controls are solid.
How does payment orchestration improve approval rates?
Payment orchestration is the technology layer that sits above your processors and routes each transaction to the best available path in real time. It is not simply having multiple processors. It is having automated logic that decides which processor, which network, and which token to use for each transaction based on current conditions.
Full orchestration capability produces approval rates above 97% and transaction completion gains above 2%. Partial orchestration, where you add a second processor but lack automated routing logic, yields far smaller improvements. The five capabilities that define a complete orchestration stack are:
- Automated routing: Rules-based and machine-learning-driven logic that selects the optimal processor path per transaction
- Frequent routing updates: Real-time adaptation to issuer and network changes, not monthly manual revisions
- Failover logic: Automatic retry through an alternate processor when the primary path declines or fails
- Token control: Ownership and portability of payment credentials across processors without re-tokenizing customers
- Easy rail addition: The ability to add a new payment method or processor without a multi-month engineering project
Token control deserves special attention. Token ownership directly determines how fast you can onboard new providers or switch processors. Without portable tokens, each provider change triggers a re-enrollment process that can take months and introduces customer friction. With token portability, you switch or add providers in days.
Pro Tip: Avoid partial orchestration deployments. Adding a second processor without automated routing logic increases operational complexity without delivering the approval rate gains that justify the investment. Commit to the full stack or stay with a single well-configured processor until you can.
What infrastructure do you need to implement payment flexibility?
The technology foundation for flexible payment options in 2026 requires three things: a modular payment system, a processor-agnostic platform, and strong data security controls. Monolithic payment setups where your processor, gateway, and fraud tool are bundled by one vendor create lock-in that limits your ability to add methods or switch providers.
Sensepass is built as a processor-agnostic orchestration layer that integrates with 50+ card processors, giving retailers the freedom to choose and switch processors without rebuilding their payment stack. It connects to major platforms including NetSuite, SuiteCommerce, Oracle Xstore, Aptos, Shopify POS, BigCommerce, Storis, NCR, and Dynamics365. That breadth of platform support means your payment layer works across in-store POS, self-checkout, eCommerce, call center, and subscription channels from a single integration.
| Infrastructure requirement | Why it matters |
|---|---|
| Processor-agnostic platform | Prevents vendor lock-in and enables best-rate routing |
| Modular payment method support | Lets you add BNPL, wallets, or crypto without rebuilding |
| Token portability | Reduces provider switching time from months to days |
| Real-time fraud and compliance controls | Protects customer trust before you scale new methods |
| Multi-platform POS integration | Covers in-store, online, and self-checkout from one system |
Data security and compliance are not optional prerequisites. Fraud protection and PCI DSS compliance must be in place before you expand to secondary rails. Customers who experience fraud on a new payment method do not return, and the reputational cost outweighs any conversion gain from adding that method prematurely.
How to build your 2026 payment flexibility strategy step by step
A structured approach prevents the most common failure mode: adding payment methods reactively without a clear rationale. Follow these steps to build a payment strategy that improves both approval rates and conversion.
-
Audit your current payment stack. Document every processor, gateway, and payment method you currently accept. Identify your approval rate by method and channel. Note which methods generate the most declines or abandoned carts.
-
Analyze your customer segments. Segment by AOV, product category, and channel. Segmented payment methods based on AOV and product category outperform one-size-fits-all stacks. A $30 grocery purchase and a $600 furniture order need different payment options.
-
Select your payment method mix. Map methods to segments. BNPL fits high-AOV categories. Pay by Bank fits repeat, high-volume buyers. Crypto fits specific tech-forward demographics. Cards and wallets cover everyone else.
-
Deploy orchestration before adding rails. Set up automated routing, failover, and token control first. Adding new payment methods without orchestration in place creates routing chaos and inconsistent approval rates.
-
Test and measure KPIs. Track approval rate by method, cart abandonment rate at checkout, and conversion lift by segment. Run A/B tests on checkout layouts when introducing new methods.
Key metrics to monitor on an ongoing basis:
- Approval rate per payment method and processor
- Checkout abandonment rate by device and channel
- BNPL utilization rate by product category and AOV band
- Token re-enrollment rate when switching processors
- Fraud rate per new payment method in the first 90 days
Pro Tip: Build payment rules by AOV band from day one. For example, surface BNPL options only on orders above a defined threshold, and offer Pay by Bank as a default for B2B or subscription customers. Matching payment options to segments reduces default decline risk and improves the customer experience without adding complexity at checkout.
How to avoid common pitfalls in payment flexibility
The most expensive mistake in payment flexibility is assuming one payment stack works for every customer, channel, and product. It does not. A single configuration optimized for your average transaction will underperform on outliers at both ends of the AOV range.
Common pitfalls to avoid:
- Adding methods without trust infrastructure: New rails fail when fraud controls are not in place. Security must precede expansion.
- Ignoring token ownership: Retailers who do not control their tokens face multi-month re-onboarding projects every time they switch or add a processor.
- Deploying BNPL indiscriminately: BNPL growth is slowing to single digits by 2029. Use it where AOV and customer profile justify it, not as a default add-on across every category.
- Removing cash from in-store checkout: Cash represents about 1 in 7 payments. Eliminating it excludes a measurable share of your in-store customers.
- Skipping regulatory review: Payment regulations vary by method and market. Pay by Bank, crypto, and BNPL each carry distinct compliance requirements that must be reviewed before launch.
“True payment flexibility success depends more on continuous operational payment routing and token portability than simply aggregating multiple providers. Retailers who focus only on adding payment logos at checkout without fixing the routing layer underneath will see minimal gains in approval rates or conversion.”
Key Takeaways
Payment flexibility in 2026 requires a combination of broad payment method coverage, full orchestration capability, and segment-specific routing rules to drive meaningful gains in approval rates and conversion.
| Point | Details |
|---|---|
| Cover primary rails first | Cards and major digital wallets must be solid before adding BNPL or crypto. |
| Deploy full orchestration | Automated routing, failover, and token control together produce approval rates above 97%. |
| Segment your payment mix | Match methods to AOV and product category rather than applying one stack to all transactions. |
| Control your tokens | Token portability cuts provider switching time from months to days and reduces integration costs. |
| Keep cash in-store | Cash still accounts for 1 in 7 payments; removing it excludes a real share of your customers. |
What I’ve learned about payment flexibility after watching retailers get it wrong
The retailers I see struggle most with payment flexibility share one trait: they treat it as a checkout feature rather than an operational system. They add Klarna or Apple Pay, call it done, and wonder why approval rates barely move. The problem is almost never the payment method itself. The problem is the routing layer underneath.
I’ve watched businesses spend months integrating a new processor only to find their token credentials are locked with the old one. That single oversight turns a two-week project into a six-month engineering effort. Token portability is not a technical detail. It is a business continuity issue.
The other pattern I see is BNPL deployed everywhere without a clear AOV rationale. BNPL works well on a $400 electronics purchase. It adds friction and confusion on a $25 transaction. The flexible payment options that actually lift conversion are the ones matched deliberately to the purchase context, not the ones added because a competitor offers them.
My honest advice: audit your routing logic before you audit your payment method list. Fix the infrastructure, then expand the menu. Retailers who do it in that order see real gains. Those who do it in reverse spend money and see noise.
— Vlad
How Sensepass powers omnichannel payment flexibility for retailers
Sensepass is built specifically for retailers who need to accept a broad range of payment methods across every channel without rebuilding their stack for each one.

Sensepass supports digital wallets including PayPal, Venmo, Apple Pay, Google Pay, Alipay, Amazon Pay, and WeChat. It covers BNPL through Klarna, Sezzle, ZIP, Splitit, and Afterpay, financing through WeGetFinancing and Affirm, crypto through BitPay and Coinbase, and Pay by Bank through Trustly and LinkMoney. The platform integrates with NetSuite, SuiteCommerce, Oracle Xstore, Aptos, Shopify POS, BigCommerce, Storis, NCR, Dynamics365, and more. As a processor-agnostic platform, Sensepass connects to 50+ card processors, giving you full routing flexibility without lock-in. Explore the full omnichannel payment solutions Sensepass offers to see how it fits your retail setup.
FAQ
What is a payment flexibility strategy?
A payment flexibility strategy is the planned selection and orchestration of multiple payment methods to match customer preferences, order values, and sales channels. The goal is to maximize approval rates and reduce checkout abandonment.
Why do 70% of consumers choose retailers by payment options?
Consumers select retailers based on whether their preferred payment method is available at checkout. Retailers without broad payment coverage lose customers before the transaction even begins.
What is payment orchestration and why does it matter?
Payment orchestration is the automated routing of transactions across multiple processors and payment methods to maximize approval rates. Full orchestration capability produces approval rates above 97%, compared to far lower rates from single-processor setups.
Should retailers still accept cash in 2026?
Yes. Cash represents about 1 in 7 payments, and 90% of cash users plan to continue using it. Removing cash from in-store checkout excludes a measurable share of customers.
How does BNPL fit into a 2026 payment strategy?
BNPL works best on higher AOV purchases where customers benefit from spreading cost. BNPL growth is slowing to single digits by 2029, so deploy it where your order profile and customer segment justify it rather than as a default option across all categories.
Recommended
- 2026 Trends in Payment Flexibility for Retail Leaders – Omnichannel payments at the Point Of Sale | Sensepass
- Your Guide to Flexible Payment Options in Retail – Omnichannel payments at the Point Of Sale | Sensepass
- Stepwise Flexible Checkout Process: 2026 Retail Guide – Omnichannel payments at the Point Of Sale | Sensepass
- Mobile Payment Trends 2026: What Retailers Must Know – Omnichannel payments at the Point Of Sale | Sensepass

 New York Office
260 Madison Ave Suite 8018 New York NY 10016

