
POS Payment Workflow Modernization for Retailers
May 20, 2026
TL;DR:
- Slow checkout speeds and limited payment options reduce revenue and undermine customer loyalty. Modern POS payment workflow upgrades, executed in phases with comprehensive auditing and staff training, improve transaction speed, acceptance, and omnichannel synchronization. Ongoing measurement of success and flexibility in processor choices ensure long-term retail performance and competitiveness.
Slow checkouts cost retailers more than time. Every friction point at the register chips away at customer loyalty, conversion rates, and revenue. POS payment workflow modernization has moved from a technical project to a business priority for any retailer competing on experience. Customers expect to pay with their preferred method instantly, whether that’s a digital wallet, a buy now pay later option, or a traditional card. This guide walks you through assessing your current setup, executing a phased upgrade, avoiding the most common mistakes, and measuring real results.
Table of Contents
- Key takeaways
- Understanding current POS payment workflow limitations
- Step-by-step guide to POS payment workflow modernization
- Common mistakes to avoid during modernization
- Verifying and measuring success after modernization
- My take on what most retailers get wrong
- How Sensepass powers your payment workflow upgrade
- FAQ
Key takeaways
| Point | Details |
|---|---|
| Audit before you upgrade | Map your current POS hardware, software, and integrations before making any changes to avoid costly surprises. |
| Phased rollouts prevent disruption | Running a modern payment layer alongside legacy systems protects data integrity and minimizes downtime during migration. |
| Checkout speed directly affects revenue | A 1-second delay in page load causes a 7% conversion drop, making speed a critical success metric. |
| Processor agnosticism gives you leverage | Choosing a platform that connects to 50+ card processors lets you optimize for cost, region, and approval rates. |
| Measurement drives ongoing improvement | Track payment success rates, checkout times, and fraud metrics after launch to keep refining your workflow. |
Understanding current POS payment workflow limitations
Before you can modernize, you need an honest picture of where your current system falls short. Most legacy POS payment workflows share the same set of problems, and they get more expensive to ignore every year.
Common limitations retailers encounter include:
- Limited payment method support. Older systems handle cards but struggle with digital wallets, BNPL options, or bank transfers. Customers who can’t pay their preferred way often leave.
- Poor omnichannel synchronization. A customer who starts a purchase online and finishes in store should have a consistent experience. Legacy POS systems routinely fail at real-time inventory and omnichannel alignment.
- Slow transaction processing. Older systems process transactions through single-path routing with no fallback logic, leading to unnecessary declines and longer wait times.
- Weak security architecture. Compliance gaps around PCI-DSS, outdated tokenization methods, and inadequate fraud detection expose you to both financial and reputational risk.
- Integration friction. Legacy platforms rarely connect cleanly with modern eCommerce systems, ERPs, or loyalty programs, creating data silos and manual reconciliation work.
Before you touch a single piece of hardware, audit your existing infrastructure. Document your current POS hardware models, software versions, network setup, and all third-party integrations. This baseline tells you what can be upgraded in place and what needs replacing.
Pro Tip: Run a payment decline analysis on your last 90 days of transactions. The decline reasons will reveal specific bottlenecks, such as processor timeouts or unsupported card types, that should directly inform your modernization priorities.
Modern payment method diversity now includes digital wallets like Apple Pay and Google Pay, BNPL products like Klarna and Afterpay, crypto payments, and pay-by-bank options. If your current POS can’t accept these, you’re not just behind. You’re turning away customers.
Step-by-step guide to POS payment workflow modernization
Executing POS payment workflow modernization effectively requires a structured process. Jumping straight to new hardware without a clear plan is one of the most expensive mistakes retailers make. Here is a proven sequence to follow.
-
Map your current architecture and define goals. Document every touchpoint in the payment journey: customer-facing terminals, back-end processors, fraud tools, and reporting systems. Set specific targets, such as reducing checkout time under 30 seconds or increasing payment method acceptance by 40%.
-
Choose a platform-agnostic payment orchestration layer. A processor-agnostic middleware lets you connect multiple processors and route transactions intelligently across them. This gives you flexibility on cost and redundancy that a single-processor setup never can.
-
Select a platform that supports diverse payment methods. Your upgraded system needs to handle the full range of modern payment types. This means digital wallets, BNPL at the point of sale, financing options, crypto, and bank transfers. Limiting payment methods at this stage defeats the purpose of the upgrade.
-
Move to a cloud-native or hybrid POS architecture. Cloud-native POS platforms provide modular, scalable components for payments, inventory, orders, and loyalty. They also offer offline resilience, meaning a lost internet connection doesn’t freeze your checkout.
-
Run parallel systems during migration. Parallel running a modern payment layer alongside your legacy system ensures data integrity and gives your team time to validate the new workflow before going live fully.
-
Configure intelligent retry and routing logic. When a transaction declines, the system should automatically retry through an alternate processor path rather than surfacing a failure to the customer. This alone can recover a significant percentage of lost sales.
-
Optimize checkout speed aggressively. Target sub-3-second load times at every checkout stage. 40% of customers abandon checkout processes that take longer than 3 seconds to load. Speed is not a luxury in modern retail. It’s a retention tool.
-
Integrate with your existing platforms. Your payment layer should connect cleanly to your existing retail stack without requiring full system replacement.
Pro Tip: During parallel running, set a two-week validation window where both systems process the same transaction types. Compare approval rates, processing times, and error logs side by side before completing the cutover.
The table below shows how modern orchestration-based architecture compares to a traditional single-processor POS setup:
| Feature | Legacy single-processor POS | Modern orchestrated POS |
|---|---|---|
| Payment method support | Cards only | Cards, wallets, BNPL, crypto, bank pay |
| Retry logic | None or manual | Automated multi-path routing |
| Processor flexibility | One processor | 50+ processors |
| Offline resilience | Limited | Cloud-native fallback mode |
| Omnichannel sync | Siloed | Real-time across all channels |
| Compliance management | Manual updates | Automated PCI-DSS tooling |
Common mistakes to avoid during modernization
Even well-resourced teams stumble during point of sale modernization. Knowing where the pitfalls are helps you route around them before they cost you money or customers.
The most damaging mistakes fall into predictable patterns:
- Full rip-and-replace without phased testing. Switching every terminal simultaneously amplifies any configuration error across your entire store network. A phased approach lets you catch problems at limited scale before they spread.
- Ignoring checkout performance during integration. It’s easy to focus entirely on feature additions and overlook how each new integration adds latency. Every added payment plugin should be load-tested before it goes live.
- Inconsistent omnichannel experience. Customers notice when the payment options available online don’t match what’s offered in store. A unified omnichannel approach requires payment method parity across all channels.
- Misconfigured retry logic. Retrying failed transactions through the same path repeatedly leads to involuntary churn and higher fees. Retry logic must route through alternate processor paths, not repeat the same failed route.
- Skipping staff training. New payment workflows mean new error scenarios. Staff who don’t understand how the system handles a declined BNPL transaction or a failed wallet authorization will create friction at exactly the wrong moment.
- Underestimating hardware compatibility. Not all payment terminals support the full range of contactless and digital wallet protocols. Verify hardware compatibility before finalizing your payment method list.
The most avoidable modernization failures aren’t technical. They’re organizational. Retailers who treat POS upgrades as IT projects rather than cross-functional business changes consistently underperform during rollout.
Compliance deserves its own mention. PCI-DSS requirements don’t pause during a migration. If your phased rollout involves both old and new systems processing live transactions simultaneously, you need to confirm that both environments maintain compliance throughout the transition period.
Verifying and measuring success after modernization
Launching a modernized POS payment workflow is the beginning of the work, not the end. The retailers who get the most from their upgrades are the ones who measure systematically and refine continuously.
The right metrics tell you whether your changes are actually working. Here’s how pre- and post-modernization performance typically compares across the key indicators:
| Metric | Pre-modernization | Post-modernization target |
|---|---|---|
| Average checkout time | 45 to 90 seconds | Under 30 seconds |
| Payment success rate | 85 to 90% | 95%+ |
| Cart abandonment rate | High (30%+) | Reduced by 20 to 30% |
| Payment method coverage | 1 to 3 methods | 8 to 15+ methods |
| Fraud detection response time | Hours or manual | Real-time automated |
| Omnichannel sync accuracy | Inconsistent | Real-time, unified |
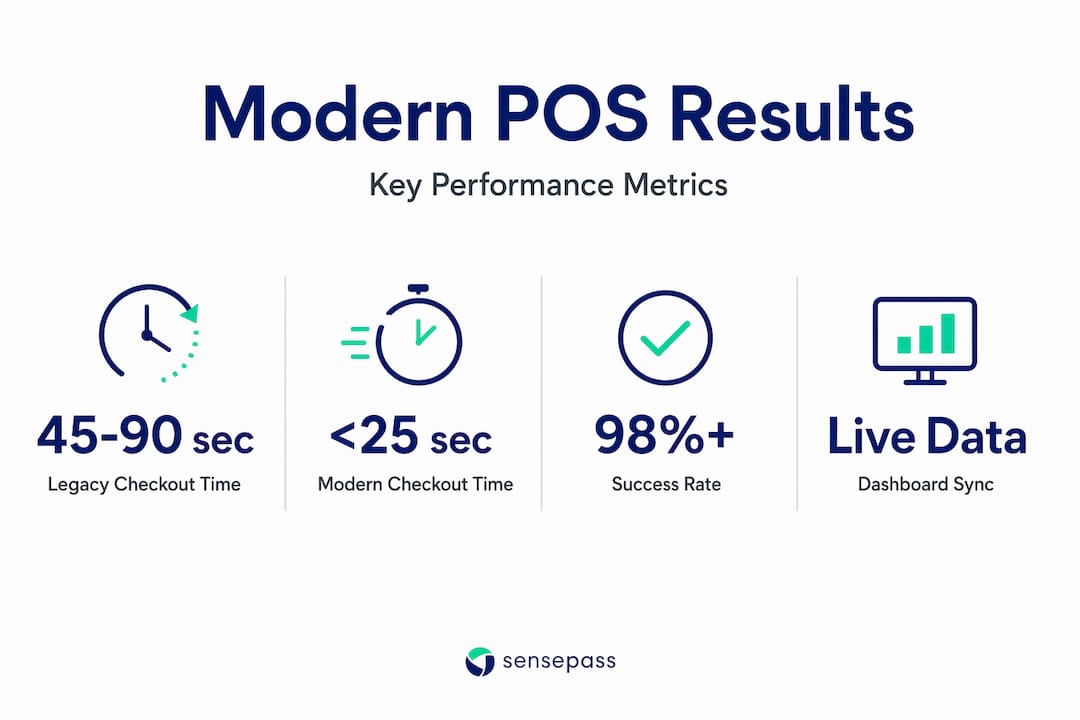
A modern POS acting as a central hub gives you real-time dashboards with live inventory syncing and sales insights. Use these dashboards to track your key performance indicators weekly, especially in the first 90 days after launch.
Payment success rates and fraud metrics should be reviewed together. An increase in approvals is positive, but not if it comes alongside a rise in fraudulent transactions. Modern payment orchestration layers include real-time fraud prevention as a built-in function, not an afterthought.
Customer behavior data is equally valuable. Watch which new payment methods see the fastest adoption and which go unused. If BNPL adoption is low, the issue might be presentation at checkout, not lack of customer interest. If crypto transactions are spiking, you may want to add a second crypto processor for redundancy.
Revisit your payment routing configurations every quarter. Processor performance changes over time. Approval rates, fees, and latency shift based on transaction volume, card types, and regional factors. The ability to optimize routing across processors is one of the clearest financial advantages of modern payment orchestration.
My take on what most retailers get wrong
I’ve watched retailers invest real money in POS upgrades and still leave disappointed. The technology works. The disappointment comes from a narrower problem: they modernize the hardware but not the mindset.
Most teams still treat their POS as a checkout tool. A place where the transaction closes. That framing is limiting. Your POS is the operational backbone of your retail business. It connects inventory, staff, customer data, and revenue in real time. When you modernize it correctly, you’re not just speeding up payments. You’re building a live intelligence layer for your entire operation.
In my experience, the retailers who see the sharpest improvements treat modernization as a phased, data-driven process from day one. They don’t rush the migration. They run parallel systems, review their decline logs obsessively, and test every payment method before it goes live. They also train their staff properly, which is the step most teams underestimate.
The other pattern I’ve noticed is how important processor agnosticism becomes over time. The retailer who locked into a single processor two years ago is now paying above-market fees with limited room to negotiate. The retailer who built on a flexible orchestration layer can switch or add processors in days, not months. That flexibility compounds in value every quarter.
If you’re evaluating payment partners for your next upgrade, the ability to select payment gateways across regions and transaction types isn’t a nice-to-have. It’s the feature that protects your margins long-term.
— Vlad
How Sensepass powers your payment workflow upgrade
When you’re ready to move beyond the planning stage, Sensepass provides the orchestration layer that makes POS payment workflow modernization practical at scale.

Sensepass integrates with major retail and POS platforms including NetSuite, SuiteCommerce, Oracle Xstore, Aptos, Shopify POS, BigCommerce, Storis, NCR, Dynamics365, and more. You don’t need to rebuild your existing stack. Sensepass connects to it. On the payment method side, Sensepass supports digital wallets (PayPal, Venmo, WeChat, Apple Pay, Google Pay, Alipay, Amazon Pay), BNPL options (Klarna, Sezzle, ZIP, Splitit, Afterpay), financing through WeGetFinancing and Affirm, crypto payments via BitPay and Coinbase, and pay-by-bank through Trustly and LinkMoney. Sensepass is also fully processor-agnostic, giving you access to 50+ card processors so you can optimize for approval rates, fees, and geography.
For retailers serious about omnichannel payment strategy, Sensepass is built to support the full scope of how modern customers pay. Explore how Sensepass helps you improve retail checkout performance across every channel.
FAQ
What is POS payment workflow modernization?
POS payment workflow modernization is the process of upgrading your point of sale infrastructure to accept diverse payment methods, reduce checkout friction, and connect payment data across all retail channels. It typically involves replacing or layering over legacy systems with cloud-native or orchestration-based platforms.
How long does a POS payment modernization project take?
A phased modernization project typically runs 3 to 6 months from initial audit to full deployment, depending on store count and system complexity. Parallel running periods of 2 to 4 weeks per phase are standard practice to validate performance before full cutover.
What payment methods should a modernized POS support?
A fully modernized POS should support credit and debit cards, digital wallets like Apple Pay and Google Pay, BNPL options like Klarna and Afterpay, pay-by-bank, financing options, and crypto payments. Modern retailers upgrading POS are adding these methods to meet contemporary customer expectations.
What is intelligent retry logic in payment processing?
Intelligent retry logic automatically routes a declined transaction through an alternate processor path rather than surfacing the failure to the customer. Without it, repeated retries on the same path lead to involuntary churn and unnecessary processing fees.
How do you measure success after a POS payment upgrade?
Track payment success rates, average checkout time, cart abandonment rates, and fraud metrics in the first 90 days post-launch. A well-executed upgrade should push payment success rates above 95% and meaningfully reduce checkout times compared to your pre-modernization baseline.
Recommended
- Master Payment Processing Best Practices for Your Business – Omnichannel payments at the Point Of Sale | Sensepass
- Complete Guide to Retail Payment Workflow Process – Omnichannel payments at the Point Of Sale | Sensepass
- Seamless retail payment workflow: step-by-step guide – Omnichannel payments at the Point Of Sale | Sensepass
- Retail Payment Ecosystem Guide: Complete Overview – Omnichannel payments at the Point Of Sale | Sensepass

 New York Office
260 Madison Ave Suite 8018 New York NY 10016

