
Processor-Agnostic Payment Setup: A Retailer’s Guide
May 27, 2026
TL;DR:
- Implementing a processor-agnostic payment system allows retailers to route transactions through multiple providers, enhancing redundancy, cost savings, and payment method diversity. Proper preparation includes auditing existing systems, establishing merchant relationships, and planning for compliance, while phased rollout and monitoring ensure reliability. Using an orchestration layer simplifies integration and is often best purchased rather than built in-house for efficiency and ongoing maintenance.
If your store has ever gone offline because a single payment processor had an outage, you already understand the core problem this guide to processor-agnostic payment setup addresses. Retailers who rely on one processor hand that provider significant control over their revenue, their customer experience, and their operating costs. A processor-agnostic payment system changes that equation entirely. It lets you route transactions through multiple providers, add new payment methods without rebuilding your stack, and negotiate better rates because you have real alternatives. This guide walks you through exactly how to build that setup.
Table of Contents
- Key Takeaways
- Understanding processor-agnostic payment systems
- Preparation steps before you implement
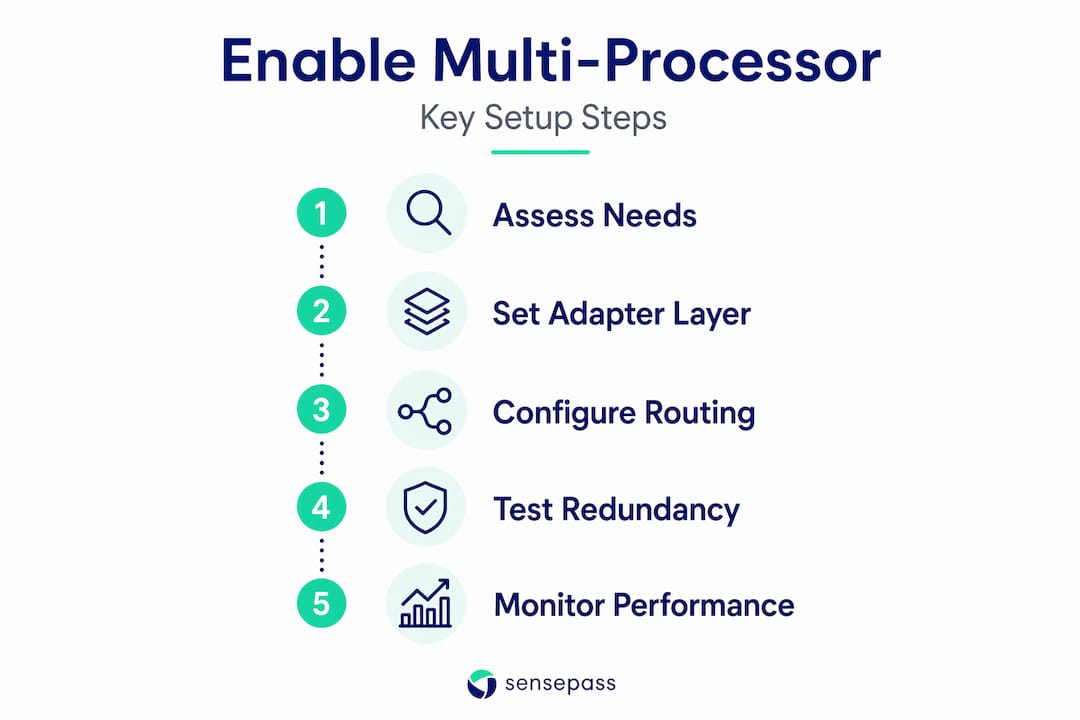
- Step-by-step process to enable multi-processor payments
- Common challenges and how to handle them
- Results you can expect after a successful setup
- My take on building processor-agnostic payments
- How Sensepass makes this setup practical for retailers
- FAQ
Key Takeaways
| Point | Details |
|---|---|
| Know your components | A processor-agnostic setup requires three layers: adapters, a routing engine, and a reconciliation spine working together. |
| Prepare before you build | Audit your current payment stack, establish PSP relationships, and confirm PCI DSS compliance before writing a single integration. |
| Phase your rollout | Start by sending 1% of traffic through the new routing layer before adding a second provider to validate stability. |
| Protect against failure | Circuit breakers should cut traffic to any provider exceeding a 50% failure rate to prevent cascading issues across your system. |
| Measure what matters | Track authorization rates, processing costs, and decline-code distributions per processor to continuously optimize your routing logic. |
Understanding processor-agnostic payment systems
The phrase “processor-agnostic” simply means your payment infrastructure does not have a permanent dependency on any single card processor or payment provider. Your system can route a transaction to Processor A today and Processor B tomorrow, based on cost, performance, or availability, without changing your checkout code.
To understand why this matters, you need to know how the three core layers differ from one another.
- Payment processor: The company that actually moves money between the cardholder’s bank and your merchant account. Examples include Stripe, Braintree, and Adyen.
- Payment gateway: The gateway vs processor difference sits at the front of the transaction. It encrypts card data, validates the request format, and sends the authorization to the processor.
- Orchestration layer: The intelligence sitting above both. It decides which gateway and processor to use for any given transaction, handles failover, and consolidates reporting.
A true processor-agnostic architecture adds one more concept: the adapter. Adapters abstract provider differences, converting each processor’s proprietary API responses into a normalized internal format. This means your routing logic never has to care whether it is talking to Stripe or a regional acquirer. It just reads standardized output.
The benefits stack up quickly once the architecture is in place. You get failover redundancy when one provider goes down. You get cost optimization through least-cost routing. You get the ability to add local payment methods for international markets without rewiring your checkout. And you reduce the negotiating leverage any single processor holds over your rates.
Pro Tip: When evaluating whether you need an orchestration layer, count how many payment methods your customers ask for that you currently cannot offer. That number is your business case.
Preparation steps before you implement
Good implementation starts long before any code is written. Skipping this phase is the most common reason processor-agnostic projects run over budget and timeline.
- Audit your current payment stack. Document every PSP, gateway, and payment method you currently support. Note their contract terms, termination clauses, and monthly volumes. This tells you what you are working with and what you cannot touch yet.
- Define your business objectives. Are you trying to reduce processing costs? Add BNPL options like Klarna or Afterpay? Expand internationally? Your objectives determine which processors to add first and how to configure routing priority.
- Establish merchant relationships with target PSPs. You cannot route to a processor you do not have a contract with. Open merchant accounts with your target providers early, because underwriting can take weeks.
- Assess your compliance posture. A multi-processor setup expands your PCI DSS scope if payment data touches your servers. Work with a QSA to confirm your tokenization and data-flow diagrams account for every new integration path.
- Evaluate build vs. buy. Building your own orchestration carries substantial ongoing maintenance. Unless payments are a core competitive advantage for your business, buying a proven orchestration platform almost always makes more economic sense when you factor in provider-specific quirks and evolving compliance mandates.
The table below summarizes the infrastructure you need before going live.
| Component | Purpose | Common Options |
|---|---|---|
| Adapter layer | Normalize PSP-specific API responses | Custom code or vendor SDK |
| Routing engine | Apply least-cost, failover, and cascading logic | Orchestration platform or in-house |
| Tokenization vault | Store card data off your servers | Third-party vault provider |
| Reconciliation engine | Aggregate settlements across PSPs | Orchestration layer or accounting tool |
| Monitoring stack | Track authorization rates per provider | Datadog, Grafana, or built-in dashboards |
Step-by-step process to enable multi-processor payments
This is the execution phase. Follow these steps in order to build a processor-agnostic payment flow that is reliable and maintainable.
-
Design your adapter interfaces. Each processor gets its own adapter class with a normalized “money-shaped” interface. Use integer minor units for all currency amounts to eliminate floating-point errors. Every adapter returns the same internal response object regardless of which processor handled the transaction.
-
Build your routing strategies. Define three routing modes: failover (try Processor A, then fall back to B), least-cost (select the processor with the lowest effective rate for this card type), and cascading retries (attempt a second processor only on a retryable decline). A retail payment routing guide can help you understand how routing logic maps to your POS environment specifically.
-
Implement circuit breakers. Your system needs automated protection against sending traffic to a failing provider. Circuit breakers cut off providers that exceed a 50% failure rate, allowing them to recover before receiving traffic again. Without this, a degraded processor will drag down your entire transaction success rate.
-
Map your decline-code taxonomy. Decline codes must be centralized into a universal taxonomy that distinguishes retryable declines (insufficient funds, timeout) from hard declines (stolen card, do not honor). Cascading retries should only fire on retryable codes. Retrying a hard decline wastes money and risks flagging the transaction as suspicious.
-
Add idempotency controls. Idempotency keys backed by Redis prevent duplicate charges when a retry or webhook fires multiple times. Set a reasonable TTL on your cache to avoid unbounded memory growth. Fail-open behavior keeps the system available even when the cache is temporarily unreachable.
-
Phase your rollout with traffic splitting. Start with 1% of traffic routed through the new orchestration layer before adding your second processor. Monitor authorization rates, error rates, and latency at each increment before increasing volume. This is the step most retailers rush, and it is the one that determines whether the project succeeds or requires a costly rollback.
Pro Tip: Run your new routing layer in shadow mode first. It processes real transactions but does not change the outcome. This lets you measure its decision-making against your existing setup without any customer impact.
The table below shows what key metrics to monitor at each rollout phase.
| Phase | Traffic Share | Key Metrics to Watch |
|---|---|---|
| Shadow mode | 0% live routing | Decision accuracy vs. baseline |
| Initial live | 1% | Authorization rate, error rate, latency |
| Validation | 10-25% | Cost per transaction, decline distribution |
| Scaled rollout | 50% | Reconciliation accuracy, provider uptime |
| Full production | 100% | All metrics, ongoing optimization |
Common challenges and how to handle them
Even a well-planned processor-agnostic setup will surface operational challenges. Knowing what to expect makes the difference between a quick fix and a revenue-affecting incident.
- Reconciliation gaps. Individual provider dashboards will never give you a complete picture across processors. A centralized reconciliation engine that aggregates webhook events and settlement files from every PSP, then flags mismatches, is the only way to prevent silent revenue leakage at scale.
- Inconsistent checkout experience. Each processor may handle 3DS challenges, redirects, or error messaging differently. Normalize these flows at the orchestration layer so customers see a consistent experience regardless of which provider processes their payment.
- Retry storms. Retry logic with exponential backoff and jitter prevents the “thundering herd” problem where all failed transactions retry simultaneously and overload a recovering processor.
- Compliance drift. Adding a new processor means updating your PCI scope, your data flow diagrams, and potentially your tokenization routing. Build a checklist that triggers every time you add a provider.
- Maintenance overhead. Provider APIs change, webhooks shift, and rate structures update. The ongoing maintenance burden of a custom-built orchestration layer often exceeds the initial build cost. Budget for it or use a managed platform.
A centralized orchestration layer should be your single source of truth for transaction status. Relying on individual provider dashboards in a multi-processor environment guarantees reconciliation errors over time.
The retail payment security fundamentals that apply to single-processor setups apply equally here, but they require more deliberate attention across each integration point.
Results you can expect after a successful setup
The return on a processor-agnostic setup is measurable across three dimensions: revenue, cost, and customer reach.
Processor-agnostic systems drive measurable increases in authorization rates through intelligent routing. When one processor’s authorization rate drops on international Visa cards, the routing engine shifts that traffic automatically. Merchants who implement cascading retry logic typically recover a meaningful percentage of transactions that would otherwise fail silently.
On the cost side, least-cost routing generates savings by selecting the processor with the most favorable interchange and fee structure for each card type. Over high transaction volumes, those fractions of a percent add up to real budget recovery. You can review specific tactics in this guide to reducing processing costs to frame your expectations before you start.
The customer-facing benefits are just as significant. Diverse payment method support across digital wallets, BNPL, crypto, and pay-by-bank options expands your effective market reach. A shopper who cannot pay with their preferred method simply does not complete the purchase.
Additional outcomes worth planning for:
- Reduced single points of failure with automatic provider failover
- Consolidated transaction data across all channels in one reporting view
- Faster market expansion because adding a regional PSP no longer requires a full integration project
- Better negotiating leverage with all processors when they know you can route around them
My take on building processor-agnostic payments
I’ve seen retailers approach this project from two very different directions. Some treat it as a pure engineering exercise: build adapters, write routing logic, ship it. Others treat it as a business transformation project and involve operations, finance, and compliance from day one. The second group consistently gets better results.
What I’ve learned from watching both approaches is that the technical parts of this setup are actually the most predictable. Adapter patterns are well-documented. Circuit breakers work as designed. The harder problems are organizational. Who owns the routing configuration? Who reviews authorization rates by processor each week? What is the process when a new processor’s API changes and breaks your adapter?
My honest advice: do not build your own orchestration layer unless you have a dedicated payments engineering team and a genuine technical moat. The build vs. buy calculation almost always favors buying when you factor in provider-specific quirks, compliance updates, and the hidden cost of on-call engineering time. I’ve watched teams spend 18 months building something that a vendor platform would have delivered in 8 weeks.
The trend I find most interesting in 2026 is the convergence of payment orchestration and customer identity. The best routing decisions increasingly depend on customer-level data, not just card-level data. Retailers who invest in that data layer now will have a significant optimization advantage in three years.
— Vlad
How Sensepass makes this setup practical for retailers

If you are a retailer looking to put this guide into practice without building an orchestration layer from scratch, Sensepass is built precisely for this use case. Sensepass operates as a processor-agnostic orchestration layer and payment gateway, giving you access to 50+ card processors with a single integration. That means you get routing flexibility, failover protection, and least-cost optimization without maintaining separate integrations for each provider.
Sensepass integrates directly with the platforms your team already uses: NetSuite, SuiteCommerce, Oracle Xstore, Aptos, Shopify POS, BigCommerce, Storis, NCR, Dynamics365, and more. On the payment method side, Sensepass supports digital wallets including PayPal, Venmo, WeChat, Apple Pay, Google Pay, Alipay, and Amazon Pay. BNPL options include Klarna, Sezzle, ZIP, Splitit, and Afterpay. Financing is covered through WeGetFinancing and Affirm. Crypto payments run through BitPay and Coinbase. Pay by bank is available via Trustly and LinkMoney.
For retailers ready to move from single-processor dependency to true payment flexibility, the omnichannel payments guide for retailers is the best place to start understanding how all of these pieces connect in a real retail environment.
FAQ
What is a processor-agnostic payment setup?
A processor-agnostic payment setup is an architecture where your payment infrastructure can route transactions through multiple card processors and payment providers without hard-coding a dependency on any single one. This gives retailers flexibility, redundancy, and cost optimization across their entire payment stack.
How do I enable multi-processor payments without rebuilding my checkout?
You implement an orchestration layer with adapters that normalize each processor’s API into a unified internal format. Your checkout code calls one endpoint, and the orchestration layer handles routing, failover, and reporting across all connected processors.
What is the biggest risk in a processor-agnostic rollout?
The most common risk is reconciliation failure. When transactions flow through multiple processors simultaneously, relying on individual provider dashboards causes gaps. A centralized reconciliation engine that aggregates settlement files and webhook events from every PSP is required to prevent revenue leakage.
How long does a processor-agnostic implementation typically take?
Using a managed orchestration platform, most retailers can go live with multi-processor routing in 6 to 12 weeks. Building a custom orchestration layer in-house typically takes 6 to 18 months, depending on team size and the number of processors being integrated.
Do I need separate merchant accounts for each processor?
Yes. Each card processor requires its own merchant account with underwriting approval before you can route live transactions through it. Establish these relationships early in your preparation phase, as approval timelines vary significantly between providers.
Recommended
- 7 Essential Retail Payment Security Tips for Seamless Sales – Omnichannel payments at the Point Of Sale | Sensepass
- Essential Payment Gateway Selection Tips for Retailers – Omnichannel payments at the Point Of Sale | Sensepass
- Payment Gateway vs Processor: Complete Breakdown – Omnichannel payments at the Point Of Sale | Sensepass
- Payment Processor Differences – Impact on Retail Integration – Omnichannel payments at the Point Of Sale | Sensepass

 New York Office
260 Madison Ave Suite 8018 New York NY 10016

