
Retail Financing Option Setup Steps for Retailers
June 22, 2026
TL;DR:
- Retail financing allows customers to pay in installments while merchants receive funds upfront, boosting sales. Proper setup involves aligning offers with customer credit profiles, integrating natively at checkout, and continuously monitoring approval rates to maximize approval and conversion. Using a payment orchestration layer like Sensepass simplifies omnichannel implementation and ensures seamless data flow and growth.
Retail financing, known in the industry as point-of-sale lending or POS financing, is defined as a structured payment program that lets customers pay for purchases in installments while the merchant receives funds upfront. The retail financing option setup steps you follow directly determine your approval rates, customer experience, and cash flow. Platforms like Shopify Payments and lenders such as Affirm and WeGetFinancing have made these programs accessible to retailers of all sizes. Done right, POS financing increases sales conversion by removing the price barrier at checkout. This guide walks you through every stage, from pre-launch assessment to post-setup optimization.
What prerequisites do you need before setting up retail financing options?
Aligning financing offers with your customer credit profiles is the single most important step before you sign any lender agreement. Misalignment produces high decline rates and wastes your marketing budget. Start by auditing two numbers: your average basket size and the estimated credit tier of your typical buyer.
Your average basket size tells you which financing products make sense. Lenders like Affirm typically target purchases above $150, while buy now, pay later providers like Klarna and Afterpay work well for lower ticket items. Knowing your number prevents you from paying integration costs for a product your customers will rarely use.
Before you commit to a provider, work through this checklist:
- Channel scope: Decide whether you need in-store, online, or omnichannel financing. Each channel has different integration requirements and compliance rules.
- Merchant authorization: Confirm your business type is eligible. Some lenders exclude certain product categories, including firearms and medical devices.
- Fee tolerance: Review your gross margin against the typical fee range for POS financing before committing.
- Technology stack: List your current POS system and ecommerce platform. Compatibility determines how fast you can go live.
- Settlement timing: Confirm how quickly funds hit your account. Third-party lenders typically settle within 48 hours through your existing payment processor.
Pro Tip: Pull three months of transaction data before your first lender call. Showing a lender your average order value and return rate positions you as a prepared merchant and often earns better fee terms.
Third-party providers vs. in-house financing platforms: which is right for you?
The core tradeoff is control versus simplicity. Third-party POS financing providers handle underwriting, collections, and compliance for you. In-house or SaaS financing platforms give you ownership of customer data and underwriting logic, but you absorb the credit risk.
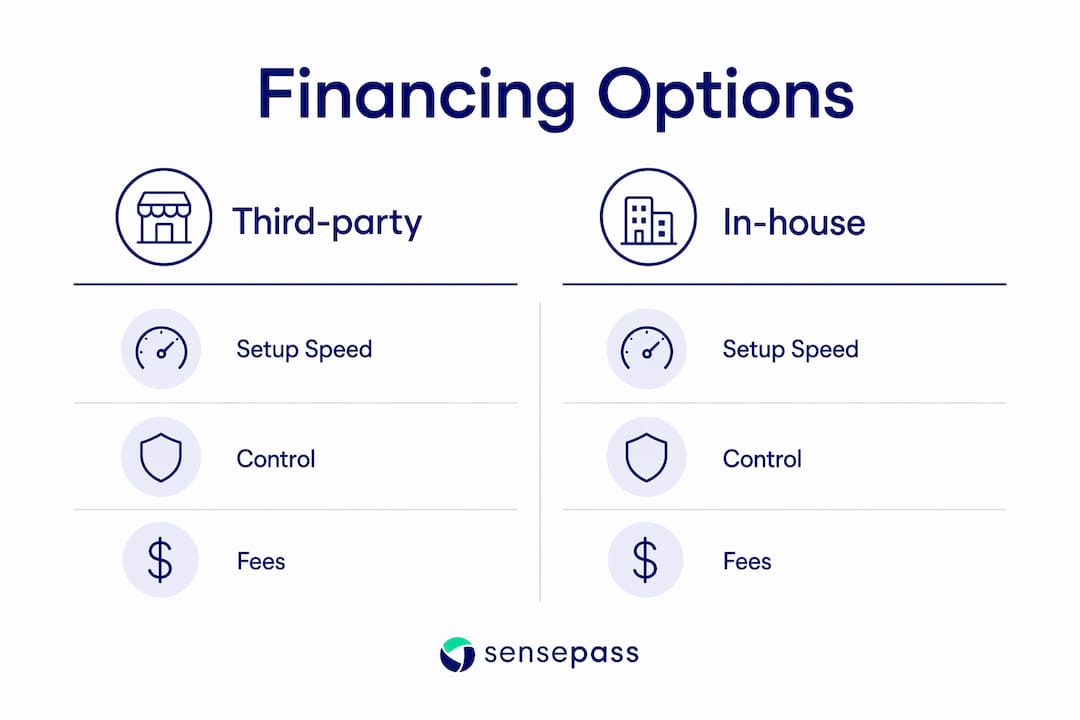
Third-party fees run 2%–6% per transaction, paid as a merchant discount rate. That cost is predictable and easy to model. In-house platforms require internal credit risk management infrastructure, which is a significant operational investment for most retailers.
| Factor | Third-party provider | In-house platform |
|---|---|---|
| Setup speed | Days to weeks | Weeks to months |
| Fee structure | 2%–6% per transaction | Platform license plus risk capital |
| Data ownership | Lender holds customer data | Retailer owns all data |
| Underwriting control | Lender sets criteria | Retailer sets criteria |
| Settlement speed | Within 48 hours | Varies by configuration |
| Best for | Small to mid-size retailers | Large retailers with credit expertise |
Most retail managers choose third-party providers first and migrate to hybrid models as volume grows. AI-driven POS platforms now blur this line by letting retailers maintain ease of use while retaining more data control than traditional third-party setups allowed.
Key questions to ask any third-party provider before signing:
- Who owns the customer relationship after approval?
- What happens to declined applicants? Can they be routed to a secondary lender?
- Does the integration support your existing POS system?
Pro Tip: Negotiate for a pilot period of 60–90 days with no long-term commitment. Most established providers will agree. This gives you real approval rate data before you commit to annual contract terms.
How to set up retail financing: the step-by-step technical workflow
A clear workflow for retail financing options prevents costly rework after launch. Follow these steps in order.
-
Complete merchant enrollment. Submit your business license, bank account details, and recent processing statements to your chosen lender. Affirm, WeGetFinancing, and similar providers typically complete eligibility verification within two to five business days.
-
Receive your API credentials and widget code. Your provider issues a merchant ID, API keys, and a JavaScript widget or SDK. Store these credentials securely before proceeding.
-
Integrate the financing widget into your checkout. For Shopify POS, this means enabling the financing app from the Shopify App Store and mapping it to your product catalog. For platforms like NetSuite, Oracle Xstore, Aptos, NCR, or Dynamics365, integration typically requires an API connection through your payment orchestration layer.
-
Activate on-site installment messaging. Place financing messaging on product pages, cart pages, and checkout. Showing monthly payment estimates at the product level, not just at checkout, increases the number of customers who apply. Automated platforms integrated with Shopify Payments approve approximately 95% of applications without additional documentation when installment messaging is properly enabled.
-
Configure processor-agnostic settlement. If you use a payment orchestration layer, map financing approvals to your existing merchant account so funds reconcile automatically. Real-time underwriting APIs process credit applications in seconds and reconcile payments within your existing merchant accounts without separate portals.
-
Run end-to-end testing before going live. Test every path in the customer journey using the table below.
| Test scenario | What to verify |
|---|---|
| Approved application | Correct order total, confirmation email, and settlement trigger |
| Declined application | Clear messaging, no checkout abandonment, alternative payment offered |
| Partial approval | Correct remaining balance shown, no double-charge risk |
| Installment messaging display | Accurate monthly amounts on product and cart pages |
| Mobile checkout | Widget loads correctly on iOS and Android |
Testing the entire financing journey, including declines and installment messaging, is critical to prevent alienating customers and ensure smooth checkout flows. A broken decline path is one of the most common causes of cart abandonment in newly launched financing programs.
What are the common pitfalls and best practices after your financing program goes live?
Retail financing is an ongoing optimization exercise, not a one-time setup. Continuous adjustment of lender routing and regular review of approval versus conversion rates separates programs that grow revenue from those that stall.
The most impactful post-setup practice is implementing waterfall financing logic. Waterfall routing sends declined applications across prime, near-prime, and subprime lenders automatically, maximizing approval rates without requiring customers to reapply. A customer declined by Affirm can be instantly routed to a secondary lender, all within the same checkout session.
Common mistakes to avoid:
- Redirect-based financing flows. Embedding financing natively in your checkout workflow converts significantly better than sending customers to an external lender page. Every redirect is a dropout risk.
- Skipping staff training. Your sales team must explain financing options accurately and ethically. Misstating terms creates compliance exposure and damages trust.
- Ignoring decline messaging. A declined customer who sees a clear, respectful message and an alternative payment option often completes the purchase. A customer who sees a generic error does not.
- Setting and forgetting approval rates. Review your approval rate monthly. A drop of more than a few percentage points signals a lender policy change or a shift in your customer mix.
“The retailers who get the most out of POS financing treat it like a marketing channel, not a payment feature. They monitor it weekly, test messaging, and adjust lender routing based on data.”
Pro Tip: Schedule a quarterly review with your lender’s merchant success team. Most providers share aggregate approval data and can flag routing issues you would not catch on your own.
Key takeaways
Retail financing setup succeeds when you align lender selection with your customer credit profile, integrate natively at checkout, and monitor approval rates continuously after launch.
| Point | Details |
|---|---|
| Audit before you sign | Match your average basket size and customer credit tier to lender requirements before committing. |
| Know your fee exposure | Third-party POS financing fees run 2%–6% per transaction; model this against your gross margin first. |
| Integrate natively | Embedding financing directly in checkout converts better than redirect-based flows. |
| Test every path | Verify approved, declined, and partial approval scenarios before going live to protect customer experience. |
| Use waterfall routing | Multi-lender routing maximizes approvals without requiring customers to reapply across providers. |
Why the integration layer matters more than the lender you pick
I have worked with retail managers who spent weeks evaluating Affirm versus WeGetFinancing, then launched on a POS system that could not pass the right data fields to either lender. The financing program failed within 30 days. The lender was not the problem. The integration was.
The most underrated step in the entire retail financing process guide is step three: connecting the financing widget to your actual checkout environment. Most providers make enrollment easy. The technical integration is where programs get delayed or quietly broken. I have seen merchants go live with installment messaging that showed the wrong monthly amounts because the widget was not receiving the correct cart total from their POS. Customers applied, got approved, and then saw a different number at confirmation. That destroys trust faster than a declined application.
My honest advice is to treat your payment orchestration layer as the foundation, not an afterthought. If your infrastructure can route a financing application to multiple lenders, reconcile the settlement, and pass clean data to your POS in real time, you have a program that can grow. If it cannot, you will rebuild it within a year. Invest in the integration first, then optimize the lender mix.
Sensepass and omnichannel retail financing
Retail managers who want to support financing options across every channel need a payment infrastructure that connects all the pieces without custom development for each provider.

Sensepass is a processor-agnostic payment orchestration layer that integrates with major retail platforms including NetSuite, SuiteCommerce, Oracle Xstore, Aptos, Shopify POS, BigCommerce, Storis, NCR, and Dynamics365. It supports financing providers WeGetFinancing and Affirm alongside BNPL options Klarna, Sezzle, ZIP, Splitit, and Afterpay. Digital wallets including PayPal, Venmo, Apple Pay, Google Pay, Alipay, Amazon Pay, and WeChat are also supported, as are crypto payments via BitPay and Coinbase, and pay-by-bank options through Trustly and LinkMoney. Sensepass gives merchants access to 50+ card processors for maximum flexibility. For a full picture of how these payment methods work together, the omnichannel payments guide covers the complete retail financing and payment integration framework.
FAQ
What are the core retail financing option setup steps?
The core steps are merchant enrollment, API and widget integration, installment messaging activation, processor-agnostic settlement configuration, and end-to-end testing of all application outcomes before launch.
How much do third-party POS financing providers charge?
Third-party providers charge between 2% and 6% per transaction as a merchant discount rate. The exact rate depends on your sales volume, average order value, and the lender’s risk assessment of your customer base.
How fast do merchants get paid with retail financing?
Merchants typically receive the full invoice amount within 48 hours of the transaction through their existing payment processor. The lender takes over billing and collections from the customer.
What is waterfall financing and why does it matter?
Waterfall financing automatically routes declined applications across multiple lenders, from prime to subprime, without requiring the customer to reapply. It maximizes approval rates and keeps customers in the checkout flow rather than sending them away after a single decline.
Do I need a separate POS system to offer retail financing?
No. Most financing providers offer API-driven integrations that connect to your existing POS or ecommerce platform. Platforms like Shopify POS, NetSuite, and Oracle Xstore all support financing widget integrations through their native app ecosystems or via a payment orchestration layer like Sensepass.
Recommended

 New York Office
260 Madison Ave Suite 8018 New York NY 10016

