
Secure Multi-Platform Payment Workflow: 2026 Guide
May 25, 2026
TL;DR:
- A secure multi-platform payment workflow integrates transaction initiation, authorization, and reconciliation across all customer channels to prevent errors and fraud. Implementing proper infrastructure, idempotency, webhook validation, and processor flexibility enhances operational efficiency and customer experience. Building this system proactively reduces fraud risks, improves reconciliation speed, and increases customer retention and revenue.
Running payments across multiple sales channels sounds straightforward until a duplicate charge appears, a webhook fires twice, or reconciliation takes your finance team half a day to untangle. A secure multi-platform payment workflow is not just about encrypting card data. It covers how transactions are initiated, authorized, recorded, and reconciled across every touchpoint your customers use. This guide walks you through the prerequisites, setup steps, common pitfalls, and the measurable outcomes that come from getting this right.
Table of Contents
- Key Takeaways
- What you need before building a secure multi-platform payment workflow
- How to set up your payment workflow step by step
- Common pitfalls in multi-platform payment setups
- What a well-built workflow delivers for your business
- Comparing payment methods and integration models
- My perspective on why most payment workflows fall short
- How Sensepass makes this easier to build and scale
- FAQ
Key Takeaways
| Point | Details |
|---|---|
| Security starts at infrastructure | Encryption, tokenization, and multi-factor authentication must be in place before connecting any payment channel. |
| Idempotency prevents costly errors | Both payment-side and webhook idempotency are required to stop duplicate charges and repeated state changes. |
| Processor flexibility matters | A processor-agnostic setup lets you choose from multiple card processors, avoiding lock-in and optimizing routing. |
| Unified dashboards reduce reconciliation work | Consolidated analytics across all channels cut manual reconciliation time and improve financial visibility. |
| Payment method variety drives conversions | Supporting digital wallets, BNPL, crypto, and pay-by-bank options directly improves checkout conversion rates. |
What you need before building a secure multi-platform payment workflow
Before you connect a single integration, your baseline infrastructure needs to be solid. Gaps here cause security incidents and operational headaches down the line.
Hardware and software requirements
Your setup will typically include in-store POS terminals, a mobile payment interface, and an online checkout layer. Each of these needs to talk to the same payment orchestration layer so transaction data does not get siloed. Payment orchestration platforms connect multiple payment providers and methods to optimize transaction success and simplify management, which means they are not optional for multi-platform operations.
Security protocols you cannot skip
Three controls form the foundation of cross-platform payment security: encryption at rest and in transit, tokenization to replace card data with non-sensitive tokens, and multi-factor authentication for all admin access. PCI DSS compliance is not a checkbox exercise. It is an ongoing practice that includes quarterly vulnerability scans, annual penetration testing, and strict access controls.
Pro Tip: Set up role-based permissions from day one. Modern payment automation platforms start with identity and access management so only the right people can authorize or modify payment configurations.
Payment methods your workflow should support
A complete multi-platform payment acceptance guide accounts for all the ways your customers want to pay. That includes:
- Digital wallets: PayPal, Apple Pay, Google Pay, Venmo, Alipay, WeChat, Amazon Pay
- BNPL options: Klarna, Afterpay, Sezzle, ZIP, Splitit
- Financing: Affirm, WeGetFinancing
- Crypto: BitPay, Coinbase
- Pay by bank: Trustly, LinkMoney
- Card payments: Credit and debit with processor flexibility across 50 or more card processors
Unified dashboards that consolidate payments, settlements, and analytics give your finance team real-time visibility across all of these channels without logging into five separate systems.
How to set up your payment workflow step by step
This is where most businesses either get it right or create technical debt they spend months fixing. Follow this sequence carefully.
-
Choose your integration model. You have three main options: hosted gateway (the provider handles the checkout UI), API-hosted (you control the UI, the provider handles processing), and self-hosted (full control, maximum responsibility). For most retailers, API-hosted offers the best balance of control and security without requiring you to store raw card data.
-
Connect your POS systems and online store to a single orchestration layer. This is the step that makes or breaks a secure omnichannel payments workflow. When your in-store NCR terminal, your Shopify POS, and your BigCommerce storefront all report to the same orchestration layer, you get one source of truth for transaction data. Platforms like NetSuite, SuiteCommerce, Oracle Xstore, Aptos, Dynamics365, and Storis can all be connected through the right orchestration setup.
-
Implement payment-side idempotency. Every payment request should include a unique idempotency key. This tells the processor: if you receive this exact request more than once due to a network retry, only process it one time. Payment idempotency prevents duplicate charges and inconsistent business states despite retries or network issues.
-
Secure and validate your webhooks. Webhooks are the messages your payment provider sends to notify your system when a transaction completes, fails, or is disputed. Webhook handlers must verify signature authenticity, handle retries gracefully, and perform safe multi-record database transactions to ensure reliability. Never process a webhook without first confirming the signature matches your provider’s shared secret.
-
Implement webhook idempotency separately from payment idempotency. These are two distinct concepts. Payment-side idempotency stops duplicate charges. Webhook idempotency stops your system from processing the same event twice when a provider retries delivery. Both are required.
-
Synchronize data across channels in real time. Your inventory, customer records, and payment statuses should update across all platforms the moment a transaction completes. This is what allows a customer to start a purchase on mobile and complete it in-store without friction.
-
Set up anomaly monitoring and alerts. Configure alerts for unusual transaction patterns: a sudden spike in declines, multiple retries on the same order, or transactions from unexpected geolocations. This is your early warning system for fraud.
Pro Tip: Run your full workflow in a sandbox environment with simulated retries, failed webhooks, and network timeouts before going live. Most payment incidents are discovered in production because testing only covered the happy path.
Common pitfalls in multi-platform payment setups
Knowing how to handle multi-platform payments also means knowing what not to do. These are the mistakes that show up most often.
-
Fragmented processing with no unified reconciliation. When each channel runs through a separate processor with no shared reporting layer, your finance team manually matches transactions against bank statements. This creates delays and errors that compound over time.
-
Skipping idempotency entirely. Many teams assume their payment provider handles this automatically. It does not, at least not on the webhook side. Ignoring idempotency at the webhook level means a single retry can trigger a double fulfillment, a double loyalty point award, or a duplicate refund.
-
No webhook signature verification. Accepting webhook payloads without verifying the signature means any system can send your server a fake “payment successful” event. This is an exploitable vulnerability, not a theoretical risk.
-
Locking into a single card processor. A setup that only supports one processor gives you no fallback when that processor experiences downtime, and no leverage to negotiate better rates. A processor-agnostic approach gives you the routing flexibility to avoid this.
-
Inconsistent customer data across channels. When your in-store and online systems store separate customer profiles, you cannot offer unified loyalty programs, purchase history, or personalized payment experiences. This directly affects repeat purchase rates.
-
Ignoring mixed-mode payments. Retailers can accept split payment combinations like 40% digital wallet and 60% credit card, but this requires your workflow to handle partial authorizations correctly. Systems that only process single-method transactions will reject these at checkout.
-
Falling behind on compliance updates. PCI DSS requirements evolve. Teams that treat compliance as a one-time setup rather than an ongoing program leave themselves exposed to both fraud and penalties.
What a well-built workflow delivers for your business
Getting the setup right has measurable consequences. Here is what businesses consistently see once a secure, unified payment workflow is operating correctly.
Efficiency and financial visibility
Payment automation reduces late payments, minimizes manual errors, and connects payment data directly to accounting software, making reconciliation faster and more accurate. Finance teams that previously spent hours on daily reconciliation get that time back. A unified dashboard means one place to review all payment statuses, settlements, and disputes across every channel.
Customer experience and retention
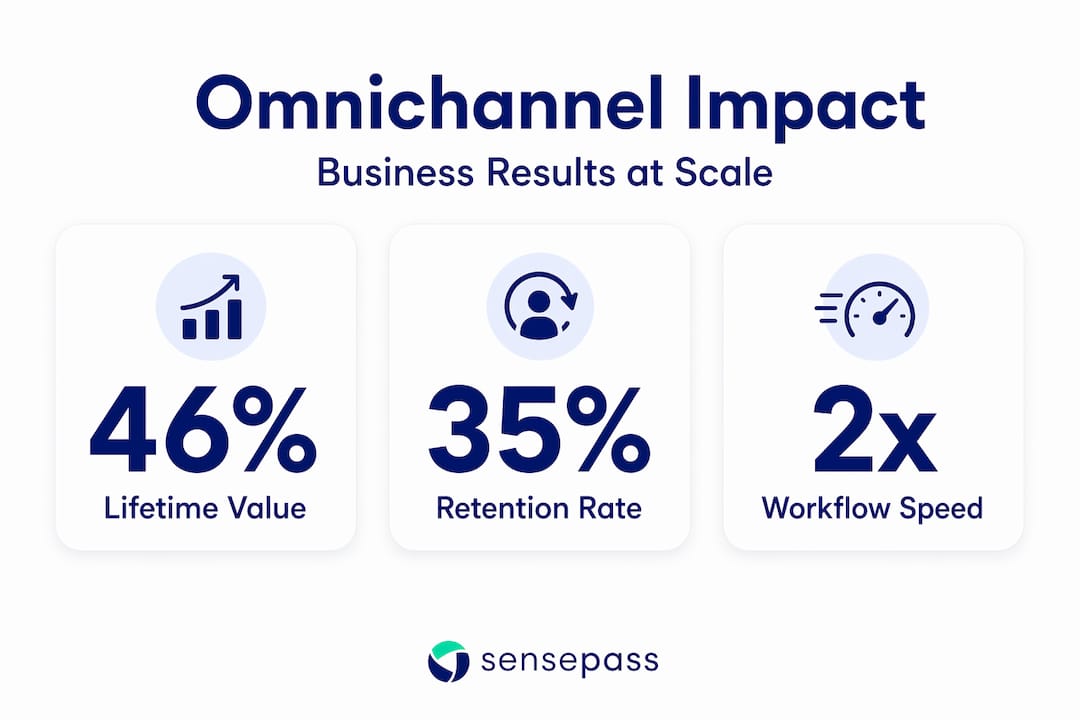
Omnichannel retail delivers 46% higher customer lifetime value and 35% higher retention rates compared to fragmented channel operations. Customers who can pay their preferred way, whether that is Apple Pay at the register or Klarna at online checkout, complete purchases at higher rates and return more often.
Conversion and revenue impact
| Metric | Fragmented workflow | Unified secure workflow |
|---|---|---|
| Reconciliation time | 2 to 4 hours daily | Under 30 minutes daily |
| Duplicate transaction rate | Higher without idempotency | Near zero with idempotency keys |
| Checkout conversion | Limited by payment method gaps | Higher with wallet, BNPL, and crypto support |
| Fraud and chargeback exposure | Elevated without anomaly monitoring | Reduced with real-time alerts |
| Customer lifetime value | Baseline | Up to 46% higher with omnichannel |
Reducing fraud exposure also matters for the bottom line. Chargebacks carry fees, damage processor relationships, and in high volumes can trigger account reviews. A workflow with proper authorization controls, anomaly detection, and webhook validation keeps chargeback rates low.
Comparing payment methods and integration models
Not every payment method or integration approach fits every business. Here is a practical comparison to help you make informed choices for your multi-platform setup.
| Option | Best for | Security notes | Cost consideration |
|---|---|---|---|
| Credit and debit cards | All business types | Requires PCI DSS compliance | Processing fees vary by processor |
| Apple Pay and Google Pay | Mobile and contactless retail | Tokenized, no card data stored | No extra fees beyond standard processing |
| BNPL (Klarna, Afterpay, etc.) | High-ticket retail | Handled by BNPL provider | Higher conversion, additional merchant fees |
| Crypto (BitPay, Coinbase) | Tech-forward retailers | Decentralized, lower fraud risk | Price volatility is a consideration |
| Pay by bank (Trustly, LinkMoney) | B2B and high-value orders | Direct bank authorization | Lower processing costs than cards |
| Hosted gateway | Smaller teams, simpler setups | Provider handles PCI scope | Less UI control |
| API-hosted | Mid to enterprise retailers | You control UI, provider handles data | More development overhead |
For gateway selection decisions, the key trade-off is between control and compliance scope. API-hosted integrations give you the most flexibility but require your development team to handle the integration carefully. Hosted gateways reduce your PCI scope significantly, which is worth the reduced UI flexibility for many businesses.
My perspective on why most payment workflows fall short
I’ve worked with enough retail payment setups to say this plainly: most workflow failures are not caused by bad technology. They come from teams that treat payment infrastructure as a one-time configuration rather than an ongoing system that needs maintenance and architecture decisions made deliberately.
The two areas I see neglected most consistently are idempotency and webhook validation. Every team I’ve talked to assumes their provider handles both automatically. They do not. Idempotency at the webhook level is your responsibility, and skipping it is how you end up sending a customer two fulfillment emails and refunding a transaction that was already successfully processed.
The other pattern I’ve noticed is processor lock-in. Businesses sign with one processor for convenience and then discover they have no fallback when that processor goes down, and no negotiating position when rates go up. A processor-agnostic approach, where you can route to 50 or more processors based on availability, cost, or geography, is not just a nice feature. It is a resilience strategy.
What actually makes a secure payment workflow effective long-term is not any single feature. It is the combination of real-time data synchronization, proper idempotency, verified webhooks, and the flexibility to add or swap payment methods as customer preferences change. Businesses that build this way stop reacting to payment incidents and start using their payment data proactively.
— Vlad
How Sensepass makes this easier to build and scale
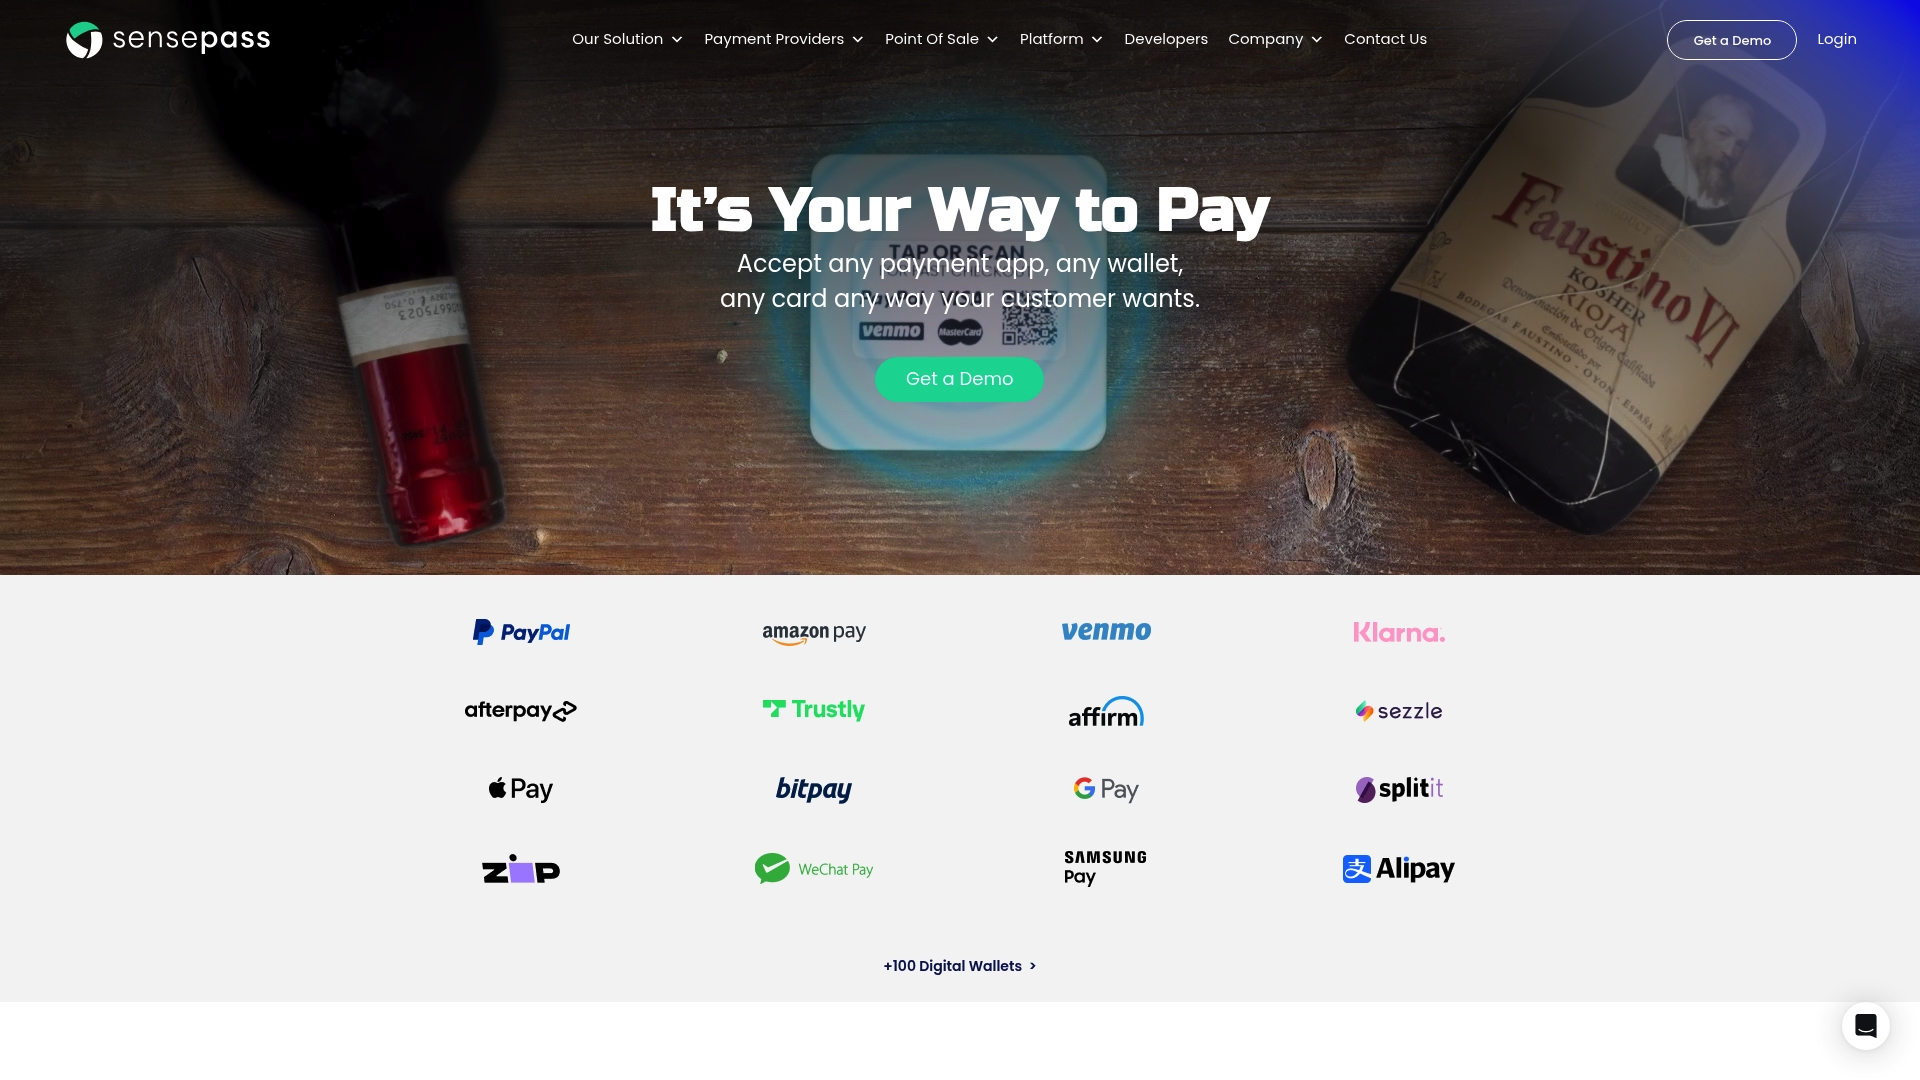
Sensepass is an orchestration layer built specifically for retailers who need to manage payments across multiple platforms without compromising security or flexibility. It integrates directly with NetSuite, SuiteCommerce, Oracle Xstore, Aptos, Shopify POS, BigCommerce, Storis, NCR, Dynamics365, and more. That means you are not building custom connectors for every system. You are connecting your existing infrastructure to a unified payment layer that handles routing, reconciliation, and reporting in one place.
On the payment method side, Sensepass supports digital wallets including PayPal, Venmo, WeChat, Apple Pay, Google Pay, Alipay, and Amazon Pay. It covers BNPL through Klarna, Sezzle, ZIP, Splitit, and Afterpay, financing through WeGetFinancing and Affirm, crypto via BitPay and Coinbase, and pay-by-bank options through Trustly and LinkMoney. And because Sensepass is processor-agnostic, you choose from 50 or more card processors. You keep the flexibility to optimize routing for cost, approval rates, or geography.
For a full breakdown of how to unify your payment channels, the omnichannel payments guide is a good starting point.
FAQ
What is a secure multi-platform payment workflow?
A secure multi-platform payment workflow is a structured system for accepting, processing, and reconciling payments across multiple sales channels, such as in-store, online, and mobile, with encryption, tokenization, and fraud controls applied consistently across all of them.
How do I prevent duplicate charges in a multi-platform setup?
Use idempotency keys on every payment request and implement separate webhook idempotency to prevent repeated event processing. These two controls together stop duplicate charges caused by network retries or provider-side webhook re-deliveries.
What payment methods should a multi-platform workflow support?
At minimum, your workflow should support credit and debit cards, digital wallets like Apple Pay and Google Pay, at least one BNPL option, and pay-by-bank methods. Supporting a broader range directly improves checkout conversion across different customer segments.
Why is processor-agnostic architecture important?
A processor-agnostic setup lets you route transactions to different card processors based on cost, availability, or performance. This gives you a fallback during processor outages and the flexibility to negotiate better rates as your transaction volume grows.
How does omnichannel payment unification affect customer retention?
Omnichannel retail operations deliver 35% higher retention rates compared to fragmented channel setups, primarily because customers get consistent experiences and payment options regardless of where or how they shop.
Recommended
- Master Payment Processing Best Practices for Your Business – Omnichannel payments at the Point Of Sale | Sensepass
- Payment Security Best Practices for Omnichannel Retailers – Omnichannel payments at the Point Of Sale | Sensepass
- Mastering the Omnichannel Payment Workflow Guide – Omnichannel payments at the Point Of Sale | Sensepass
- Seamless retail payment workflow: step-by-step guide – Omnichannel payments at the Point Of Sale | Sensepass

 New York Office
260 Madison Ave Suite 8018 New York NY 10016

