
Step by Step Multi-Currency Acceptance for Retailers
June 26, 2026
TL;DR:
- Implementing multi-currency acceptance increases international conversion rates by up to 30 percent through localized checkout experiences.
- Successful adoption requires a five-step process including market selection, currency model, payment method mapping, technical integration, and operational setup.
Multi-currency acceptance is defined as the ability to display prices, collect payments, and settle funds in more than one currency across a single checkout experience. Retailers and eCommerce businesses that implement a structured, step by step multi-currency acceptance process increase international conversion rates by 20–30%, because localized checkout removes the friction of unexpected bank fees and unfamiliar pricing. Platforms like Sensepass, along with multi-currency payment gateways, give merchants the infrastructure to make this work at scale. The standard industry term for this practice is multi-currency payment processing, and it covers three distinct layers: what customers see, what gets settled, and how FX risk is managed.
What does step by step multi-currency acceptance actually involve?
The 5-step implementation process for accepting multiple currencies covers market selection, currency model choice, payment method mapping, technical integration, and operational setup. Most retailers only complete the first two steps and call it done. That gap is where conversion losses and FX surprises happen. Each step builds on the last, so skipping one creates compounding problems downstream.
How do you prioritize markets and select currencies to support?
Start with your analytics, not your assumptions. Pull geographic data from Google Analytics, Shopify, or your POS reporting to identify which countries generate the most traffic but the lowest conversion rates. That gap between visits and purchases is where multi-currency investment pays off fastest.
Once you identify your top three to five underperforming regions, look at their dominant currencies. The euro, British pound, Canadian dollar, Australian dollar, and Japanese yen cover a large share of cross-border eCommerce volume. Prioritize currencies that appear repeatedly in your abandoned cart data and in your customer support inquiries about pricing.
Use these criteria to build your initial shortlist:
- Traffic volume: Countries sending more than 5% of your total sessions deserve a currency review.
- Cart abandonment rate: Regions with above-average abandonment often signal a pricing or payment friction problem.
- Average order value: Higher AOV markets justify the operational cost of adding a new currency.
- Local payment norms: Some markets rely on bank transfers or digital wallets more than cards.
Pro Tip: Limit your first rollout to two or three currencies. Overextending to 15 currencies at launch creates reconciliation chaos without proportional revenue gain. Add currencies based on data, not geography ambition.
Presentment vs. settlement: which currency model is right for you?
The currency model you choose determines your FX exposure and your margin. Most retailers confuse these two concepts, and that confusion is expensive.
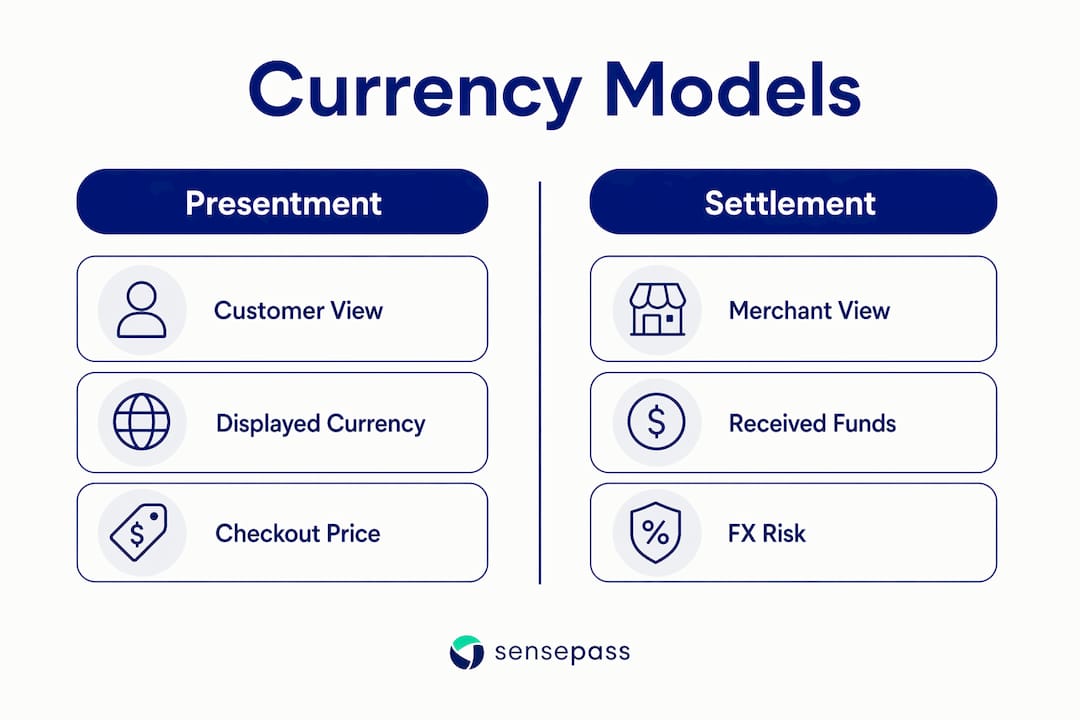
Presentment is what the customer sees at checkout. A shopper in Germany sees €89 instead of $97. Settlement is what actually lands in your bank account. These are not the same thing, and treating them as identical is the most common mistake in multi-currency setup.
| Model | What customer sees | What you receive | FX risk |
|---|---|---|---|
| Home currency billing | Local currency display only | Base currency (e.g., USD) | Borne by customer via DCC |
| Multi-currency presentment | Local currency | Base currency after conversion | Borne by gateway |
| True multi-currency settlement | Local currency | Local currency held in account | Borne by merchant, manageable |
Stealth conversion is the hidden danger in home currency billing. The gateway converts funds before they reach your account, often at poor rates with undisclosed margins. True multi-currency settlement, where you hold foreign currency balances rather than forcing daily conversions, gives you control over when and at what rate you convert.
Settlement flexibility directly affects your FX risk strategy. Merchants with high volume in euros or British pounds often benefit from holding those balances and converting in batches when rates are favorable.
Pro Tip: Ask your payment provider directly: “Do you settle in the customer’s currency or convert before sending funds?” If they cannot answer clearly, that is your answer.
How do you map payment methods by market for optimal conversion?
Currency display alone does not close the sale. Payment method fit is as important as currency acceptance, and neglecting it leaves conversion gains on the table even after you have localized your pricing.
Different markets rely on fundamentally different payment rails. A German shopper expects SEPA bank transfer options. A Chinese customer expects Alipay or WeChat Pay. A US customer may want Klarna or Afterpay for a high-ticket item. Matching your checkout to these expectations is what separates a localized experience from a translated one.
Build a payment method matrix by region before you configure anything technically. Your matrix should cover:
- Cards: Visa and Mastercard work globally, but local card networks like UnionPay in China matter in specific markets.
- Digital wallets: PayPal, Apple Pay, Google Pay, Venmo, Alipay, Amazon Pay, and WeChat cover most major markets.
- Buy Now Pay Later: Klarna dominates Europe and parts of North America. Afterpay, Sezzle, ZIP, and Splitit serve different audience segments.
- Pay by Bank: Trustly and LinkMoney handle bank-to-bank transfers in markets where card penetration is lower.
- Crypto: BitPay and Coinbase Commerce serve a growing segment of digital-native buyers.
- Financing: WeGetFinancing and Affirm work well for higher-ticket retail purchases in the US market.
The operational challenge is maintaining this matrix as payment preferences shift. Assign one person or team to review regional payment data quarterly and update your checkout configuration accordingly.
How do you integrate multi-currency payments into your platform?
Technical integration is where the plan becomes real. The right approach depends on your platform, but the core steps follow a consistent sequence regardless of whether you run Shopify, Magento, WooCommerce, or a custom build.
- Connect a currency conversion API. Real-time exchange rate feeds from your payment provider keep displayed prices accurate. Stale rates create pricing discrepancies that erode trust.
- Configure currency detection. Multi-currency gateways detect location using IP address, browser language, or billing address to display local prices automatically. Enable manual currency selection as a fallback so customers can override the default.
- Align checkout, invoicing, and reporting. The currency shown at checkout must match the invoice and the reporting dashboard. Mismatches create reconciliation errors and customer complaints.
- Set up settlement accounts. Decide which currencies you will hold and which you will convert immediately. Configure your payment provider accordingly before going live.
- Verify PCI DSS compliance. Payment gateways use PCI DSS encryption and tokenization to secure card data. Confirm your integration does not break compliance when adding new currency flows or payment methods.
Sensepass integrates with NetSuite, SuiteCommerce, Oracle Xstore, Aptos, Shopify POS, BigCommerce, Storis, NCR, and Dynamics365, among others. Its payment API architecture supports real-time currency handling across both online and in-store channels. Sensepass is also processor-agnostic, giving merchants access to 50+ card processors so you are not locked into a single rate or routing path.
Pro Tip: Test your multi-currency checkout with real cards from each target market before launch. Sandbox testing misses regional card authorization quirks that only appear with live transactions.
Managing FX exposure, reconciliation, refunds, and customer support
Operational readiness is the layer most merchants skip, and it is the one that causes the most post-launch pain. Setting up multi-currency payments without operational protocols is like opening a new store without a cash register process.
The key operational areas to address before going live:
- FX gains and losses: Track these separately in your accounting system. Batch conversions at favorable rates rather than converting every transaction individually.
- Reconciliation: Accounting complexity grows significantly with multi-currency payments. Use automated reconciliation tools that can match transactions across currencies and flag discrepancies.
- Refunds: Exchange rate timing differences on refunds require manual adjustments when the rate at refund time differs from the rate at purchase time. Document your refund policy clearly and train your support team on how to explain rate differences to customers.
- Customer support scripts: Write region-specific scripts that address the four questions customers ask most at checkout.
- Fee transparency: Customers need clear answers to four questions before completing a purchase: What am I paying? In which currency? What payment methods are accepted? Are taxes and fees included?
“Do not overlook support workflows and refund policies tailored regionally. They are the difference between a customer who completes a purchase and one who files a chargeback.”
Review your payment processing best practices for FX management and reconciliation at least quarterly. Currency volumes shift, and your operational setup needs to keep pace.
Key Takeaways
Successful multi-currency acceptance requires completing all five implementation layers: market selection, currency model, payment method mapping, technical integration, and operational setup.
| Point | Details |
|---|---|
| Prioritize by data | Target regions with high traffic but low conversion before expanding to new markets. |
| Separate presentment from settlement | True multi-currency settlement gives you FX control; stealth conversion does not. |
| Map payment methods by region | Currency display without local payment methods still produces high cart abandonment. |
| Align all systems at integration | Checkout, invoicing, and reporting must show the same currency to avoid reconciliation errors. |
| Build operational protocols first | Refund policies, FX tracking, and support scripts must be ready before launch, not after. |
Why most multi-currency rollouts fail in the first 90 days
I have worked with retailers who spent months configuring multi-currency pricing and then watched their international conversion rates barely move. The pattern is almost always the same. They solved the display problem and ignored everything else.
The distinction between presentment and true multi-currency settlement is not a technical detail. It is a financial one. When a gateway converts your funds before they reach your account, you lose control of your margin on every international transaction. That loss compounds quietly until someone runs a quarterly FX report and finds a gap they cannot explain.
The other mistake I see constantly is launching with currencies but not with the payment methods those markets actually use. A German shopper who sees a euro price but cannot pay by bank transfer is still going to abandon the cart. The currency was never the barrier. The payment method was.
My recommendation is to treat the first rollout as a pilot, not a full launch. Pick two markets, two currencies, and the three most common payment methods in each. Measure conversion, refund rates, and support ticket volume for 60 days. Then expand based on what the data shows, not what the roadmap assumed.
The retailers who get multi-currency right are the ones who treat it as an ongoing operational practice, not a one-time configuration project.
— Vlad
How Sensepass supports multi-currency acceptance for retailers
Retailers who want to move from planning to live implementation need a platform that handles both the technical and operational layers without requiring a custom build for every new market.

Sensepass is built for exactly this use case. It connects to NetSuite, SuiteCommerce, Oracle Xstore, Aptos, Shopify POS, BigCommerce, Storis, NCR, and Dynamics365, covering the POS and eCommerce platforms most retailers already run. Its payment method support spans digital wallets (PayPal, Venmo, WeChat, Apple Pay, Google Pay, Alipay, Amazon Pay), BNPL options (Klarna, Sezzle, ZIP, Splitit, Afterpay), financing (WeGetFinancing, Affirm), crypto (BitPay, Coinbase), and Pay by Bank (Trustly, LinkMoney). Sensepass is processor-agnostic, giving you access to 50+ card processors so you control routing and rates. Explore the full omnichannel payment capabilities to see how Sensepass fits your specific retail setup.
FAQ
What is multi-currency payment acceptance?
Multi-currency payment acceptance is the ability to display prices and collect payments in a customer’s local currency. It covers both what customers see at checkout and how funds are settled into the merchant’s account.
What is the difference between presentment and settlement in multi-currency payments?
Presentment is the currency displayed to the customer. Settlement is the currency received by the merchant. True multi-currency requires both to align; otherwise, the gateway converts funds at its own rate before they reach your account.
How many currencies should a retailer support at launch?
Start with two to three currencies tied to your highest-traffic, lowest-conversion markets. Expanding too quickly creates reconciliation and operational complexity without proportional revenue gain.
Why do refunds get complicated with multi-currency payments?
Exchange rates change between the time of purchase and the time of refund. That difference creates a discrepancy in the refund amount, which requires manual accounting adjustments and a clear customer-facing refund policy.
Does Sensepass support multi-currency payment acceptance?
Sensepass supports a broad range of payment methods and integrates with major retail POS and eCommerce platforms. Its processor-agnostic architecture and multi-method checkout setup give retailers the flexibility to configure currency and payment options by market.
Recommended
- Essential Payment Gateway Selection Tips for Retailers – Omnichannel payments at the Point Of Sale | Sensepass
- How to Set Up Multi-Method Checkout for Retailers – Omnichannel payments at the Point Of Sale | Sensepass
- How to Accept Digital Payments Seamlessly Across Channels – Omnichannel payments at the Point Of Sale | Sensepass
- Payment Gateway Selection Tips for Retail Success – Omnichannel payments at the Point Of Sale | Sensepass

 New York Office
260 Madison Ave Suite 8018 New York NY 10016

