
How to Accept Bank Transfers: A Stepwise 2026 Guide
July 22, 2026
Accepting a bank transfer correctly means following a specific sequence of steps, not just waiting for money to appear. Stepwise bank transfer acceptance is the controlled process of collecting payer details, verifying identity, initiating the transfer, monitoring its status, and confirming receipt before releasing goods or recording the payment. Get any step wrong and you risk fraud, delayed funds, or reconciliation headaches.
How to accept bank transfers step by step
The bank transfer approval steps below apply whether you’re an individual receiving a one-time payment or a small business processing regular transactions.
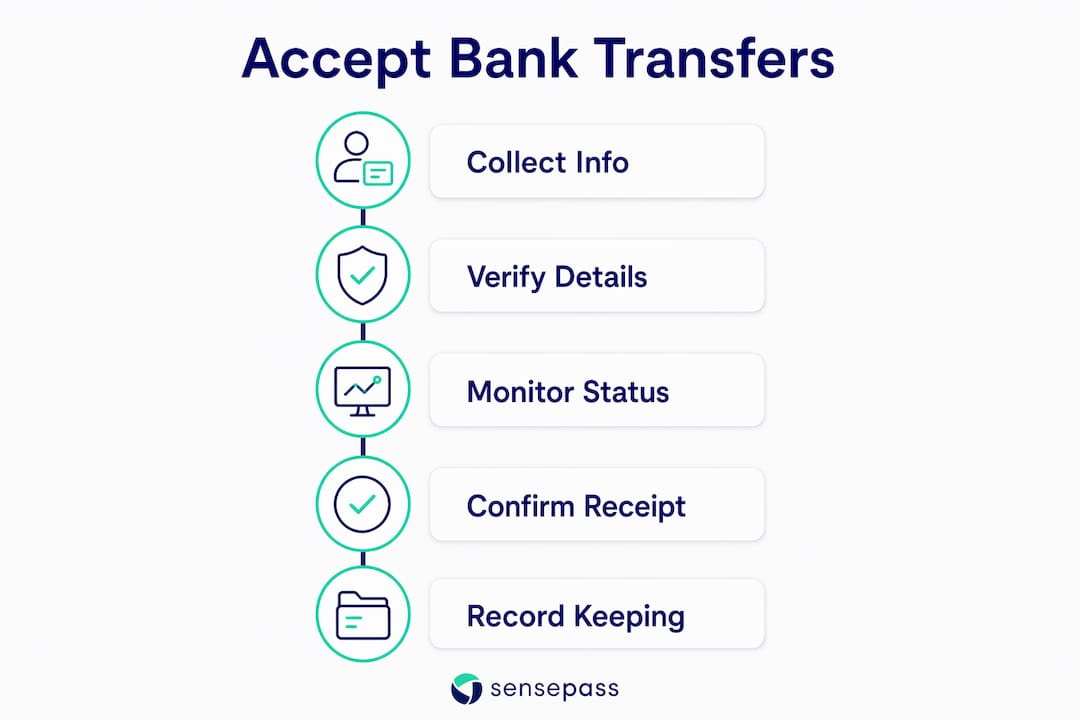
- Collect banking details. Get the payer’s full name, bank account number, and routing number. For business payments, also request the bank name and any reference or invoice number.
- Verify payer identity. Confirm the sender is who they claim to be before the transfer begins. Request a government-issued ID or use your bank’s identity verification tools for larger amounts.
- Choose your transfer method. Decide between ACH, wire transfer, or an instant payment rail based on urgency and cost. Each has different timelines and fees (covered in the next section).
- Initiate or instruct the transfer. Either direct the payer to your bank’s receiving details or, if you’re pulling funds, initiate the request through your banking portal.
- Monitor transfer status. Log into your bank’s online portal or mobile app and watch for status labels: Pending, Processing, or Completed. Most portals let you filter by date or amount.
- Confirm funds arrival. Do not release goods or mark an invoice paid until the funds post to your account, not just when the status reads “Completed” on the sender’s end.
- Save your records. Download the PDF receipt or transaction log immediately. Note the confirmation number and store it with the related invoice or contract.
What timelines and approval phases should you expect?
Planning around transfer timelines prevents cash flow surprises. ACH transfers generally take a few business days to complete, while domestic wire transfers often complete on the same business day if submitted before the bank’s cutoff time.
- ACH (Automated Clearing House): Processed in batches, not individually. Expect 1–3 business days. Same-day ACH is available at many banks for transfers submitted before the cutoff.
- Wire transfers: Processed individually, which is why they’re faster. Wires sent after the cutoff typically process the next business day.
- Instant payments: Rails like FedNow and RTP confirm delivery within seconds. Both the sending and receiving bank must support the rail for it to work.
- Weekends and holidays: Cutoff times, weekends, and bank holidays commonly delay ACH and wire transfers. A payment submitted late Friday may not begin processing until Monday morning.
Transfer status labels explained: Pending means your bank accepted the instruction but hasn’t released funds. Processing means the payment is moving through the clearing network. Completed means the sending bank finished its part. Failed or Returned means something went wrong, usually a mismatched account number or insufficient funds.
What fees and costs come with bank transfers?
Fee structures vary by method and by institution, so knowing the ranges helps you choose the most cost-effective option.
- ACH transfers are typically low cost or free for standard processing. Same-day ACH may carry a small per-transaction fee depending on your bank.
- Wire transfers carry higher fees, often charged by both the sending and receiving bank. Domestic wires generally cost less than international ones.
- Instant payment services may charge a fee for immediate fund access, particularly when transferring to an external bank account rather than keeping funds within the platform.
- Receiving fees: Some banks charge the recipient a fee for incoming wires. Check your account agreement so you’re not caught off guard.
- Manual review triggers: Transfers over $10,000 trigger Currency Transaction Reports under FinCEN rules. Banks may also manually review transfers above certain amounts to prevent fraud, which can add processing time.
Understanding these cost layers upfront lets you decide whether ACH’s lower cost justifies the wait, or whether a wire’s speed is worth the premium for a time-sensitive deal.
How do you verify that a bank transfer was successful?
A “Completed” status on the sender’s side does not guarantee the money is in your account. That status means the sender’s bank released the funds into the network. The receiving bank still needs to process and post them.
- Check your own transaction history, not the sender’s confirmation screenshot.
- Look for the funds posted to your account balance, not just a status update.
- Obtain the transaction reference or confirmation number from the sender and match it to your records.
- Download a PDF receipt or transaction log as official proof.
- If the sender’s status shows “Completed” but your account shows nothing, request a formal trace from your bank. This opens an official investigation where your bank contacts the receiving institution directly, distinct from a standard customer service call.
Pro Tip: Business transfers sometimes arrive under the payment provider’s name or a reference number rather than the sender’s name. If you can’t locate a transfer, search by amount and date rather than sender name.
How do you protect yourself from fraud during transfers?
Security in bank transfers is not passive. You need active habits to stay protected.
- Verify sender identity before accepting. Fraudsters sometimes initiate transfers and then claim overpayment, requesting a refund before the original transfer reverses.
- Use two-factor authentication on your banking portal. Most major US banks support this, and it significantly reduces unauthorized access risk.
- Watch for fraud holds. Large or unusual transfers may trigger an automatic hold. Your bank will notify you, and you may need to confirm the transaction before funds release.
- Never share your full account number over email or unencrypted channels. Use secure messaging within your bank’s portal when communicating transfer details.
- Transfers over $10,000 trigger mandatory Currency Transaction Reports to FinCEN, and banks may flag transfers over $3,000 for manual review.
Pro Tip: Reconcile your accounts weekly. If a transfer amount, sender name, or reference number looks off, call the sender directly using a phone number you already have, not one provided in the suspicious message.
What happens behind the scenes when a bank transfer clears?
The gradual bank transfer process involves far more than two banks exchanging a number. Bank transfers pass through a sequential chain of encrypted steps before money posts to your account.
- Initiation: You or the payer submits transfer details through a banking portal or payment gateway.
- Data encryption and tokenization: Payment data is encrypted and tokenized before leaving the originating system.
- Gateway routing: The encrypted data routes through a payment gateway to the acquiring bank, which processes payments on the merchant’s behalf.
- Issuing bank verification: The payer’s bank checks account balance, validates account details, and assesses fraud risk. Two-factor authentication, such as a one-time passcode or biometric check, is often triggered here.
- Authorization decision: The issuing bank approves or declines based on available funds, transaction limits, and compliance rules. An approval message travels back through the same network path.
- Response transmission: The authorization response moves from the issuing bank back through the card network, acquiring bank, and gateway to the merchant or recipient.
- Clearing and settlement: Banks reconcile transaction details, then the actual funds transfer. ACH uses batch clearing over 1–3 days; wires settle individually, often the same day.
Platforms like Sensepass handle this orchestration transparently for merchants, connecting to payment gateways and alternative payment methods across NetSuite, SuiteCommerce, Oracle Xstore, Aptos, Shopify POS, BigCommerce, Storis, NCR, and Dynamics365.
How do international bank transfers work?
International transfers add layers of compliance, currency conversion, and correspondent banking to the standard process. The SWIFT network handles the secure messaging between institutions, though SWIFT itself does not move money. Actual settlement occurs through correspondent banking relationships or central bank systems.
Expect international transfers to take 1–5 business days, with delays possible from currency conversion, compliance checks, or intermediary banks in the chain. Always provide the sender with your IBAN or SWIFT/BIC code alongside your account and routing numbers. For incoming international wires, confirm with your bank whether it charges a receiving fee and whether currency conversion happens automatically or requires your instruction.
How do you set up your bank information to receive transfers?
Getting your receiving details right prevents the most common cause of failed transfers: incorrect account information.
- Gather your routing number and account number. Your routing number identifies your bank; your account number identifies your specific account. Both appear on a check or in your online banking portal.
- Confirm account type. Specify whether the account is checking or savings, since some transfer systems route differently based on account type.
- For business accounts, provide your legal business name exactly as it appears on the account. Mismatches between the name on file and the name the sender uses can trigger holds.
- For wire transfers, you’ll also need your bank’s full name and address, and sometimes an intermediary bank’s details for international wires.
- Test with a small transfer before relying on a new account for large payments. A $1 test confirms the routing is correct before anything significant is at stake.
Retail businesses using platforms like Sensepass can connect Pay by Bank options such as Trustly and LinkMoney directly to their POS or eCommerce setup, alongside digital wallets like PayPal, Apple Pay, Google Pay, and Venmo, plus BNPL options including Klarna, Afterpay, Sezzle, ZIP, and Splitit. Sensepass is processor-agnostic, giving merchants access to 50+ card processors for maximum flexibility.
Best practices for record keeping after you accept a transfer
Good records protect you in disputes and make tax time far less painful.
Every accepted transfer should generate at least three records: the transaction confirmation from your bank, the invoice or agreement it relates to, and any communication with the sender confirming the amount and purpose. Store these together, either in a cloud accounting tool or a dedicated folder organized by date and payer.
Reconcile your bank statement against your invoices at least monthly. If you’re running a business, match each incoming transfer to an open receivable and mark it closed only when the funds post, not when the sender says they’ve sent it. For high-volume operations, retail network infrastructure that supports real-time payment data can make this reconciliation faster and more reliable.
Keep records for at least three years for standard transactions, and seven years for anything that touches a tax filing or a contract with a dispute clause.
How to contact your bank for support and dispute resolution
When a transfer goes wrong, the path to resolution depends on acting quickly and having your documentation ready.
Start with your bank’s online portal or mobile app. Most US banks let you flag a transaction directly from your account history, which creates a case number faster than calling. If the portal isn’t enough, call the bank’s dedicated wire or ACH support line, not the general customer service number, since transfer specialists have direct access to clearing network records.
For a missing or stalled payment, request a formal trace. Give the representative your confirmation number, the exact dollar amount, the transfer date, and the sending bank’s name. The bank will open an investigation, contact the receiving institution, and provide a written report. Under the Electronic Fund Transfer Act (Regulation E), your bank has specific investigation deadlines for consumer ACH transactions. Wire transfers follow different rules under UCC Article 4A, which most states have adopted, and liability assignments differ between the two frameworks.
Key Takeaways
Stepwise bank transfer acceptance requires collecting verified banking details, monitoring status labels carefully, and confirming funds post to your account before treating a payment as complete.
| Point | Details |
|---|---|
| ACH vs. wire timelines | ACH takes 1–3 business days; domestic wires often complete the same day if submitted before cutoff. |
| “Completed” does not mean received | That status means the sender’s bank released funds, not that your account has been credited yet. |
| FinCEN reporting threshold | Transfers over $10,000 trigger mandatory Currency Transaction Reports; banks may review transfers over $3,000. |
| Formal trace for missing payments | Request a formal trace from your bank to open an official investigation beyond standard customer support. |
| Record keeping minimum | Keep transfer records for at least three years, and seven years for anything tied to a tax filing or contract. |
If you’re running a retail business and want to accept bank transfers alongside digital wallets, BNPL, crypto, and more, Sensepass connects all of it through one orchestration layer. It integrates with NetSuite, Shopify POS, Oracle Xstore, BigCommerce, and a dozen other platforms, with Pay by Bank options like Trustly and LinkMoney built in. Explore omnichannel payment options and see how Sensepass fits your setup.

Recommended
- How to Add Bank Transfer Options for Retailers – Omnichannel payments at the Point Of Sale | Sensepass
- Pay by Bank Integration: A Step-by-Step Business Guide – Omnichannel payments at the Point Of Sale | Sensepass
- Pay by Bank Tutorial: A Complete Guide for Businesses – Omnichannel payments at the Point Of Sale | Sensepass
- Mastering the Omnichannel Payment Workflow Guide – Omnichannel payments at the Point Of Sale | Sensepass

 New York Office
260 Madison Ave Suite 8018 New York NY 10016

