
Stepwise Payment Settlement Guide for Retailers
June 19, 2026
TL;DR:
- Payment settlement involves a multi-stage process transferring funds from customers to merchants after authorization, requiring proper infrastructure and tools. Retailers must manage each phase, from authorization to reconciliation, to ensure timely funds and resolve potential delays caused by fund holds or disputes. A proactive approach, including enforceable agreements and a control-sensitive workflow, helps optimize cash flow and minimizes settlement challenges.
Payment settlement is defined as the structured, multi-stage process of transferring funds from a customer’s account to a merchant’s account after a transaction is authorized. This stepwise payment settlement guide walks retail professionals through every phase of that process, from authorization to final reconciliation, so you can protect cash flow and reduce friction at checkout. Platforms like Sensepass are built specifically to support this workflow across dozens of payment methods and POS environments. Credit card settlements typically complete within 1–3 business days, while ACH payments usually settle in 1–2 days. Knowing where your money is at every step is not a luxury. It is an operational requirement.
What are the essential prerequisites for payment settlement?
Before your first transaction clears, the right infrastructure must be in place. Missing a single component creates bottlenecks that delay funds and frustrate customers.
The core tools every retailer needs are:
- Payment gateway: Routes transaction data between your POS and the card networks. Sensepass functions as an orchestration layer, connecting your checkout to 50+ card processors.
- Merchant account: Holds funds temporarily before they transfer to your business bank account.
- POS integration: Your point-of-sale system must communicate cleanly with your gateway. Sensepass integrates with NetSuite, SuiteCommerce, Oracle Xstore, Aptos, Shopify POS, BigCommerce, Storis, NCR, Dynamics365, and more.
- Reconciliation records: Invoices, receipts, and transaction logs that match deposits to sales.
- Security and compliance layer: PCI DSS compliance and fraud detection tools prevent holds before they start. Secure payment processing is the foundation of a clean settlement cycle.
The table below compares the key tools and their primary functions in the settlement workflow.
| Tool | Primary function |
|---|---|
| Payment gateway | Encrypts and routes transaction data to the processor |
| Merchant account | Holds authorized funds before bank deposit |
| POS system | Captures transaction data at the point of sale |
| Reconciliation software | Matches bank deposits to individual transactions |
| Fraud detection tools | Flags unusual activity before it triggers a fund hold |
A processor-agnostic platform like Sensepass gives you the flexibility to choose your card processor based on rates and performance rather than lock-in. That choice directly affects how fast funds move through the settlement chain. Review the payment gateway selection tips before committing to any single processor relationship.
What are the step-by-step actions in the payment settlement process?
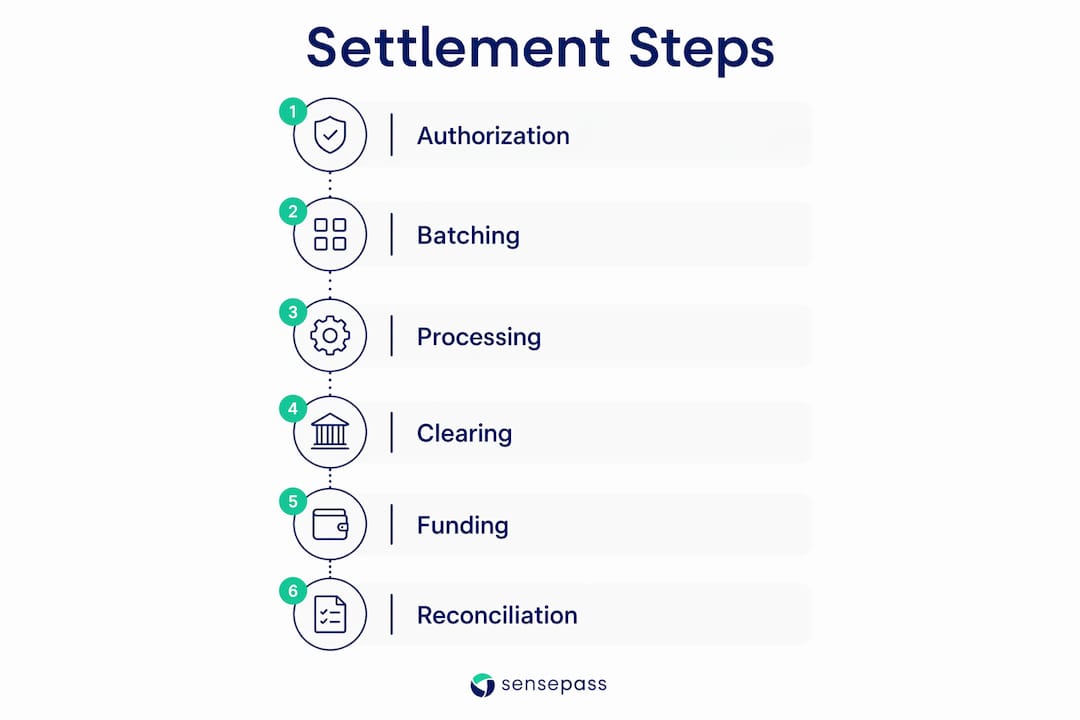
The payment settlement process follows eight distinct phases. Each one must complete before the next begins. Skipping or mishandling any phase delays your funds.
-
Authorization. The customer initiates payment. Your POS sends a request to the payment gateway, which forwards it to the card network and issuing bank. The bank approves or declines in seconds. No money moves yet. Only a hold is placed on the customer’s account.
-
Verification. The gateway checks for fraud signals, CVV matches, and address verification. This is where automated risk models can flag unusual activity and trigger a hold on your end.
-
Capture. You confirm the transaction. For most retail sales, authorization and capture happen simultaneously. For pre-orders or delayed shipments, capture occurs separately when goods are fulfilled.
-
Batching. Authorized transactions accumulate throughout the day. At a set time, usually end of business, your system groups them into a batch and submits them to your processor. Batching transactions at day-end optimizes processing efficiency and supports timely settlement. Submitting a clean batch before your processor’s cutoff time is the single most controllable factor in settlement speed.
-
Clearing. The processor sends the batch to the card networks, which route each transaction to the appropriate issuing bank. The issuing bank debits the customer’s account. This stage typically runs overnight.
-
Settlement. The card network transfers funds to your acquiring bank, minus interchange fees. Credit card settlements complete within 1–3 business days from this point.
-
Funding. Your acquiring bank deposits the net amount into your merchant account or business bank account. ACH payments follow a parallel path and typically settle in 1–2 days.
-
Reconciliation. You match every deposit to its corresponding transaction records. Discrepancies found here are far easier to resolve than ones discovered weeks later.
Pro Tip: Set your batch submission time at least 30 minutes before your processor’s daily cutoff. Late batches roll to the next business day, adding 24 hours to your funding timeline with no benefit.
The retail payment workflow guide from Sensepass maps this entire sequence across omnichannel environments, including in-store POS, self-checkout, and online transactions.
How can businesses troubleshoot common payment settlement challenges?
Settlement delays almost always trace back to one of three causes: fund holds triggered by risk flags, chargebacks initiated by customers, or reconciliation mismatches caused by data errors. Each requires a different response.
Resolving fund holds
Fund holds result from automated risk models flagging unusual activity. The most common triggers are sudden spikes in transaction volume, high average ticket sizes, or a new product category that differs from your processing history. Generic customer support cannot resolve these. You must contact the underwriting or risk department directly and request a written explanation of the specific trigger. Responding with complete proof within 24–48 hours speeds fund release significantly. Acceptable documentation typically includes invoices, delivery confirmations, customer communications, and refund policy records.
Managing chargebacks and disputes
Effective payment dispute resolution involves three actions: categorizing the root cause of each dispute, pausing automated collection attempts while the dispute is open, and assigning internal ownership so one person drives the resolution. Timely categorization reduces Days Sales Outstanding and prevents disputes from compounding. Proactively communicating with both the processor and the disputing customer builds trust and often results in a withdrawn chargeback before it escalates.
Best practices to reduce chargebacks and accelerate fund release:
- Use clear billing descriptors so customers recognize your charge on their statement.
- Send automated order confirmations and delivery notifications to every customer.
- Maintain a 30-day archive of transaction evidence for every sale.
- Monitor your chargeback ratio monthly. Most processors flag merchants above 1%.
- Respond to every retrieval request within the processor’s stated deadline, typically 10 business days.
Pro Tip: Call your processor’s risk department rather than emailing. A direct conversation establishes context faster and signals that you are a cooperative merchant, which matters when a hold decision is being reviewed.
What are the best practices for drafting payment settlement agreements?
A payment settlement agreement is a formal contract that documents the terms under which a debt or disputed amount will be resolved. A valid agreement must include clear payment terms, a defined release scope, enforcement provisions, and proper execution by all parties.
Key elements of an enforceable agreement
The release scope defines exactly which claims are being settled. A narrow release covers only the specific invoice in dispute. A broad release covers all claims between the parties up to the agreement date. Choose the scope deliberately, because courts interpret release language literally.
Enforcement provisions give the agreement teeth. Acceleration clauses, late payment interest, and clear contractual structures make agreements enforceable and discourage default. When the consideration being exchanged is uncertain or nominal, executing the agreement as a deed rather than a standard contract provides stronger legal standing.
The table below compares the core components of a payment settlement agreement and their practical benefits.
| Agreement component | Practical benefit |
|---|---|
| Clear payment terms | Eliminates ambiguity about amounts, dates, and method |
| Defined release scope | Prevents future claims on settled matters |
| Acceleration clause | Makes full balance due immediately upon default |
| Late payment interest | Discourages delayed installments |
| Deed execution | Strengthens enforceability when consideration is uncertain |
Operational tips for managing agreements
Automate installment payments wherever possible. Manual payment collection introduces human error and creates unnecessary friction. Schedule reminder notifications three days before each due date and again on the due date itself. Retain all signed agreements and payment records for a minimum of seven years. This protects you in the event of a future dispute or audit.
Dispute resolution is about preserving long-term business relationships, not just recovering funds. An agreement that leaves both parties feeling treated fairly is more likely to be honored and more likely to lead to continued business.
Key takeaways
A complete payment settlement process requires the right tools, a clear understanding of each phase, and documented agreements that protect both parties when disputes arise.
| Point | Details |
|---|---|
| Settlement has eight phases | Authorization through reconciliation must each complete in sequence for funds to arrive on time. |
| Batching timing controls speed | Submitting your batch before the processor’s daily cutoff is the most controllable factor in funding speed. |
| Fund holds need targeted responses | Contact the risk department directly and provide specific documentation within 24–48 hours to release held funds. |
| Agreements need enforcement hooks | Acceleration clauses and late payment interest make settlement agreements enforceable and reduce default risk. |
| Processor flexibility matters | A processor-agnostic platform gives you the ability to switch processors without rebuilding your entire payment stack. |
Why I think most retailers underestimate the settlement layer
Most retail operators focus intensely on the checkout experience and almost not at all on what happens after the customer taps their card. That is a mistake I have seen cost businesses real money.
The settlement layer is where cash flow actually lives. A two-day delay in funding does not sound significant until you are managing payroll, inventory replenishment, and vendor payments simultaneously. At that point, the difference between a 24-hour and a 72-hour settlement cycle is material.
The other thing I have noticed is that fund holds catch merchants completely off guard. They treat a hold as an error rather than a trigger to be resolved. The processor is not your adversary in that moment. They flagged something unusual and they need you to explain it. Merchants who respond fast, with the right documentation, almost always get their funds released quickly. Merchants who wait or escalate to generic support waste days.
The same logic applies to payment settlement agreements. I have seen businesses use informal email chains to document installment arrangements with customers. When those arrangements fall apart, there is nothing enforceable to stand on. A properly executed agreement with an acceleration clause changes the dynamic entirely.
The retailers who handle settlement well share one trait: they treat the payment workflow as a core business process, not a background function. That means owning every step from batch submission to reconciliation, and having a clear response plan for holds and disputes before they happen.
— Vlad
How Sensepass supports your payment settlement workflow
Sensepass is built to give retailers control at every stage of the settlement process, from the moment a customer initiates payment to the final deposit in your account.

Sensepass connects to NetSuite, SuiteCommerce, Oracle Xstore, Aptos, Shopify POS, BigCommerce, Storis, NCR, Dynamics365, and more, so your POS data flows cleanly into the settlement chain without manual intervention. The platform supports digital wallets including PayPal, Venmo, Apple Pay, Google Pay, Alipay, WeChat, and Amazon Pay. It also covers BNPL options like Klarna, Sezzle, ZIP, Splitit, and Afterpay; financing through WeGetFinancing and Affirm; crypto payments via BitPay and Coinbase; and pay-by-bank solutions including Trustly and LinkMoney. Because Sensepass is processor-agnostic, you choose from 50+ card processors for maximum rate flexibility. Explore the full omnichannel payments platform to see how it fits your settlement needs.
FAQ
What is the standard payment settlement timeline?
Credit card settlements typically complete within 1–3 business days after the batch is submitted. ACH payments usually settle in 1–2 business days.
What causes a payment settlement fund hold?
Automated risk models flag unusual transaction patterns such as volume spikes or high ticket sizes. Resolving a hold requires contacting the processor’s risk department and providing targeted documentation.
What should a payment settlement agreement include?
A valid agreement must include clear payment terms, a defined release scope, and enforcement provisions like acceleration clauses and late payment interest. Executing the agreement as a deed strengthens enforceability when consideration is uncertain.
How does batching affect settlement speed?
Batching groups authorized transactions before submission to the processor. Submitting your batch before the processor’s daily cutoff ensures same-day processing and avoids a 24-hour delay.
How do you resolve a payment dispute efficiently?
Effective dispute resolution requires categorizing the root cause, pausing automated collections, and assigning one internal owner to drive the resolution. Direct communication with the customer often results in a withdrawn chargeback before escalation.
Recommended
- Master Payment Processing Best Practices for Your Business – Omnichannel payments at the Point Of Sale | Sensepass
- Essential Payment Gateway Selection Tips for Retailers – Omnichannel payments at the Point Of Sale | Sensepass
- Your Guide to Flexible Payment Options in Retail – Omnichannel payments at the Point Of Sale | Sensepass
- Retail Payment Workflow Optimization for Seamless Omnichannel Sales – Omnichannel payments at the Point Of Sale | Sensepass

 New York Office
260 Madison Ave Suite 8018 New York NY 10016

