
How to Streamline Your Offline Payment Workflow in 2026
July 21, 2026
Best practices to improve your offline payment workflow
Getting your offline payment workflow right comes down to a short list of deliberate operational choices. The goal is not just to survive connectivity outages but to run a payment process that is accurate, fast, and auditable whether your internet is up or not. Here are the foundational practices that make the biggest difference.
- Set clear transaction limits. Offline payment best practices call for a maximum offline ticket size, signature requirements for higher amounts, and restrictions to chip cards only. These controls protect you from the merchant liability that comes with store-and-forward transactions.
- Automate reconciliation daily. Offline terminals store encrypted transaction data locally and submit it automatically when connectivity returns. Match those stored records against your gateway settlement reports every day, not weekly.
- Support multiple payment methods. Customers expect options. Configuring your POS to accept digital wallets, BNPL, and pay-by-bank methods offline reduces abandoned transactions during outages.
- Use electronic invoicing and recurring billing. Both reduce manual data entry and the errors that come with it. Recurring billing is especially useful for subscription-based or contract customers.
- Train employees on offline procedures. Staff should know which tender types are allowed offline, how to document transactions, and what to tell customers about delayed processing.
- Monitor offline transactions every day. Review approval and decline reports after each sync. Contact customers promptly when a stored transaction is declined post-reconnection.
- Use offline-capable terminals and POS systems. Most systems enforce a 12–24 hour offline operation window before reconnection is required. Choose hardware and software that handle this window gracefully, with encrypted local storage and automatic syncing.
How do you identify and reduce friction in offline payment processing?
Friction in an offline payment process usually hides in the handoffs. A transaction that flows cleanly online can stall at three or four points the moment connectivity drops, and most teams only discover those gaps during an actual outage.
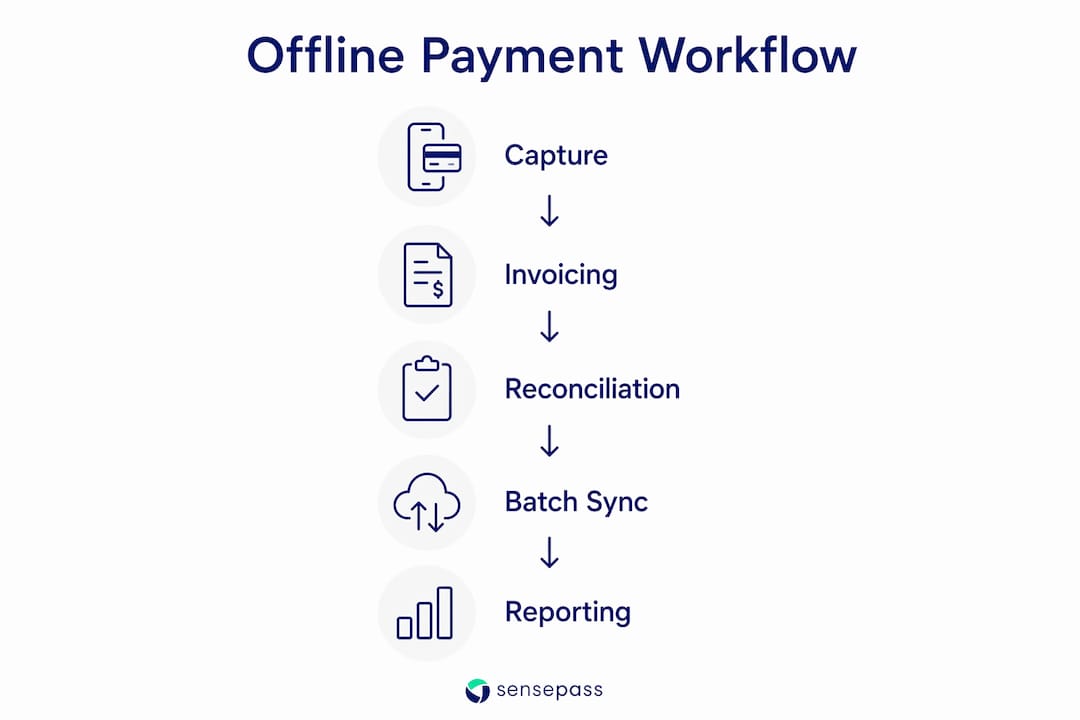
Start by mapping your current process end to end. Walk through a complete offline transaction: card tap, receipt print, cash drawer open, and end-of-day sync. You will find friction faster by doing it than by theorizing about it.
- Technology gaps. Many POS systems restrict offline mode to 12–24 hours with limited tender types. BNPL, gift cards, and manual card entry are often disabled offline. Know exactly what your system supports before an outage forces the question.
- Hardware failures. Cloud-based receipt printers fail without local network connectivity. Testing your printer connection before going live is not optional. USB printers are more reliable offline than Wi-Fi models.
- Delayed authorizations. Store-and-forward means authorization happens after reconnection, not at the point of sale. Customers may leave before you know whether a payment cleared. Setting a maximum offline ticket size limits your exposure here.
- Data conflicts across devices. When multiple terminals operate offline simultaneously, inventory and order data can diverge. Peer-to-peer mesh networking synchronizes orders and inventory locally among offline POS devices, preventing overselling and data conflicts during outages.
- Customer experience gaps. Customers do not always understand why a receipt says “pending settlement.” A small sign at the register and a trained staff response go a long way toward preventing confusion and disputes.
- Sync errors after reconnection. Offline payment queues need clear sync statuses with timestamps, rejection flags, and audit trails to support error detection and financial reconciliation. If your system does not show this clearly, that is a friction point worth fixing before the next outage.
Pro Tip: Run a controlled offline simulation quarterly. Disconnect your internet, complete a full transaction cycle including a card payment, a cash sale, a receipt print, and a refund attempt, then restore connectivity and verify the sync results match your records.
Why automation is the core of a reliable offline payment process
Automating the repetitive parts of offline payment handling, specifically invoicing, recurring billing, and bank reconciliation, removes the manual steps where errors accumulate. The payoff is faster settlement, cleaner books, and fewer customer disputes.
Electronic invoicing speeds up the payment cycle by delivering invoices digitally the moment a transaction is captured, even if the actual authorization is queued for later. Customers receive confirmation faster, which reduces inbound inquiries about payment status.
Recurring billing is particularly valuable for businesses with subscription or retainer-based revenue. When billing runs automatically on a schedule, payment lapses from forgotten invoices drop sharply. The manual follow-up that typically eats staff time disappears.
Automated reconciliation is where the operational gains are most concrete. Hybrid reconciliation workflows combine device-stored records with gateway settlement verification and automated job matching. The system flags mismatches for human review rather than requiring a staff member to compare records line by line.
- Reconcile offline batches the same day they sync, not at month-end.
- Use accounting software that accepts direct feeds from your payment gateway so transaction data flows in without manual export and import.
- Configure your reconciliation tool to flag declined offline transactions automatically, so you can contact affected customers the same day.
- Maintain a clear audit trail: every offline transaction should carry a local timestamp, a device sequence number, and a final authorization result after sync.
- Review the payment processing best practices that apply specifically to offline batch workflows before configuring your reconciliation schedule.
The right accounting software integration turns what used to be a half-day reconciliation task into a background job that surfaces only the exceptions that need your attention.
How payment portals and multiple payment methods improve offline acceptance
Offering only one or two payment options offline is a quiet revenue leak. Customers who cannot pay their preferred way often abandon the transaction entirely, and that loss rarely shows up in your reports as “payment method unavailable.”
Payment portals give customers a self-service channel to view invoices, confirm payment status, and complete transactions when connectivity is restored. For B2B contexts especially, a portal reduces the back-and-forth between your AR team and the customer’s accounts payable department.
Supporting diverse payment methods offline requires deliberate terminal configuration. Not every payment type works in offline mode by default. Here is what to prioritize:
- Digital wallets (Apple Pay, Google Pay, PayPal, Venmo, Amazon Pay, Alipay, WeChat) can be configured for offline acceptance on capable terminals. Contactless transactions are faster at the register and reduce handling errors.
- BNPL options (Klarna, Afterpay, Sezzle, ZIP, Splitit) are typically online-dependent, but queuing the payment intent offline for processing on reconnection is possible with the right orchestration layer.
- Pay-by-bank methods (Trustly, LinkMoney) and crypto payments (BitPay, Coinbase) follow a similar queued model. The transaction is captured offline and submitted when connectivity returns.
- Financing options (WeGetFinancing, Affirm) work best when the terminal can cache the application data and complete authorization post-reconnection.
Security and PCI compliance apply in offline mode just as they do online. Encrypted local storage is the baseline. Offline payment risks include merchant responsibility for declined stored transactions, so configuring per-transaction limits and restricting offline card acceptance to chip cards are non-negotiable controls. For a deeper look at supporting bank-based payment methods in retail, the in-store bank payment solutions page covers the configuration options in detail.
How do you manage accounts receivable and communication for offline payments?
Cash flow reliability in an offline payment environment depends on two things: knowing exactly where every transaction stands, and communicating that status clearly to customers and internal teams. Most AR problems in offline workflows trace back to one of those two gaps.
Track the right metrics. Monitor offline transaction volume daily, flag any payment that has not synced within your system’s reconnection window, and track your decline rate on stored transactions separately from your online decline rate. These numbers tell you whether your offline controls are calibrated correctly.
- Set early payment incentives for customers who pay invoices before the due date. A small discount for prompt payment improves cash flow and reduces the AR backlog that builds during high-outage periods.
- Define payment terms clearly in every invoice and customer agreement. Ambiguity about when a payment is “due” versus when it is “authorized” creates disputes that are expensive to resolve.
- Use automated reminders for outstanding invoices. A reminder sent 3 days before the due date and again on the due date reduces late payments without requiring staff intervention.
- Document every offline payment agreement. Signed receipts, timestamped transaction records, and clear settlement-state language on customer receipts all reduce dispute frequency.
- Train staff to explain offline payment delays confidently. A customer who hears “your payment is securely stored and will process when our connection restores” is far less likely to dispute the charge than one who receives no explanation.
Transparent communication during an outage is also an omnichannel customer experience issue. Customers who understand what is happening stay calm. Those who do not tend to call their bank first and ask questions later.
Pro Tip: Build a one-page offline payment script for your front-line staff. Cover the three most common customer questions: “Was my payment taken?”, “When will it process?”, and “Can I get a receipt now?” Consistent answers prevent disputes before they start.
How Sensepass supports offline payment workflow orchestration
Sensepass operates as a processor-agnostic orchestration layer, which means it sits between your POS system and your payment processors and manages transaction routing, method support, and sync logic across all of them. That architecture is what makes it possible to run a consistent offline payment experience across multiple locations and terminal types without rebuilding your stack.
The platform integrates with major POS and eCommerce platforms including NetSuite, SuiteCommerce, Oracle Xstore, Aptos, Shopify POS, BigCommerce, Storis, NCR, and Dynamics365. That breadth of integration means your existing infrastructure does not need to be replaced. Sensepass connects to what you already have and extends its offline capabilities.
On the payment method side, Sensepass supports:
- Digital Wallets: PayPal, Venmo, WeChat, Apple Pay, Google Pay, Alipay, Amazon Pay
- BNPL: Klarna, Sezzle, ZIP, Splitit, Afterpay
- Financing: WeGetFinancing, Affirm
- Crypto: BitPay, Coinbase
- Pay by Bank: Trustly, LinkMoney
Sensepass is also processor-agnostic, giving merchants access to 50+ card processors. That flexibility lets you choose the processor with the best rates and offline mode terms for your transaction profile, rather than being locked into a single provider’s offline limitations.
Treating offline mode as a deliberate operational configuration, rather than a fallback, is what separates payment operations that maintain customer trust during outages from those that lose sales and generate disputes. The Federal Reserve’s analysis of offline payment resilience makes clear that hybrid systems combining local encrypted storage with automatic batch syncing represent the current best practice for reliable offline payment acceptance.
For retailers running omnichannel operations, Sensepass handles the encrypted local storage, batch syncing, and unified customer experience that make offline transactions indistinguishable from online ones from the customer’s perspective. The retail payment workflow guide walks through how that orchestration works step by step for in-store and mobile POS environments.
Pro Tip: When evaluating any offline payment orchestration platform, ask specifically about three things: the maximum offline transaction window, which tender types are supported offline, and who bears liability for declined stored transactions. The answers will tell you whether the platform is built for offline-first operations or treating offline as an afterthought.
Sensepass helps you build a resilient offline payment operation
If you are running a retail business with multiple locations, mixed payment methods, and real connectivity risk, the omnichannel payments guide for retailers is the right starting point for understanding how Sensepass fits into your existing stack.

Sensepass connects your POS systems, payment methods, and processors into a single orchestration layer that keeps transactions moving whether you are online or not. From digital wallets to BNPL to crypto, every method you need is supported, and every processor you prefer is available.
Key Takeaways
Improving your offline payment workflow requires deliberate configuration, daily reconciliation, and an orchestration layer that supports every payment method your customers expect.
| Point | Details |
|---|---|
| Set transaction limits | Cap offline ticket sizes and restrict acceptance to chip cards to limit merchant liability on declined stored transactions. |
| Reconcile daily | Match device-stored records against gateway settlement reports every day; automated reconciliation flags declines for same-day follow-up. |
| Test hardware offline | Cloud-based receipt printers fail without local network connectivity; USB printers and pre-tested cash drawers prevent compliance gaps. |
| Support multiple methods | Digital wallets, BNPL, crypto, and pay-by-bank methods can be queued offline and processed on reconnection with the right orchestration layer. |
| Use an orchestration platform | Sensepass integrates with 50+ card processors and major POS platforms including NetSuite, Oracle Xstore, and Shopify POS for processor-agnostic offline operations. |
Recommended
- Master Payment Processing Best Practices for Your Business – Omnichannel payments at the Point Of Sale | Sensepass
- How to improve the in-store payment experience: 5 steps – Omnichannel payments at the Point Of Sale | Sensepass
- Streamline checkout for retail success in 2026 – Omnichannel payments at the Point Of Sale | Sensepass
- Optimize retail checkout for higher conversions: 70% loss – Omnichannel payments at the Point Of Sale | Sensepass

 New York Office
260 Madison Ave Suite 8018 New York NY 10016

