
How to streamline payment systems for omnichannel retail
March 23, 2026
Many retailers struggle with fragmented payment systems that slow transactions, inflate costs, and limit customer choice. Disconnected gateways create silos between online stores, physical locations, and mobile channels, leading to declined payments and abandoned carts. Streamlining your payment infrastructure with intelligent routing, processor-agnostic platforms, and unified omnichannel integration transforms these pain points into competitive advantages. This guide walks you through assessing your current setup, implementing smart payment flows, unifying channels, and continuously optimizing performance to boost approval rates and reduce friction.
Table of Contents
- Key takeaways
- Assess your current payment systems and set goals
- Implement intelligent payment routing and optimize transaction flows
- Unify omnichannel payment systems to handle complex scenarios
- Test, monitor, and continuously optimize your payment system
- How Sensepass can help you streamline payments
- Frequently asked questions
Key Takeaways
| Point | Details |
|---|---|
| Intelligent routing | Real time machine learning based routing selects the best acquirer for each transaction to maximize approval rates and reduce costs. |
| Processor agnostic platforms | Choose flexible platforms that integrate with multiple gateways and major POS systems. |
| Omnichannel integration | Unify online, in store, and mobile payments to reduce silos and improve the customer experience. |
| Sandbox testing | Create sandbox environments to safely test changes before going live and compare performance against baseline metrics. |
| Ongoing optimization | Continuously monitor approval rates, speeds, and costs and run tests to maintain smooth payment flows. |
Assess your current payment systems and set goals
Before making changes, you need a clear picture of your existing payment infrastructure and specific objectives. Start by conducting a thorough audit of all payment gateways, processors, and POS integration points across your business. Map every touchpoint where customers pay, from ecommerce checkout pages to in-store terminals and mobile apps.
Identify specific pain points causing friction or revenue loss. Common issues include slow transaction approvals that frustrate customers, high processing fees eating into margins, limited payment options that exclude potential buyers, and channel silos preventing seamless cross-platform experiences. Document decline rates, average transaction times, and total processing costs to establish baseline metrics.
Define clear, measurable goals aligned with business priorities. You might aim to reduce transaction times by 30%, cut processing costs by 15%, or support ten additional payment methods within six months. Prioritize platforms that are processor-agnostic and support multiple gateways and POS systems like Shopify POS, NetSuite, Oracle Xstore, or NCR for maximum flexibility.
Set up sandbox environments for safe testing before deploying changes to live systems. Sandbox testing lets you validate integrations, routing rules, and payment flows without risking customer transactions or revenue. Document current workflows, integration points, and system dependencies thoroughly so you can compare performance after implementation and quickly troubleshoot issues.
Key preparation steps include:
- Audit all payment touchpoints across online, in-store, and mobile channels
- Measure baseline metrics for approval rates, transaction speed, and processing costs
- Define specific improvement goals tied to revenue and customer experience
- Research payment gateway selection criteria for retail flexibility
- Create sandbox environments to test changes safely before going live
- Map system dependencies and integration points for smooth transitions
Implement intelligent payment routing and optimize transaction flows
Intelligent payment routing uses machine learning and predictive algorithms to select the best acquirer for each transaction in real time. Instead of sending all payments through a single processor, smart routing directs transactions via optimal acquirers based on card type, customer location, and historical approval data. This approach significantly increases approval rates while reducing processing costs.
Consider multiple parameters when building routing logic. Card type matters because certain processors have better relationships with specific card networks. Geographic location affects approval rates since local acquirers often perform better for domestic transactions. Transaction history reveals patterns about which processors approve payments from repeat customers most reliably. Time of day and purchase amount also influence optimal routing decisions.
Employ smart retry logic to rescue declined transactions automatically. When a payment fails, the system immediately attempts the transaction through alternative routes without requiring customer action. This happens in milliseconds, so customers rarely notice the retry. Smart retries can recover 10 to 20% of initially declined transactions, directly reducing cart abandonment and increasing revenue.
Pro Tip: Monitor routing performance weekly during the first three months after implementation, then monthly thereafter. Payment trends shift as fraud patterns evolve, new processors enter the market, and customer preferences change. Regular reviews let you adjust algorithms to maintain optimal approval rates.
Include fallback mechanisms to handle processor downtime or temporary declines gracefully. If your primary acquirer experiences technical issues, the system should automatically route transactions to backup processors without interrupting customer checkout flows. Build redundancy into your payment infrastructure to ensure 99.9% uptime even when individual processors face problems.
Critical routing optimization tactics:
- Deploy machine learning models that analyze card type, location, and transaction history
- Configure smart retry logic to attempt declined payments via alternative acquirers instantly
- Set up fallback processors to maintain uptime during primary acquirer outages
- Test routing rules in sandbox environments before applying to live transactions
- Monitor approval rate improvements and adjust algorithms based on performance data
Improved routing can boost approval rates by 5 to 15% while cutting processing costs through intelligent acquirer selection. Every percentage point improvement in approval rates translates directly to revenue gains, making intelligent routing one of the highest-ROI payment optimizations available.
Unify omnichannel payment systems to handle complex scenarios
Adopting an omnichannel payment platform unifies transactions across physical stores, ecommerce sites, and mobile apps into a single coherent system. Instead of managing separate payment stacks for each channel, you gain centralized control over all payment flows, customer data, and reporting. This unification solves edge cases that frustrate customers and drain operational resources.
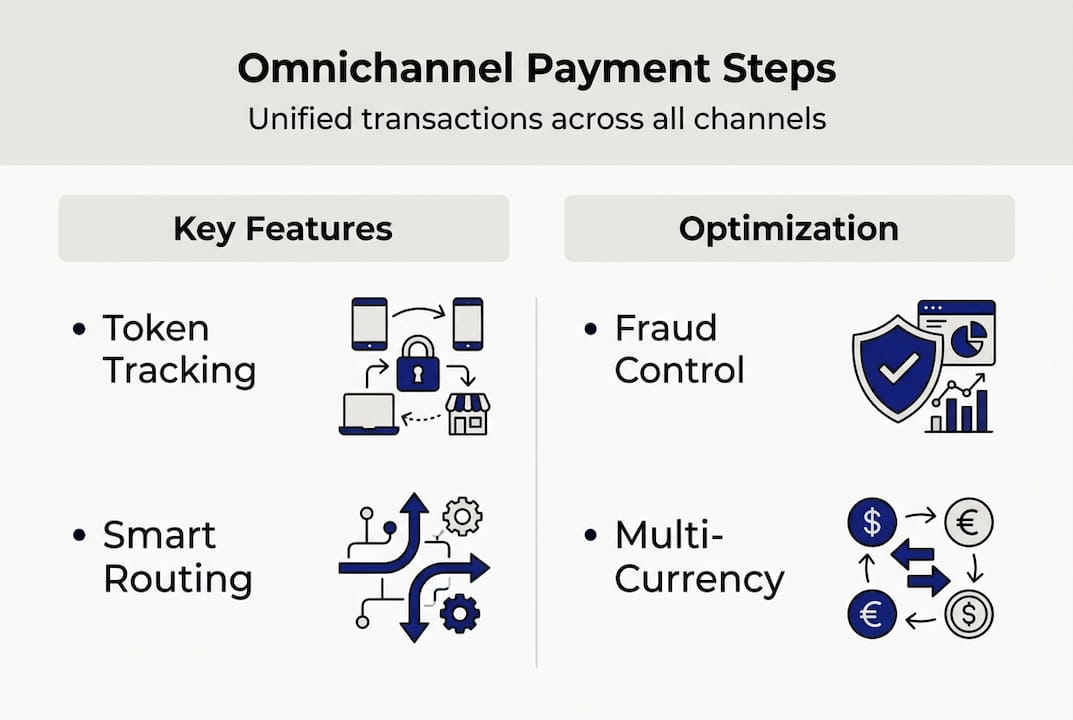
Enable universal payment tokens to track and reconcile payments across channels seamlessly. When a customer saves a payment method in your mobile app, those tokenized credentials should work equally well for online purchases or in-store transactions. Universal tokens eliminate the need for customers to re-enter payment details across channels while maintaining PCI compliance and security standards.
Leverage AI-powered fraud detection and prediction to minimize losses without blocking legitimate transactions. Modern fraud systems analyze hundreds of behavioral signals in real time, identifying suspicious patterns while allowing good customers to check out smoothly. AI handles cross-channel returns, refunds, and multi-currency processing automatically, reducing manual intervention and operational costs.
Support multi-currency processing and refunds seamlessly between channels. A customer who purchases online in euros should be able to return the item in-store and receive a refund in their original currency without complications. Omnichannel systems handle currency conversion, exchange rate fluctuations, and cross-border regulations automatically.
Plan system scalability to accommodate new stores, traffic spikes, and seasonal trends without performance degradation. Your payment infrastructure should handle Black Friday traffic volumes as smoothly as a typical Tuesday in February. Cloud-based omnichannel platforms scale elastically, adding processing capacity during peak periods and reducing costs during slower times.
| Multichannel Silos | Omnichannel Unity |
|---|---|
| Separate payment systems per channel | Single unified payment platform |
| Customer re-enters payment info across channels | Universal tokens work everywhere |
| Complex cross-channel returns and refunds | Seamless returns regardless of purchase origin |
| Fragmented customer data and insights | Centralized analytics and reporting |
| Manual reconciliation between systems | Automated reconciliation and reporting |
| Limited fraud detection per channel | AI-powered fraud prevention across all touchpoints |
Implementation priorities for omnichannel unification:
- Select platforms supporting NetSuite, SuiteCommerce, Oracle Xstore, Aptos, Shopify POS, BigCommerce, Storis, NCR, and Dynamics365 integrations
- Deploy universal payment tokenization to enable saved credentials across all channels
- Integrate AI fraud detection that learns from transaction patterns across online and offline sales
- Configure multi-currency support for international customers and cross-border transactions
- Build scalable infrastructure that handles traffic spikes without degrading performance
Understanding what omnichannel payment truly means helps you evaluate platform capabilities and avoid solutions that simply connect channels without genuine unification. True omnichannel platforms share customer data, payment credentials, and transaction history seamlessly across every touchpoint, creating consistent experiences that build loyalty and increase lifetime value. Following payment gateway best practices ensures your unified system maintains security, compliance, and performance standards as you scale.
Test, monitor, and continuously optimize your payment system
Testing each integration, routing rule, and payment flow in a sandbox environment before going live prevents costly mistakes and customer-facing errors. Sandbox testing simulates real transactions without processing actual payments, letting you validate configurations safely. Test edge cases like partial refunds, declined transactions, and multi-currency conversions to ensure your system handles unusual scenarios gracefully.
Monitor key performance indicators continuously to verify your streamlined payment system delivers expected benefits. Track approval rates to measure routing effectiveness, transaction speed to ensure fast checkout experiences, cart abandonment rates to identify friction points, and cost per transaction to validate fee reductions. Audit systems and monitor performance using these metrics to ensure smooth payment flows and ongoing cost savings.
Set alerts for spikes in declines or fraud attempts so you can react promptly to emerging issues. A sudden increase in declined transactions might indicate processor problems, routing misconfigurations, or fraud attacks. Automated alerts let you investigate and resolve issues before they significantly impact revenue or customer satisfaction.
Collect customer feedback on payment experiences to identify friction points that metrics alone might miss. Direct feedback reveals when customers find checkout confusing, payment options insufficient, or transaction times frustrating. Combine quantitative metrics with qualitative insights for a complete picture of payment system performance.
Continuously review fee structures and negotiate with providers based on transaction volume and performance data. As your business grows and payment volumes increase, you gain leverage to negotiate better rates. Regular reviews ensure you are not overpaying for processing services or missing opportunities to reduce costs through provider optimization.
Step-by-step testing, monitoring, and optimization process:
- Configure new integrations or routing rules in sandbox environments first
- Run comprehensive test scenarios covering typical transactions and edge cases
- Deploy changes to production during low-traffic periods to minimize risk
- Monitor approval rates, transaction speeds, and error rates for 48 hours post-deployment
- Collect customer feedback through surveys and support ticket analysis
- Review weekly performance reports comparing metrics to baseline measurements
- Adjust routing algorithms, processor selection, and configurations based on data
- Negotiate fee reductions with processors using volume and performance metrics
- Document changes and results to build institutional knowledge over time
- Repeat the cycle monthly to maintain optimal payment system performance
Pro Tip: Automate reporting and use real-time dashboards for instant insights that speed decision-making. Manual report generation wastes time and delays responses to emerging issues. Modern payment platforms offer customizable dashboards showing approval rates, processing costs, and fraud metrics updated every few minutes, letting you spot trends and react quickly.
Successful payment gateway selection for retail requires ongoing optimization, not just initial implementation. Payment landscapes evolve constantly with new fraud tactics, changing customer preferences, and emerging payment methods. Systems optimized today need adjustments tomorrow to maintain peak performance and competitive advantages.
How Sensepass can help you streamline payments
If you are ready to move beyond fragmented payment systems toward unified, intelligent processing, Sensepass offers solutions designed specifically for omnichannel retail success. As a processor-agnostic orchestration layer, Sensepass integrates seamlessly with major platforms including NetSuite, SuiteCommerce, Oracle Xstore, Aptos, Shopify POS, BigCommerce, Storis, NCR, and Dynamics365, giving you flexibility to work with your existing infrastructure.

Sensepass supports diverse payment methods your customers prefer, from digital wallets like PayPal, Venmo, Apple Pay, Google Pay, and Alipay to BNPL options including Klarna, Sezzle, Afterpay, and Splitit. The platform also handles financing through WeGetFinancing and Affirm, crypto payments via BitPay and Coinbase, and pay by bank solutions like Trustly and LinkMoney. With access to 50+ card processors, you choose the best combination for your business needs.
Intelligent routing maximizes approval rates while expert support ensures smooth implementation and ongoing optimization. Explore how omnichannel payments transform retail experiences, learn what omnichannel payment capabilities matter most, or review payment gateway selection tips to make informed platform decisions.
Frequently asked questions
How can I reduce payment declines in my retail system?
Use intelligent routing based on card type, customer location, and transaction history to direct payments through acquirers most likely to approve them. Employ smart retries to route declined transactions through alternative acquirers automatically within milliseconds. Predictive routing and machine learning models cut declines and boost conversions by selecting optimal processors for each unique transaction. Regular monitoring and algorithm adjustments maintain high approval rates as payment patterns evolve.
What are the key features to look for in a payment platform?
Prioritize processor-agnostic architecture supporting multiple gateways and POS systems so you are not locked into single-vendor relationships. Ensure omnichannel integration capabilities that unify online, in-store, and mobile transactions seamlessly. Look for support for diverse payment methods including digital wallets, BNPL, crypto, and pay by bank options. Security features like AI-driven fraud detection, PCI compliance, and universal tokenization protect your business and customers while maintaining smooth checkout experiences.
How do I handle cross-channel returns and refunds smoothly?
Use universal payment tokens to track payments across sales channels, enabling seamless refunds regardless of where customers originally purchased items. Ensure your omnichannel system supports automatic refund processing to original payment methods across channels without manual intervention. Configure multi-currency handling so international customers receive refunds in their original currency. Centralized transaction records and reporting make reconciliation straightforward even when purchases and returns happen through different channels.
How often should I monitor and optimize payment performance?
Monitor daily or weekly key metrics like approval rates, transaction speeds, decline reasons, and fraud alerts during the first three months after implementation. Once systems stabilize, shift to weekly detailed reviews with monthly deep dives into trends and optimization opportunities. Regularly review processing fees and fraud reports quarterly to optimize routing rules and renegotiate provider contracts. Set up automated alerts for anomalies so you can respond immediately to spikes in declines or fraud attempts without waiting for scheduled reviews.
Recommended
- Payment Gateway Selection Tips for Retail Success – Omnichannel payments at the Point Of Sale | Sensepass
- Mastering the Omnichannel Payment Workflow Guide – Omnichannel payments at the Point Of Sale | Sensepass
- Payment Gateway Selection Tips for Retail Success – Omnichannel payments at the Point Of Sale | Sensepass
- Master Payment Processing Best Practices for Your Business – Omnichannel payments at the Point Of Sale | Sensepass

 New York Office
260 Madison Ave Suite 8018 New York NY 10016

