
Stripe Payment Gateway Pricing for Retailers
December 26, 2025
Over 60 percent of American retailers now accept at least one form of digital wallet or BNPL as payment. Managing payment processing costs across online and in-store channels has become a top priority for retail operations managers. With new options like Stripe and SensePass offering flexible pricing and integration, understanding the details of each model helps teams avoid hidden fees and take control of their bottom line.
Table of Contents
- What Stripe Payment Gateway Pricing Means
- Types of Stripe Fees and Rate Structures
- Practical Pricing: Case Studies for Retailers
- Hidden Costs and Common Pricing Surprises
- SensePass Integration: Maximizing Cost Efficiency
Key Takeaways
| Point | Details |
|---|---|
| Flexible Pricing Model | Stripe utilizes a pay-as-you-go structure, charging based on transaction volume and specific payment services used. |
| Transaction Fee Variability | Fees differ by payment method, with standard online fees at 2.9% + $0.30 per transaction for credit cards and varied rates for in-person payments. |
| Potential Hidden Costs | Retailers should monitor additional charges such as chargeback fees and currency conversion costs that can impact overall expenses. |
| Integration Advantages | Utilizing SensePass with Stripe can offer enhanced payment processor flexibility and cost optimization through a broader selection of payment options. |
What Stripe Payment Gateway Pricing Means
Stripe Payment Gateway Pricing represents a flexible transaction-based pricing model designed specifically for businesses processing digital payments. According to industry research, Stripe utilizes a pay-as-you-go structure where businesses are charged based on transaction volume and the specific payment services they utilize.
The core of Stripe’s pricing strategy revolves around transaction fees, which vary depending on several critical factors. For online transactions, Stripe typically charges 2.9% plus 30 cents per transaction for standard credit card payments. In-person transactions processed through physical point-of-sale systems often carry slightly different rates, reflecting the reduced fraud risk associated with chip and PIN or contactless payments.
Businesses can expect additional nuances in Stripe’s pricing model. Different payment methods like international credit cards, American Express transactions, or specialized payment types might incur alternative fee structures. Some advanced features such as recurring billing, subscription management, and custom checkout experiences could also introduce supplementary charges beyond standard transaction rates.
Pro tip: Review your monthly transaction volume and payment mix carefully to accurately predict your total processing costs with Stripe and identify potential optimization strategies.
Types of Stripe Fees and Rate Structures
Payment processing fees represent a complex landscape for retailers, and Stripe offers multiple fee structures to accommodate different business models. According to Federal Reserve guidelines, payment processors like Stripe implement varied fee models that reflect network interchange rates, regulatory requirements, and transaction characteristics.
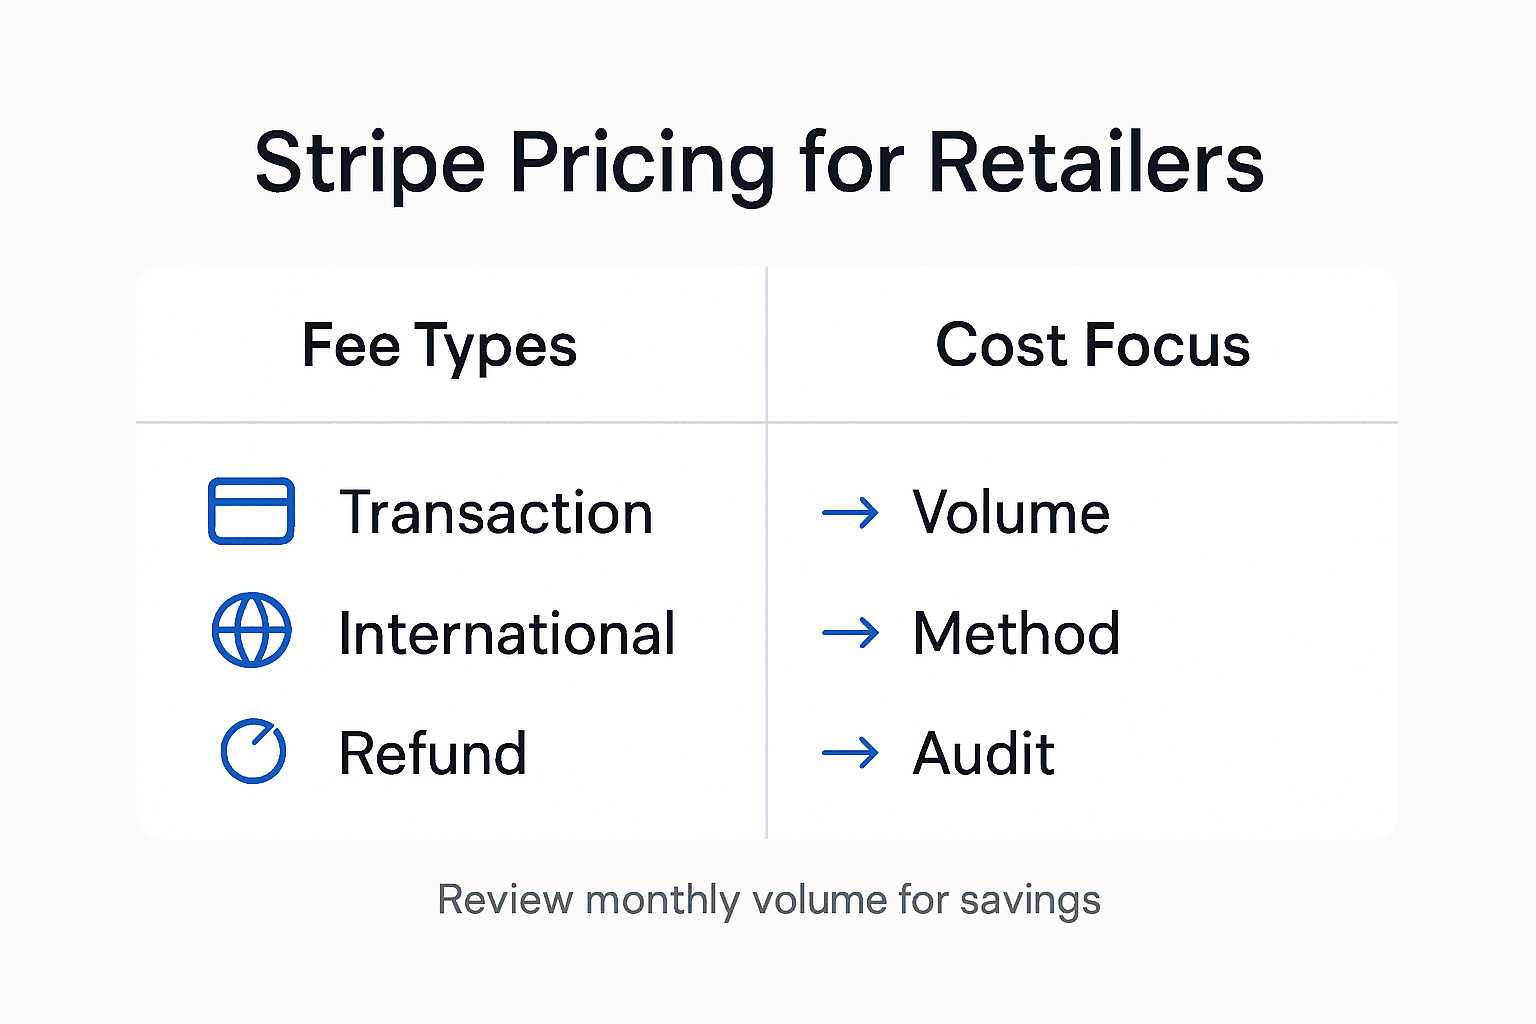
Stripe’s primary fee structure includes standard transaction fees that differ based on payment method and transaction environment. Online transactions typically incur a rate of 2.9% plus 30 cents per transaction, while in-person payments processed through physical point-of-sale systems might have slightly reduced rates. Research indicates that specialty transactions such as international payments, currency conversions, or marketplace sales can trigger additional surcharges.
The fee categories for Stripe generally break down into several key components:
- Standard Online Transactions: 2.9% + $0.30 per transaction
- In-Person Card Payments: Potentially lower percentage rates
- International Transactions: Higher percentage fees
- Specialized Services: Additional charges for recurring billing, dispute management, and custom checkout experiences
Pro tip: Carefully analyze your specific transaction mix and volume to predict potential processing costs, as even small percentage differences can significantly impact your overall financial bottom line.
Practical Pricing: Case Studies for Retailers
Retail payment processing presents unique challenges for businesses of all sizes, and Stripe’s pricing model offers diverse solutions across different operational contexts. Harvard Business School research reveals that retailers range from small startups to established enterprises, each requiring nuanced payment processing strategies that balance cost, convenience, and operational efficiency.
For small online retailers, Stripe’s per-transaction model provides flexibility and predictability. A boutique clothing store with $50,000 annual revenue might pay approximately $1,450 in processing fees, representing a manageable expense compared to traditional merchant account setups. Stanford’s case studies demonstrate that businesses with variable sales volumes benefit significantly from this approach, as they only incur charges when transactions occur.
Larger retailers face more complex considerations. A mid-sized omnichannel retailer processing $2 million annually would experience different cost dynamics:
- Online Sales: Approximately $58,000 in processing fees
- In-Store Transactions: Potentially reduced percentage rates
- International Sales: Higher transaction cost percentages
- Subscription Services: Additional specialized fee structures
Pro tip: Conduct a quarterly analysis of your transaction types and volumes to identify potential cost-saving opportunities within Stripe’s flexible pricing framework.
Below is a summary of how Stripe’s main pricing categories impact different business types:
| Business Type | Most Relevant Fee Category | Cost Management Focus |
|---|---|---|
| Small Online Shop | Standard online transaction fees | Minimize per-transaction costs |
| Omnichannel Retailer | Mix of online, in-store, and intl. fees | Optimize payment method selection |
| International E-commerce | International and currency conversion | Monitor cross-border surcharges |
| Subscription Service | Specialized recurring billing fees | Track add-on service expenses |
Hidden Costs and Common Pricing Surprises
Payment processing fees often extend far beyond the standard transaction rates retailers initially expect. Business research reveals that multiple unexpected charges can significantly impact a retailer’s bottom line, including fees for chargebacks, cross-border transactions, and specialized service features that are not immediately apparent in standard pricing structures.
Stripe’s pricing model includes several potential additional expenses that can catch retailers off guard. These might encompass fees for account maintenance, currency conversion, dispute resolution, and advanced integration services. International retailers face even more complex cost considerations, with potential surcharges for transactions originating from different geographic regions or requiring specialized processing protocols.
Key hidden cost categories for retailers to monitor include:
- Chargeback Fees: Typically $15-$25 per disputed transaction
- Currency Conversion Charges: Additional percentage fees for international sales
- Account Update Fees: Costs associated with maintaining payment method information
- Advanced Integration Expenses: Charges for custom API development or specialized checkout experiences
Federal Trade Commission guidelines emphasize the importance of carefully reviewing complete processing agreements to understand the full scope of potential expenses.
Pro tip: Request a comprehensive fee breakdown from Stripe and conduct a quarterly audit of your transaction costs to identify and mitigate unexpected charges.
SensePass Integration: Maximizing Cost Efficiency
Payment system integration represents a critical strategic decision for retailers seeking to optimize operational expenses and transactional performance. MIT systems engineering research demonstrates that deliberate interface management can significantly reduce duplicated efforts and minimize expensive processing errors.
SensePass offers retailers a sophisticated integration layer that connects seamlessly with Stripe, enabling businesses to leverage advanced cost-control mechanisms. By providing a processor-agnostic platform, SensePass allows merchants to select from 50+ card processors, creating unprecedented flexibility in managing transaction expenses. This approach enables businesses to dynamically adjust their payment processing strategy based on real-time performance and cost considerations.
Key cost efficiency advantages of SensePass integration include:
- Processor Flexibility: Access to 50+ card processors
- Omnichannel Support: Unified payment experiences across online and in-store channels
- Advanced Payment Methods: Support for digital wallets, BNPL, and crypto payments
- Integrated Platforms: Seamless connections with NetSuite, Shopify POS, and other major systems
Cost-effectiveness analysis frameworks suggest that integrated solutions like SensePass can provide measurable operational advantages by reducing transaction complexity and administrative overhead.
Pro tip: Conduct a comprehensive audit of your current payment processing costs and compare potential savings through SensePass integration before making a final decision.
Compare the benefits of integrating SensePass with Stripe to using Stripe alone:
| Feature | Stripe Only | Stripe + SensePass |
|---|---|---|
| Payment Flexibility | Limited to Stripe terms | Choose among 50+ processors |
| Integration Scope | Primarily Stripe tools | Unified with other platforms |
| Cost Optimization Tools | Standard Stripe controls | Dynamic, processor-based savings |
| Omnichannel Support | Separate channels | Fully unified experiences |
Optimize Your Retail Payment Strategy with SensePass
Retailers navigating Stripe payment gateway pricing often face challenges like managing multiple fee structures, handling diverse payment methods, and controlling rising processing costs. SensePass directly addresses these pain points by offering a processor-agnostic payment orchestration platform that empowers you to choose from 50+ card processors and manage payments seamlessly across online and offline channels. Supporting integration with major platforms like NetSuite, Shopify POS, Oracle Xstore, Aptos, and Dynamics365, SensePass enables streamlined operations and enhanced payment flexibility.
Experience comprehensive support for a wide range of payment methods including digital wallets such as PayPal, Apple Pay, Google Pay, and Venmo; BNPL options like Klarna and Afterpay; crypto payments via BitPay and Coinbase; plus financing and pay by bank alternatives. This broad payment ecosystem not only improves customer satisfaction but also helps reduce unexpected fees and optimize transaction costs beyond standard Stripe fees.

Take control of your payment processing costs today by integrating SensePass with your retail systems. Visit SensePass now to explore how our versatile omnichannel solutions can help you increase sales conversion, reduce operational complexity, and future-proof your payment infrastructure.
Frequently Asked Questions
What is the standard transaction fee for Stripe payment processing?
The standard fee for online transactions with Stripe is 2.9% plus 30 cents per transaction. In-person payments may have slightly reduced rates.
Are there additional fees for international transactions with Stripe?
Yes, international transactions typically incur higher percentage fees compared to standard domestic transactions. It’s important to review pricing structures for specific cases.
How can I optimize my processing costs with Stripe?
To optimize processing costs, analyze your monthly transaction volume and payment methods. This helps in understanding potential cost-saving strategies and allows you to predict your total fees more accurately.
What are some common hidden costs associated with Stripe’s pricing model?
Common hidden costs may include chargeback fees, currency conversion charges for international sales, and advanced integration expenses. It’s advisable to conduct a quarterly audit of your transaction costs to identify these potential charges.
Recommended
- Role of Payment Gateways: Complete Retail Guide – Omnichannel payments at the Point Of Sale | Sensepass
- Credit Card Payment Gateway: Complete Retail Guide – Omnichannel payments at the Point Of Sale | Sensepass
- Payment Gateway Best Practices: Complete Guide – Omnichannel payments at the Point Of Sale | Sensepass
- Understanding PayPal Payment Gateway Pricing – Omnichannel payments at the Point Of Sale | Sensepass

 New York Office
260 Madison Ave Suite 8018 New York NY 10016

