
The Card Processor Selection Process for Retailers
May 28, 2026
TL;DR:
- Choosing the right card processor requires defining your business profile, evaluating vendors systematically, and testing with real transactions to avoid costly mistakes.
- Regularly reviewing your processor ensures it scales with your evolving sales channels, volume, and payment preferences, saving future costs and headaches.
The card processor selection process is one of the most consequential decisions a retail business makes, yet most companies treat it like a commodity purchase. Pick the wrong provider and you pay for it twice: once in processing fees you didn’t see coming, and again in integration headaches that slow down your checkout. This guide walks you through a practical, step-by-step card processor selection framework so you can evaluate providers with clear criteria, understand what your costs will actually be, and build a payment foundation that scales with your business.
Table of Contents
- Key takeaways
- The card processor selection process starts with knowing your business
- How to evaluate and compare processors systematically
- Understanding pricing models and total cost of ownership
- Integration quality, API support, and fraud tools
- Implementing your decision and verifying performance
- My perspective on what actually matters here
- How Sensepass simplifies your processor decision
- FAQ
Key takeaways
| Point | Details |
|---|---|
| Start with your business profile | Define your volume, channels, and tech stack before comparing any providers. |
| Use a scoring matrix | Rate vendors on weighted criteria to remove bias from the evaluation process. |
| Decode total cost of ownership | Transaction fees are just the start; chargebacks, PCI fees, and cross-border costs add up fast. |
| Test before you commit | A one-week proof-of-concept reveals integration gaps no sales deck will show you. |
| Treat selection as ongoing | Your first processor choice should be reviewed as your business model evolves. |
The card processor selection process starts with knowing your business
Before you open a single vendor comparison page, you need a clear picture of your own operation. Operators must define their business model and operating environment before comparing brands to avoid costly misalignment. That advice sounds obvious, but most businesses skip it.
Start with these questions:
- Monthly processing volume and average ticket size. These two numbers drive your pricing model decision more than anything else. Businesses below $5,000 per month in volume typically benefit from flat-rate pricing, while those above that threshold often save money through interchange-plus models.
- Sales channels. Do you sell in-store, online, over the phone, through a mobile app, or all of the above? Each channel has different hardware, API, and certification requirements.
- Customer payment preferences. Today’s shoppers expect to pay with digital wallets, buy now pay later options, and bank transfers, not just cards. Build a list of the payment methods your customers actually use.
- Your existing tech stack. Note every POS system, ecommerce platform, and accounting tool that a processor will need to work with. Compatibility gaps discovered late in the process are expensive.
- Security and compliance requirements. Any processor you consider must support PCI DSS compliance, fraud detection tools such as 3D Secure, AVS, and CVV verification, plus tokenization for stored card data.
- Growth plans. If you expect to expand internationally or launch new sales channels within 18 months, your processor needs to support that scope from day one.
Pro Tip: Build a one-page business profile document covering all the points above before your first vendor call. You’ll get far better answers to your questions and save hours of back-and-forth.
How to evaluate and compare processors systematically
Gut feeling and sales calls are not a selection process. A structured evaluation using weighted criteria and a real-world test is how you find the right fit.
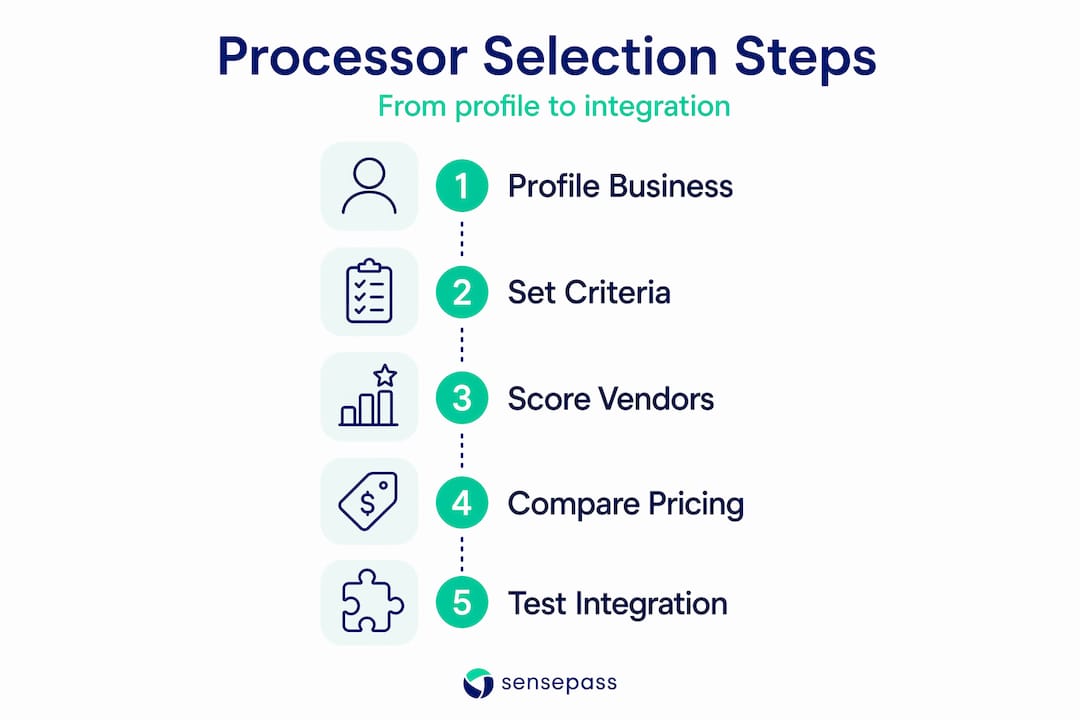
Here is a reliable step-by-step card processor selection workflow:
-
Define your evaluation criteria and weights. Assign a weight out of 100 to five core dimensions: pricing transparency, reliability and uptime history, developer experience and API quality, security tools, and support availability. Your weights should reflect your business priorities. A high-volume retailer might weight pricing at 35%, while a developer-led startup might weight API quality at 30%.
-
Score each candidate provider. Use a 1 to 5 scale for each criterion. Multiply the score by the weight. Sum the totals. This scoring matrix removes the influence of polished marketing from the decision.
-
Classify your provider candidates. Class A providers like those offering self-service onboarding and published rates are best for fast market entry with simple needs. Class B and C providers are built for complex omnichannel or enterprise environments where routing logic, custom integrations, and high transaction volumes come into play.
-
Run a one-week proof-of-concept. A time-boxed PoC is the single most reliable way to verify what a vendor actually delivers. Test transaction latency, error handling, sandbox environment quality, and the speed of support responses. Real data from this test will tell you more than any reference call.
-
Review contract terms carefully. Look at minimum monthly fees, early termination clauses, and any volume commitments. Migration costs and contractual lock-ins must factor into your economic analysis, not just the headline processing rate.
Here is a simplified scoring matrix example for three providers:
| Criterion | Weight | Provider A | Provider B | Provider C |
|---|---|---|---|---|
| Pricing transparency | 30% | 4 (1.2) | 3 (0.9) | 5 (1.5) |
| Reliability and uptime | 25% | 5 (1.25) | 4 (1.0) | 4 (1.0) |
| Developer experience | 20% | 3 (0.6) | 5 (1.0) | 3 (0.6) |
| Security tools | 15% | 5 (0.75) | 4 (0.6) | 4 (0.6) |
| Support availability | 10% | 4 (0.4) | 3 (0.3) | 4 (0.4) |
| Total score | 4.20 | 3.80 | 4.10 |
Pro Tip: Weight your criteria before scoring, not after. Adjusting weights to make a preferred vendor win is a common bias that leads to bad decisions.
Understanding pricing models and total cost of ownership
Pricing is where most businesses get surprised. The advertised rate rarely tells the full story.
The three primary pricing models in card processing work like this. Flat-rate pricing charges a fixed percentage on every transaction, typically around 2.6% to 2.9% plus a per-transaction fee. It’s predictable and easy to budget, but at higher volumes you overpay because the actual interchange cost on many transactions is lower than the flat rate you’re paying. Interchange-plus pricing passes the actual interchange fee from the card network directly to you, then adds a transparent processor markup. Interchange-plus models pass real interchange fees at published rates like 0.3% plus $0.30, which makes your true costs visible and usually lower at higher volumes. Tiered pricing bundles transactions into “qualified,” “mid-qualified,” and “non-qualified” buckets, which sounds simple but bundled fees often mislead about actual processing costs since the processor controls which tier each transaction lands in.
Beyond the headline rate, watch for these fees in any contract:
- Monthly or annual account fees
- Chargeback fees, often $25 to $50 per dispute
- PCI DSS compliance or non-compliance fees
- Cross-border and currency conversion fees
- Hardware rental or software licensing fees
- Batch processing and statement fees
Transparent interchange-plus pricing builds real trust between processors and merchants because it lets you forecast costs accurately instead of reconciling mysterious fee line items at the end of each month. When evaluating providers, always ask for a detailed breakdown separating the interchange component from the processor markup. If a vendor won’t provide that, take it as a signal.
To understand what you will actually pay, calculate your effective rate: total fees paid divided by total volume processed. Then apply that rate to your projected monthly volume and compare across providers.
Integration quality, API support, and fraud tools
Price is visible. Integration pain is not. Until you’re three weeks into a migration and your development team is blocked on unclear documentation.
Developer tools and documentation reduce engineering integration costs and enable faster time to market. A processor with excellent API docs and a full-featured sandbox environment may cost slightly more per transaction, but the time your team saves on the integration pays back that difference quickly. You can explore API quality and integration factors in the context of choosing between gateway and processor setups to understand where these decisions intersect.
When evaluating integration quality, look at these areas specifically:
- Sandbox environment. Does it accurately simulate production behavior? Can your team test edge cases like declined cards, partial authorizations, and refunds?
- POS and platform compatibility. Verify that the processor integrates with your existing systems, whether that is Shopify, Magento, WooCommerce, or an enterprise POS.
- Fraud detection tools. Look for built-in 3D Secure 2.0 support, address verification, velocity checks, and chargeback management workflows.
- Uptime and failover. Ask for actual uptime data, not just SLA commitments. Also confirm whether the system has offline transaction queuing for periods of connectivity loss.
- Support structure. Know whether you get 24/7 technical support, a dedicated account manager, or just a ticketing system. For high-volume retailers, support quality during an outage is not optional.
Pro Tip: Before signing, send a technical question to the provider’s support team as if you were a customer. Measure the response time and quality. This one test tells you more about day-to-day support than any reference check.
Implementing your decision and verifying performance
Choosing a processor is not the finish line. Implementing it well and verifying it works as expected is where the real work happens.
- Negotiate the contract. Focus on termination clause flexibility, rate lock-in periods, and what happens if the provider changes its fee structure. Avoid contracts with long lock-ins unless you have a very strong reason to accept them.
- Run pilot transactions before full rollout. Process a small volume of real transactions across your channels before cutting over entirely. This surfaces configuration issues that sandbox testing missed.
- Train your team. Cashiers, customer service staff, and managers all interact with your payment system. Underprepared staff create checkout errors, which customers notice.
- Monitor key metrics from day one. Track transaction success rates, decline rates, average processing time, chargeback rates, and actual fees charged. Compare fees billed against your contract to catch billing errors early.
- Audit your reconciliation process. Your finance team should run monthly reconciliations that match processor settlement reports against your bank deposits and accounting records. Discrepancies often reveal hidden fees or configuration errors.
- Prepare a contingency plan. If performance falls short within the first 90 days, know your exit options. Review your termination clause so switching providers does not catch you off guard.
My perspective on what actually matters here
I’ve watched businesses spend weeks comparing logo pages on processor websites and almost no time defining what they actually need. That backward approach is why so many companies end up migrating processors 18 months after their initial setup.
In my experience, the total cost of a bad integration is always higher than the cost of a slightly higher processing rate. A processor that charges 0.1% more but offers clean documentation, responsive support, and reliable uptime will outperform a cheaper provider that costs your team 40 hours of integration debugging and adds friction at checkout.
What I’ve also learned is that the businesses that get this right treat processor selection as a recurring review, not a one-time project. Your volume changes. Your channels expand. Your customer payment preferences evolve. The processor that was the right fit at $50,000 per month may not be the right fit at $500,000 per month.
My advice: do the hard work upfront to define your business profile, run an honest scoring process, and test with real transactions. Then set a calendar reminder to revisit the decision every 12 months. Payment infrastructure is not set-and-forget.
— Vlad
How Sensepass simplifies your processor decision

If you’ve completed this evaluation process and want a payment infrastructure that gives you maximum flexibility from day one, Sensepass is built for exactly that. Sensepass is a processor-agnostic orchestration layer that lets you choose from 50+ card processors, so you’re never locked into a single provider’s rates or terms. It integrates with major platforms including NetSuite, SuiteCommerce, Oracle Xstore, Aptos, Shopify POS, BigCommerce, Storis, NCR, and Dynamics365.
Beyond card processing, Sensepass supports digital wallets (PayPal, Venmo, Apple Pay, Google Pay, WeChat, Alipay, Amazon Pay), BNPL options (Klarna, Sezzle, ZIP, Splitit, Afterpay), financing through WeGetFinancing and Affirm, crypto payments via BitPay and Coinbase, and Pay by Bank through Trustly and LinkMoney. For retailers building or refining their omnichannel payment strategy, Sensepass removes the tradeoff between payment method breadth and processing cost control.
FAQ
What is the most important first step when choosing a card processor?
Define your business profile before comparing vendors. Document your monthly volume, sales channels, existing tech stack, and compliance requirements so you can evaluate providers against real criteria rather than marketing claims.
When does interchange-plus pricing make sense?
Interchange-plus pricing typically makes sense for businesses processing more than $5,000 per month, since the transparent markup structure usually results in lower total costs compared to flat-rate models at that volume.
How do I test a card processor before committing?
Run a one-week proof-of-concept in the provider’s sandbox environment, then process a small batch of real transactions before full rollout. Measure latency, error rates, and documentation quality during the test.
What fees beyond the transaction rate should I watch for?
Watch for monthly account fees, chargeback fees, PCI compliance fees, cross-border transaction fees, and batch processing fees. Always request a detailed fee breakdown that separates interchange from processor markup before signing.
How often should I review my card processor choice?
Review your processor at least once a year, and any time your processing volume increases significantly, you add a new sales channel, or you receive a notice of fee changes from your current provider.
Recommended
- Essential Payment Gateway Selection Tips for Retailers – Omnichannel payments at the Point Of Sale | Sensepass
- Payment Processor Differences – Impact on Retail Integration – Omnichannel payments at the Point Of Sale | Sensepass
- Credit Card Payment Solutions That Transform Retail – Omnichannel payments at the Point Of Sale | Sensepass
- Payment Gateway vs Payment Processor: Key Differences for Retailers – Omnichannel payments at the Point Of Sale | Sensepass

 New York Office
260 Madison Ave Suite 8018 New York NY 10016

