
Top Omnichannel Payment Solutions 2026 – Expert Comparison
November 29, 2025
Payments have become more than just swiping a card or entering a number online. Businesses now juggle countless options for accepting money from customers whether in person, online, or over the phone. Some tools promise to bring all those payment methods together, others focus on speed or security, and a few are built just for global needs. The choice can shape how customers experience checkout and how quickly your team can manage sales. Wondering which solution fits your business goals best? The real differences come down to how each platform handles your day to day challenges and future plans.
Table of Contents
SensePass

At a Glance
SensePass is an orchestration layer and payment gateway built for retailers that need a single hub to manage online, in-store, and call-center payments. It supports a very broad set of digital payment methods and provides mobile POS, self-checkout, and virtual terminal options to unify checkout across channels. If you want to reduce friction at checkout and consolidate payment streams without juggling multiple vendors, SensePass delivers a focused, retailer-centered solution.
Core Features
SensePass centers on a unified payment hub that brings credit cards, contactless payments, and digital wallets into one flow. Core capabilities include mobile POS for in-store selling, self-checkout deployments, virtual payment terminals for call centers, and buy-by-link functionality. The platform explicitly supports over 101 digital wallets and credit card processors, positioning it as a single integration point for complex retail environments. The vendor emphasizes streamlining payments across channels to improve checkout speed and consistency for customers and staff.
Pros
- Extensive payment method coverage: SensePass supports a very wide variety of digital wallets and card processors, allowing retailers to accept the methods customers prefer.
- Omnichannel consistency: The platform unifies online, in-store, and call-center payments so you can deliver a consistent checkout experience across channels.
- Multiple form factor support: With mobile POS, self-checkout, and virtual terminals, SensePass covers the physical and remote touchpoints retailers use today.
- Operational efficiency gains: By consolidating payment processing into one hub, SensePass helps simplify reconciliation and can reduce the number of point integrations your teams must maintain.
- Conversion and cost focus: The platform is designed to reduce transaction friction and claims to lower processing costs while improving sales conversion rates.
Who It’s For
SensePass is ideal for retailers, eCommerce merchants, and service providers who need a flexible, integrated payment backbone that spans multiple sales channels. Whether you operate a single store with online orders or a chain with call-center sales and recurring subscriptions, SensePass targets businesses that want to centralize payment operations and reduce the overhead of managing separate payment tools.
Unique Value Proposition
SensePass’s distinction is its role as a true orchestration layer: rather than forcing a single payment method or processor, it brings many payment options into a single operational plane. That unified hub reduces integration sprawl and lets merchant teams deploy mobile POS, self-checkout, and virtual terminals from the same platform. This focused consolidation is a deliberate design choice—trading the complexity of multiple vendor relationships for the simplicity of one gateway that supports a very broad set of wallets and processors.
Real World Use Case
A multi-location retail chain deploys SensePass to enable contactless in-store payments, integrate online and offline transactions into one ledger, and accept a wide array of wallet and card options at checkout. The result: faster customer flows at peak times, simplified reconciliation for finance teams, and measurable reductions in failed or abandoned checkouts.
Pricing
SensePass pricing structure consist of small SaaS fee ( depend of locations count) and 0.1% fee for credit card processing and 0.2% for alternative payment options.
Website: https://sensepass.com
Adyen
At a Glance
Adyen is an end-to-end payment and financial management platform built to help medium and large businesses accept payments globally while consolidating online and in-store data. It emphasizes unified commerce, strong fraud protection using machine learning, and flexible payout and card management options. If you need a single platform to scale payments, local acquiring, and analytics, Adyen delivers a robust, data-driven foundation.
Core Features
Adyen combines online and in-store payment acceptance with unified commerce capabilities that merge transaction data across channels. The platform includes fraud management powered by machine learning and customer-friendly authentication flows, tools to gain insights from global payment data, and banking infrastructure to optimize finances and enable fast payouts. It also supports issuing physical and virtual cards and offers multi-currency support plus local acquiring to simplify market expansion.
Pros
- Comprehensive end-to-end platform: Adyen brings payments, analytics, and financial management together so you can reduce tool sprawl and centralize operations.
- Global coverage and payment variety: The platform supports multiple currencies and local acquiring, which makes expansion into new markets more straightforward.
- Strong fraud protection and analytics: Built-in machine learning for fraud detection helps protect revenue while preserving good customer experiences.
- Flexible payout and card management: Options for fast payouts and issuing physical or virtual cards give finance teams more control over cash flow.
- Transparent cost model for setup: With no setup or monthly fees and a pay-per-transaction model, there’s a lower barrier to entry for large-scale deployments.
Cons
- Pricing complexity by region and method: Pricing varies by payment method and region, which can make cost forecasting and comparisons difficult.
- Potentially high fees in some markets: Certain countries or payment types may incur relatively high fees, which can erode margins for thin-margin merchants.
- Support quality may vary: Customer support and service experience can differ by region, so implementation and ongoing support may not be uniform across all markets.
Who It’s For
Adyen is best suited for medium to large retailers, marketplaces, and global e-commerce companies that require a scalable, unified commerce solution. If you operate across multiple channels or plan to expand into international markets and need consolidated payment data, Adyen provides the tooling and infrastructure to support that growth.
Unique Value Proposition
Adyen’s value lies in combining payments, fraud management, and financial tooling into a single platform that scales across channels and geographies. The unified commerce approach means teams get consolidated data and faster financial operations without stitching together multiple vendors.
Real World Use Case
A global e-commerce merchant integrates Adyen to accept diverse local payment methods and currencies, uses the platform’s machine learning to reduce fraud-related chargebacks, and speeds cash flow through optimized payouts and virtual card issuance for vendor payments.
Pricing
Adyen operates on a pay-per-transaction model with no setup or monthly fees; pricing comprises fixed processing fees plus variable fees that depend on payment method and region.
Website: https://adyen.com
Komoju
At a Glance
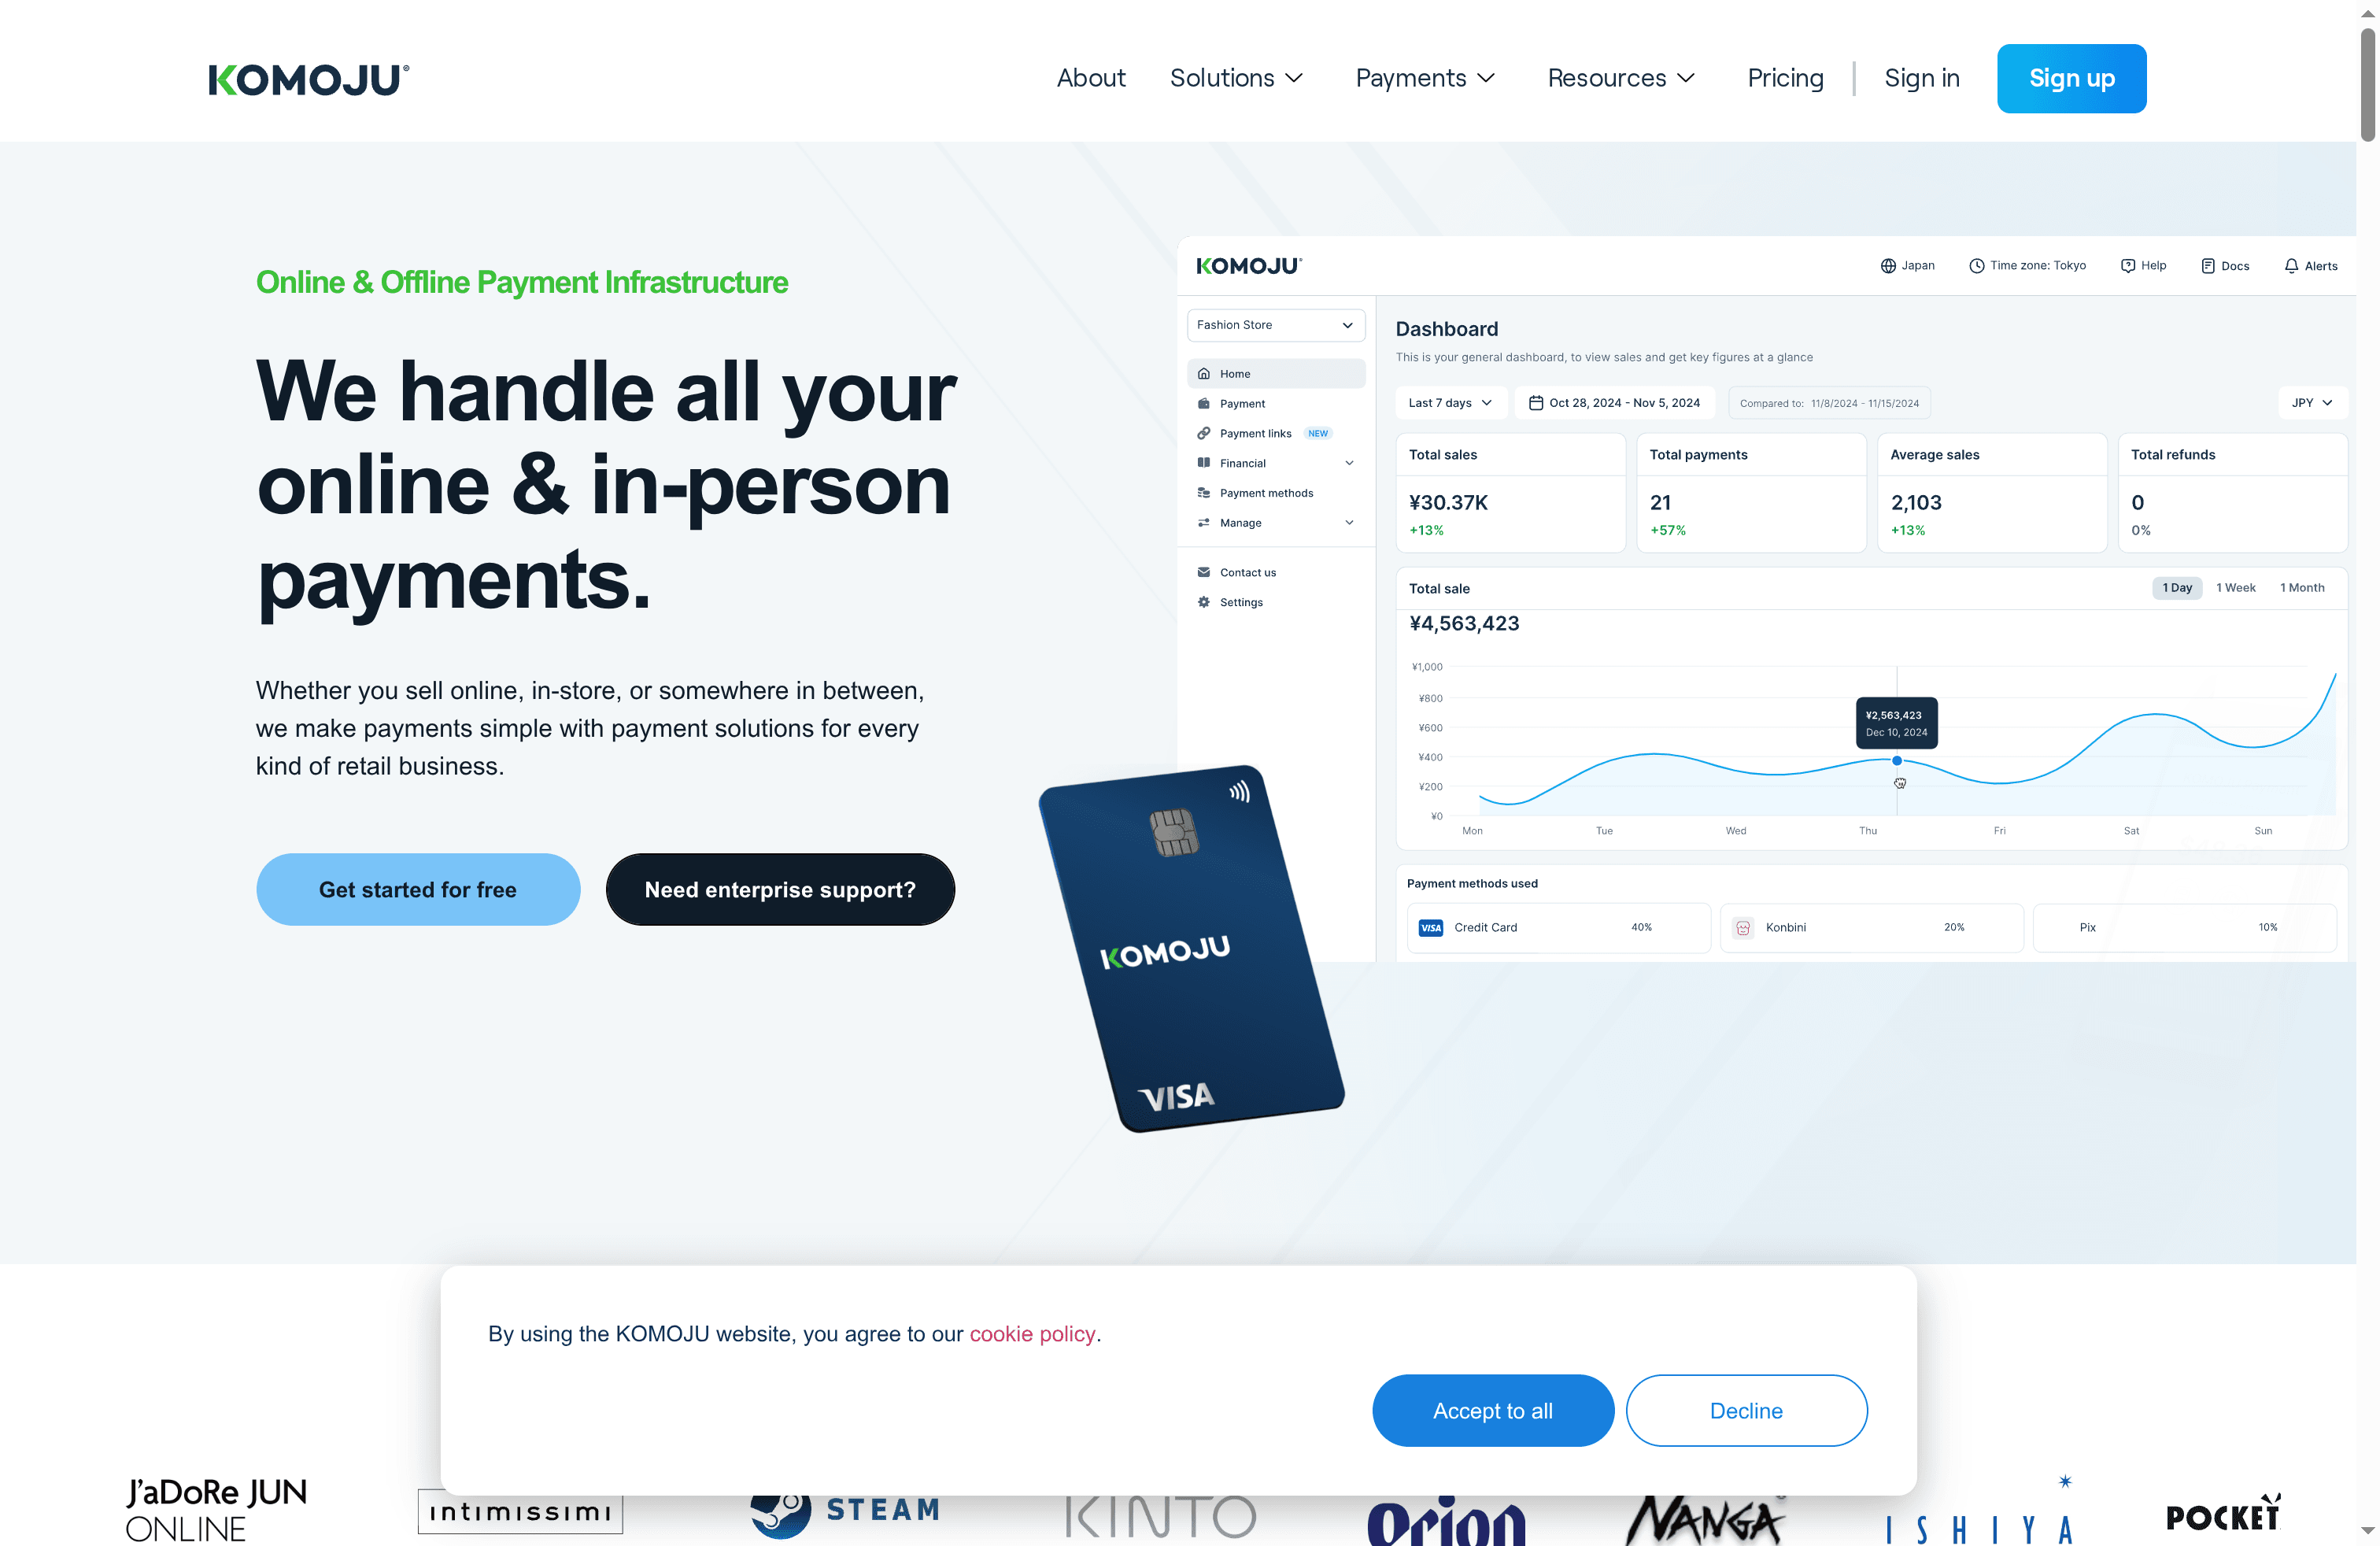
Komoju is a regionally aware payment platform that blends online and offline payments into a single, scalable infrastructure. It supports more than 65 payment methods across credit/debit, bank transfers, e-wallets, and prepaid cards, and includes in-store tools like a Komoju Terminal and Tap to Pay. If you need multi-regional coverage and reliable uptime, Komoju delivers strong security and transaction continuity; however, initial configuration can be complex for teams without dedicated payment expertise.
Core Features
Komoju offers API and low-code integration options for e-commerce platforms, payment links for ad-hoc or custom orders, and in-store hardware and contactless options through Komoju Terminal and Tap to Pay. The platform’s Komoju Card provides instant access to sales revenue, while its catalog of 65+ payment methods targets local preferences across regions such as Japan, Korea, China, Europe, and Brazil. These capabilities make Komoju equally suitable for web storefronts, mobile checkouts, and brick-and-mortar terminals.
Pros
- Wide regional coverage: Komoju supports a broad array of locally preferred payment methods tailored for markets like Japan, Korea, China, Europe, and Brazil, helping reduce conversion friction in each region.
- Flexible integration options: The platform provides both API and low-code integration paths, making it easier for technical and nontechnical teams to connect Komoju to e-commerce systems.
- Transaction-based pricing model: There are no sign-up or monthly fees listed; merchants pay per transaction, which simplifies cost planning for low-volume sellers.
- Strong security and compliance: Komoju advertises high security standards with PCI DSS and ISO-level compliance, which reduces risk and supports regulatory requirements.
- High reliability: The platform claims the ability to handle high transaction volumes with 99.99% uptime, supporting peak retail periods and large-sale events.
Cons
- Complex regional customization: The extensive options for regional payment methods can complicate initial setup and require careful configuration to avoid misrouted or unsupported payment flows.
- Unclear international support details: The provided content lacks specifics about international customer support and onboarding, which could leave teams uncertain about time-to-live and operational help.
- Online dependency: Komoju’s online transactions depend on internet connectivity, so merchants must plan for network redundancy or offline contingencies to avoid interruptions.
Who It’s For
Komoju is aimed at retailers and online merchants of all sizes that need a flexible, secure, and multi-regional payment platform. It fits especially well for e-commerce businesses expanding into Asia and Europe, retail stores that require contactless in-store payments, and organizations that want payment links for bespoke ordering workflows.
Unique Value Proposition
Komoju’s unique value lies in combining extensive local payment method support with both online and offline acceptance tools, plus quick-access funds via Komoju Card. That mix makes it an attractive single-vendor option for merchants pursuing global reach while honoring local payment habits.
Real World Use Case
A Japanese e-commerce seller integrates Komoju to accept credit cards, convenience store payments, and bank transfers, enabling seamless local and cross-border transactions while preserving security and conversion rates across multiple customer touchpoints.
Pricing
Komoju charges only a percentage of transactions processed; specific rates are not provided in the available content, so merchants should request a customized rate card during onboarding.
Website: https://komoju.com
Paystand
At a Glance
Paystand is a B2B-focused payments-as-a-service platform built as a SaaS layer on blockchain, designed to digitize receivables and payables while eliminating many per-transaction costs. Its strengths are predictable subscription pricing, deep ERP integrations, and bank-payment networks that remove transaction fees inside the ecosystem. If you run finance or accounting operations in a mid-sized or large enterprise and want to cut Days Sales Outstanding (DSO) and simplify reconciliation, Paystand warrants a close look.
Core Features
Paystand centralizes accounts receivable and payable automation, collections automation, and real-time payment reconciliation, backed by blockchain-based immutable transaction records for auditability and security. The platform includes a self-service payment portal that accepts multiple methods—bank transfer, ACH, eCheck, credit card—and removes transaction fees for bank payments within Paystand’s network. It also supports international and cross-border payments, expense management and corporate cards, spend analytics, procurement support, and native integrations with major ERPs and accounting systems such as NetSuite, Sage Intacct, Dynamics 365, QuickBooks Online, and Xero.
Pros
- Zero transaction fees for bank payments within the network — Merchants processing bank transfers inside Paystand’s network avoid per-transaction fees, lowering cost of receivables.
- Blockchain-based auditability — Immutable transaction records provide transparent, tamper-proof trails that simplify compliance and audits.
- End-to-end automation reduces manual work — Automation across receivables, payables, collections, and reconciliation shortens DSO and cuts back on manual interventions.
- ERP and accounting integrations — Native connectors to leading systems like NetSuite and Dynamics 365 enable seamless workflows and reduce reconciliation friction.
- Predictable subscription pricing — Flat monthly rates improve budgeting and forecasting versus variable fee models.
Cons
- Requires existing digital infrastructure — To unlock full benefits you need integrated ERP systems and digitized invoice workflows, which may demand implementation effort.
- Not ideal for very small or non-digitized businesses — Organizations without digital billing or that rely heavily on cash or manual invoicing may find limited value.
- Learning curve around blockchain and SaaS workflows — Finance teams unfamiliar with blockchain or modern SaaS payment flows should expect a ramp-up period.
Who It’s For
Paystand is built for finance and accounting teams in mid-sized to large enterprises that prioritize automation, faster time-to-cash, and better auditability. It fits organizations that already use ERPs like NetSuite or Dynamics 365 and are ready to migrate receivables and payables onto a digitized, subscription-priced payment platform.
Unique Value Proposition
Paystand’s unique value lies in combining subscription-based pricing with blockchain-backed transparency and a bank-payment network that eliminates fees for in-network transfers. That mix offers predictable costs, faster reconciliation, and an auditable payment history—appealing to organizations that must optimize working capital and compliance simultaneously.
Real World Use Case
A manufacturing company used Paystand to automate receivables collection, cutting its DSO by 30% while eliminating transaction fees for bank transfers processed in the platform’s network; blockchain records maintained compliance-ready audit trails throughout the process.
Pricing
Subscription-based model with transparent flat monthly rates; no transaction fees on bank transfers within Paystand’s network, with optional service fees for add-on features or card payments. Pricing requires evaluation against current fee-based arrangements to quantify ROI.
Website: https://paystand.com
Adyen
At a Glance
Adyen is a unified payments platform that combines end-to-end payment acceptance, fraud management, and financial controls into a single system. It excels at supporting online, in-app, and in-person transactions for businesses that need global reach and multiple payment methods. For merchants scaling across channels and currencies, Adyen reduces operational friction while exposing richer payment data for decision-making. It’s powerful, but organizations should expect some integration complexity depending on their tech stack.
Core Features
Adyen’s core is a single platform that handles payments and financial management across online, in-app, and brick-and-mortar channels. The platform includes machine learning–driven fraud detection, unified commerce that links offline and online payment data, flexible payout and currency options, and a consolidated data ecosystem for analytics. Together these capabilities let merchants accept diverse payment methods and gain actionable insights without stitching together multiple vendors.
Pros
- No setup or monthly fees: merchants pay per transaction, which can simplify budgeting and lower upfront costs.
- Broad payment and currency support: the platform accepts a wide range of payment methods and currencies, enabling global commerce.
- Fully integrated platform: Adyen combines acceptance, protection, and financial operations into one system, reducing vendor sprawl.
- Flexible payout and card options: businesses can use virtual and physical payment cards and customize payout flows for marketplaces and platforms.
- Strong data ecosystem: consolidated payment data and analytics help teams identify growth opportunities and strengthen security.
Cons
- Pricing complexity: transaction costs vary by payment type and region, which can make side-by-side comparisons and forecasting more difficult.
- Limited eligibility for some models: certain industries or business models may not qualify for processing, creating onboarding risk.
- Integration demands: implementation and setup can require significant technical resources for complex or highly customized environments.
Who It’s For
Adyen fits businesses that need a scalable, global payments backbone—digital merchants, omnichannel retailers, marketplaces, and platforms that require consistent processing across online, mobile, and physical channels. If you operate in multiple currencies, value unified payment data, and want to avoid juggling separate payment, fraud, and payout vendors, Adyen is aimed at you.
Unique Value Proposition
Adyen’s primary advantage is delivering end-to-end payments and finance tools within a single platform that bridges online and offline commerce. That unified approach reduces integration overhead, centralizes fraud defenses, and elevates payment data into a single source of truth for operations and growth decisions.
Real World Use Case
A global e-commerce marketplace uses Adyen to accept online and in-app payments, route payouts to sellers in multiple currencies, and run consolidated fraud checks across channels. The unified data feeds analytics teams with transaction patterns that inform pricing, acceptance rules, and dispute handling.
Pricing
Adyen charges on a pay-per-transaction basis with no setup or monthly fees; pricing consists of a fixed processing fee plus payment method and region-specific fees. Because costs vary by payment type and geography, merchants should request a tailored rate card to model true costs per transaction.
Website: https://adyen.com
Payment Gateway Tools Comparison
This table provides an overview of several payment gateway solutions, highlighting their key features, pros, cons, target audience, and pricing information. Use it to compare and choose the best solution for your business needs.
| Tool | Key Features | Pros | Cons | Pricing |
|---|---|---|---|---|
| SensePass | Unified payment hub, mobile POS, self-checkout, virtual terminals, over 101 digital wallets | Extensive payment coverage, omnichannel consistency, operational efficiency | No specific cost details available | Contact for a tailored quote |
| Adyen | Unified payments, fraud management, analytics, multi-currency support | Comprehensive platform, global coverage, strong fraud protection | Pricing complexity, support quality may vary | Pay-per-transaction model |
| Citcon | Single API, over 100 payment methods, multi-currency support, built-in compliance | Broad payment coverage, operational cost savings, fast deployment | High setup and ongoing costs, complex vertical solutions | Enterprise pricing, contact for details |
| Komoju | 65+ payment methods, API and low-code integration, in-store tools like Komoju Terminal | Wide regional coverage, flexible integration, strong security and compliance | Complex regional setup, unclear international support | Transaction-based model, request rate card |
| Paystand | ERP integration, blockchain-based auditability, zero bank fees within network | Subscription pricing, end-to-end automation, transparent transaction records | Requires digital infrastructure, not ideal for non-digitized businesses | Subscription-based model |
Discover the Power of True Omnichannel Payment Integration
Retailers face the growing challenge of unifying diverse payment methods across online stores, physical locations, and call centers while maintaining smooth customer experiences. If you are searching for a flexible payment solution that supports a vast range of digital wallets, BNPL options, crypto payments, and traditional cards without the headache of juggling multiple processors, SensePass offers a uniquely streamlined approach. With seamless integrations into major POS systems like Shopify POS, NetSuite, Oracle Xstore, Aptos, and Dynamics365, SensePass eliminates friction and operational complexity while boosting conversion rates and reducing costs.
Experience a payment gateway that puts flexibility first. SensePass supports over 50 card processors and popular digital wallets such as PayPal, Venmo, Apple Pay, and WeChat. It also provides BNPL solutions including Klarna and Afterpay, crypto payment acceptance like Coinbase and BitPay, plus pay-by-bank methods to meet modern customer preferences. If your goal is to deliver consistent, contactless, and fast checkout experiences across every channel, explore the full SensePass platform. The future of retail payments starts with a single integration designed for your omnichannel needs.
Enhance your business’s payment infrastructure today. Visit SensePass.com to learn how you can unify payment acceptance, simplify management, and empower shoppers with choices that drive sales growth.
Get started with SensePass now and transform how you accept payments across every channel.
Frequently Asked Questions
What should I consider when choosing an omnichannel payment solution for 2025?
When choosing an omnichannel payment solution, consider factors like transaction speed, payment method coverage, and ease of integration with your existing systems. Evaluate how well each solution aligns with your customer preferences and the specific channels you operate in.
How can an omnichannel payment solution improve my business operations?
An omnichannel payment solution can streamline payment processing across multiple channels, reducing friction for customers and simplifying reconciliation for your finance team. To maximize benefits, implement a solution that unifies both online and offline transactions, potentially reducing operational costs by up to 20%.
What types of payment methods should an ideal omnichannel solution support?
The ideal omnichannel payment solution should support a wide array of payment methods, including credit/debit cards, digital wallets, and contactless payments. Assess your target audience’s preferences and prioritize solutions that provide the methods most commonly used by your customers.
How long does it take to implement an omnichannel payment solution?
Implementation timelines can vary significantly based on the complexity of your systems and the solution selected; however, many businesses complete integration within 30–60 days. Start by planning for a thorough needs assessment to ensure a smoother setup process.
Can an omnichannel payment solution help reduce chargebacks and fraud?
Yes, many omnichannel payment solutions include advanced fraud detection mechanisms that can help lower chargeback rates. To enhance your security measures, choose a platform that utilizes machine learning technology to analyze transactions in real-time, potentially decreasing fraudulent activities by approximately 30%.
Recommended
- 7 Essential Tips for Your Omnichannel Payment Methods List – Omnichannel payments at the Point Of Sale | Sensepass
- Complete Guide to Omnichannel Payments for Retailers – Omnichannel payments at the Point Of Sale | Sensepass
- What Is Omnichannel Retail? Complete Guide for 2025 – Omnichannel payments at the Point Of Sale | Sensepass
- What Is Omnichannel Payment? Complete Guide for Retailers – Omnichannel payments at the Point Of Sale | Sensepass

 New York Office
260 Madison Ave Suite 8018 New York NY 10016

