
Your Guide to Flexible Payment Options in Retail
May 26, 2026
TL;DR:
- Flexible payment options, including BNPL, digital wallets, and pay-by-bank, enhance checkout conversion and customer satisfaction. Proper preparation involves verifying platform compatibility, adhering to PCI DSS v4.0, and managing scripts continuously to ensure security and compliance. Implementing these methods gradually and monitoring their performance helps merchants deliver seamless, secure, and flexible payment experiences across channels.
When a customer reaches your checkout and their preferred payment method isn’t available, they leave. It’s that simple. A rigid payment setup doesn’t just cost you that one sale. It signals to customers that their preferences don’t matter. This guide to flexible payment options walks retail and eCommerce business owners through every stage of expanding payment choice — from understanding what’s available, to preparing your systems, to running a secure, compliant setup that converts. If you’re ready to stop losing sales at checkout, this is where to start.
Table of Contents
- Key Takeaways
- A Guide to Flexible Payment Options for Retailers
- What to prepare before adding payment methods
- How to enable flexible payment methods step by step
- Verifying and managing payment flexibility over time
- My take on flexible payments after years in the industry
- How Sensepass helps you offer flexible payment choices
- FAQ
Key Takeaways
| Point | Details |
|---|---|
| Offer multiple payment methods | Covering BNPL, digital wallets, and pay-by-bank captures more customers across different spending habits. |
| Prepare before you launch | Audit your current platform compatibility and PCI DSS requirements before adding new payment methods. |
| Keep provider count manageable | Two to three BNPL providers covers most needs without creating checkout confusion. |
| Monitor scripts continuously | PCI DSS v4.0 requires ongoing script management on payment pages, not just point-in-time audits. |
| Use a processor-agnostic platform | Choosing a flexible payment orchestration layer gives you more control over costs and provider selection. |
A Guide to Flexible Payment Options for Retailers
The term “flexible payment options” covers a broad range of methods that go beyond the standard credit and debit card. Understanding what each category does, and which customer segment it serves, is the first step in building a smarter checkout experience.
Buy Now, Pay Later (BNPL) has moved from novelty to expectation for many shoppers. Klarna offers multiple BNPL structures including pay-in-4, pay-in-30 days, and longer financing over 6 to 36 months with variable APR. Transaction fees run between 3.29% and 5.99% plus $0.30 per transaction, with no setup or monthly fees. That fee range is meaningful when you’re comparing providers at scale. Other strong BNPL options include Sezzle, ZIP, Splitit, and Afterpay, each with slightly different approval models and consumer audiences.
Digital wallets have become the fastest checkout path at both POS and online. Apple Pay, Google Pay, PayPal, Venmo, Amazon Pay, WeChat, and Alipay each carry different demographic strengths. Apple Pay dominates iOS users in North America. Alipay and WeChat are non-negotiable if you serve Chinese shoppers. Offering a mix of wallets isn’t redundant. It’s strategic coverage.
Financing solutions from providers like Affirm and WeGetFinancing serve higher average order values. A customer considering a $1,200 piece of furniture or a $900 piece of tech equipment is more likely to complete the purchase when monthly payment options appear at checkout.
Pay-by-bank options like Trustly and LinkMoney bypass card networks entirely. For merchants, this often means lower processing fees and faster settlement. For customers, it’s a direct, familiar payment flow from their bank account.
Payment links and digital invoicing are often overlooked in flexibility discussions. Merchants can accept payments without a website at all, using payment links sent by email or SMS, which makes this model ideal for B2B transactions, service providers, and situations where a full eCommerce checkout isn’t practical. You can review the full spectrum of methods in this overview of retail payment methods to understand where each fits your business model.
Crypto payments through BitPay and Coinbase Commerce are still niche but growing. They attract a specific, tech-forward customer base and carry zero chargeback risk for merchants, which is worth factoring into your risk calculations.
What to prepare before adding payment methods
Adding payment methods without proper preparation can create compliance gaps, integration failures, and customer-facing errors. Before you flip any switch, work through these foundational checks.
- Platform compatibility. Not every payment provider works natively with every platform. Shopify, BigCommerce, WooCommerce, Magento, and POS systems like NetSuite, Oracle Xstore, and Dynamics365 each have different integration paths. Confirm that your chosen provider has a tested, supported integration before committing.
- PCI DSS v4.0 requirements. All scripts on payment pages, including marketing and analytics scripts, are now in scope under PCI DSS v4.0. Merchants must maintain an active inventory, provide business justification for each script, and implement integrity controls. This isn’t a one-time task. It’s a continuous obligation.
- Script management readiness. Adding payment scripts can load external code that creates e-skimming vulnerabilities if not managed. Every new payment integration you add to a checkout page requires security review and ongoing monitoring.
- Cash flow and accounting alignment. BNPL providers generally pay merchants upfront. Shop Pay Installments, for example, pays the merchant the full transaction amount immediately while the customer repays in installments. Your accounting team needs to understand how different providers handle settlement timing, fees, and reconciliation.
- Customer geography and order values. A pay-in-4 product optimized for $50 to $500 orders doesn’t serve the same purpose as a 36-month financing option for high-ticket items. Match your provider selection to your actual order value distribution and customer location.
Pro Tip: Before signing with any new payment provider, check whether your payment gateway or orchestration layer already supports that provider natively. Adding through an existing integration is almost always faster and cheaper than a standalone direct integration.
How to enable flexible payment methods step by step
This is the execution layer. Follow these steps to move from preparation to live payment options without creating friction in your existing checkout.
-
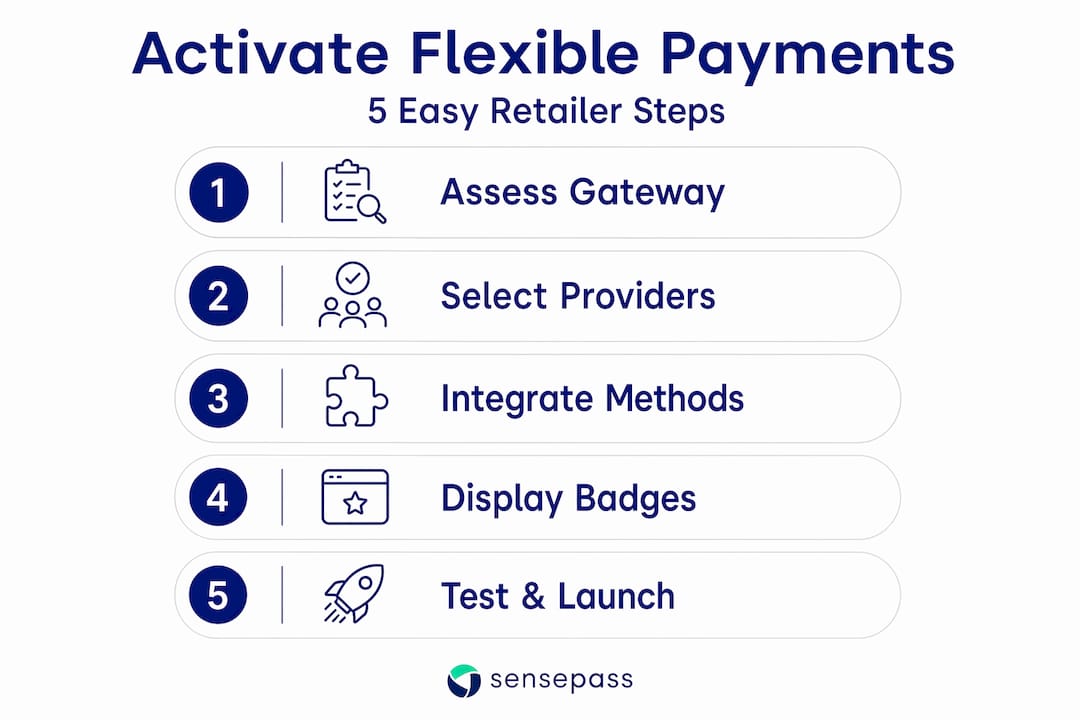
Audit your current checkout flow. Document every payment method currently active, where each appears in the checkout sequence, and what the fallback is when a method fails. This baseline helps you spot gaps and avoid duplicating effort.
-
Activate BNPL on your platform. On Shopify, native BNPL integration accelerates deployment and reduces maintenance compared to third-party apps. Shop Pay Installments activates through a native toggle in your Shopify Payments settings, covering the pay-in-4 use case with no separate app required. For providers not natively supported, evaluate whether a third-party app or a payment orchestration layer is the cleaner path. You can find specific setup guidance for Klarna on Shopify POS if that provider is on your shortlist.
-
Set up payment links and invoicing tools. For transactions outside your main storefront, configure a payment link tool through your gateway or invoicing platform. Payment links sent by email or SMS expand your sales reach beyond the standard cart, serving B2B clients, phone orders, and service transactions efficiently.
-
Integrate digital wallets at POS and online. Wallet integration at the physical POS often requires NFC-enabled hardware. Online, most major gateways support Apple Pay and Google Pay through standard API configuration. Confirm that your checkout page displays wallet options on mobile browsers, where they appear as one-tap checkout buttons.
-
Limit provider count to avoid friction. Two to three BNPL providers covering native and third-party options satisfies the majority of customer needs without overwhelming the checkout experience. More than that starts to create visual clutter and decision paralysis.
-
Test every new payment flow before going live. Run test transactions through each method, on both desktop and mobile. Check that error states display clearly, that confirmation emails fire correctly, and that orders appear properly in your backend with the right payment method label.
Here’s a comparison of the most common BNPL approaches by setup path and merchant benefit:
| BNPL Provider | Setup Path | Merchant Payout | Best For |
|---|---|---|---|
| Shop Pay Installments | Native Shopify toggle | Upfront, full amount | Shopify merchants, $50–$3,000 orders |
| Klarna | App or API integration | Upfront, full amount | Broad order range, EU and US markets |
| Afterpay | App or direct integration | Upfront, full amount | Fashion, lifestyle, mid-range price points |
| Affirm | Direct integration or Shopify app | Upfront, full amount | High-ticket items, 6–36 month financing |
| Sezzle | App integration | Upfront, full amount | Budget-conscious shoppers, US and Canada |
Pro Tip: Place your most recognizable payment badges, Apple Pay, PayPal, and Klarna, near the price on product pages, not only at checkout. Customers make purchase decisions earlier than most merchants assume, and seeing a familiar payment method before they add to cart increases conversion.
Verifying and managing payment flexibility over time
Going live is not the finish line. Ongoing management is where compliant, high-performing payment setups separate themselves from the ones that create risk and erode trust.
The most critical post-launch obligation under PCI DSS v4.0 is script management. Continuous monitoring and authorization of scripts on payment pages significantly reduces e-skimming risk. A script that was legitimate when you first integrated a payment provider can be compromised weeks later. Your monitoring system needs to detect unauthorized changes in real time, not during quarterly reviews.
Beyond compliance, track the performance of each payment method as a discrete metric. The table below outlines the key areas to monitor and what action each metric should trigger:
| Metric | What to monitor | Action threshold |
|---|---|---|
| BNPL conversion rate | Orders completed using BNPL vs. total orders | Below 5% may indicate poor placement or messaging |
| Wallet adoption rate | Percentage of mobile orders using Apple Pay or Google Pay | Low rate suggests wallet buttons aren’t appearing correctly |
| Payment failure rate | Failed transactions per method | Above 2% warrants provider or integration review |
| Script inventory count | Number of active scripts on checkout pages | Any unauthorized addition triggers immediate review |
| Settlement accuracy | Reconciled payouts vs. expected amounts per provider | Discrepancies flag accounting or integration issues |
Beyond the numbers, gather customer feedback through post-purchase surveys. Ask specifically whether customers found a payment method they trusted. That qualitative signal tells you what the conversion data can’t: whether customers left before checkout because of perceived payment risk.
Regularly review your provider contracts for fee changes, coverage updates, and compliance obligations. Payment providers update their terms, and a fee increase that looks small on one transaction compounds significantly across thousands of orders monthly.
My take on flexible payments after years in the industry
I’ve worked closely with retailers at every scale, from single-location boutiques to multi-channel operations running across POS, eCommerce, and call center environments. The pattern I keep seeing is the same: businesses add payment methods reactively, usually after a competitor does, and skip the groundwork entirely.
The BNPL category is a good example. Merchants activate it expecting a conversion lift and get one, initially. But without tracking which provider is actually performing, they end up carrying three or four providers, each with separate reconciliation requirements, separate compliance obligations, and separate fee structures. The initial gain erodes into operational complexity.
What I’ve found actually works is treating payment flexibility as a deliberate architecture decision, not a feature toggle. Start with your highest-value customer segments and work backward to the methods they actually use. A mid-market furniture retailer and a fast-fashion eCommerce brand have almost no overlap in optimal payment mix, even though both would benefit from BNPL.
The compliance piece is where I see the most avoidable risk. Merchants often treat payment page security as a setup task. PCI DSS v4.0 changed that permanently. Every script on your checkout page is now a managed asset with documentation, authorization, and monitoring requirements. That’s not bureaucracy. It’s protection against e-skimming attacks that can compromise customer card data silently over weeks.
My practical advice: choose a processor-agnostic platform that handles the orchestration layer for you. It gives you the flexibility to add or swap providers without rebuilding integrations from scratch. It also centralizes your compliance monitoring instead of fragmenting it across five separate dashboards.
— Vlad
How Sensepass helps you offer flexible payment choices
If you’ve worked through this guide and you’re now looking at a list of providers, integrations, and compliance tasks, Sensepass is built to simplify that entire stack.

Sensepass is a processor-agnostic payment orchestration platform that integrates with major retail systems including NetSuite, SuiteCommerce, Oracle Xstore, Aptos, Shopify POS, BigCommerce, Storis, NCR, and Dynamics365. On the payment method side, Sensepass supports digital wallets (PayPal, Venmo, WeChat, Apple Pay, Google Pay, Alipay, Amazon Pay), BNPL providers (Klarna, Sezzle, ZIP, Splitit, Afterpay), financing options (WeGetFinancing, Affirm), crypto payments (BitPay, Coinbase), and pay-by-bank solutions (Trustly, LinkMoney). Merchants also get access to 50+ card processors for maximum processing flexibility. For a full picture of how this works across channels, the omnichannel payments guide covers every use case from POS to self-checkout to eCommerce.
FAQ
What are flexible payment options for retailers?
Flexible payment options include BNPL, digital wallets, financing, pay-by-bank, payment links, and crypto payments. They give customers more ways to complete a purchase, which reduces cart abandonment and increases conversion.
How many BNPL providers should I offer?
Two to three providers is the recommended range. A native platform option combined with one or two third-party providers covers most customer needs without creating checkout friction.
Do BNPL providers pay merchants upfront?
Yes, in most cases. Shop Pay Installments pays the full merchant amount immediately, even though customers repay in installments. Most major BNPL providers follow the same structure.
What is PCI DSS v4.0 and why does it affect payment pages?
PCI DSS v4.0 requires merchants to maintain inventories of all scripts on payment pages, authorize each one, and detect unauthorized changes continuously. This applies to every script on a checkout page, not just payment-specific code.
Can I accept payments without an eCommerce website?
Yes. Payment links sent by email or SMS let merchants collect payments without a website or full eCommerce platform. This approach works well for B2B transactions, service businesses, and phone-based orders.
Recommended
- 7 Types of Retail Payment Methods for Your Business – Omnichannel payments at the Point Of Sale | Sensepass
- Understanding Must-Have Retail Payment Features – Omnichannel payments at the Point Of Sale | Sensepass
- Power your sales with payment-integrated online forms – Omnichannel payments at the Point Of Sale | Sensepass
- 7 Essential Mobile Payment Solutions List for Retailers – Omnichannel payments at the Point Of Sale | Sensepass

 New York Office
260 Madison Ave Suite 8018 New York NY 10016

